


EN
Is Rich P E Valuation Altering The Investment Case For Capricorn Metals Shares?
- Capricorn Metals is under fresh scrutiny after sustained strong returns left its shares trading on an elevated P/E multiple relative to current earnings power and project delivery risks.
- The key issue now is whether Capricorn Metals’ existing mine performance and development pipeline can justify a valuation that already assumes ambitious future profitability.
- This reassessment of Capricorn Metals’ valuation against its earnings profile could reshape the company’s investment narrative.
Pressure test Capricorn Metals’ rich P/E against peers and search for other producers with sturdier earnings support using our curated 33 elite gold producer stocks
Capricorn Metals Investment Narrative Recap
To stay invested in Capricorn Metals, you need to be comfortable that Karlawinda keeps delivering steady production and that Mt Gibson is built broadly in line with current study assumptions on timing, capex and costs. The big short term swing factor is still execution on Mt Gibson, since that project is central to the 400,000 ounce per year production ambition.
The main operational risk is that capital costs, all in sustaining costs or ramp up timing at Mt Gibson differ from current estimates, especially with a fresh spotlight on the rich P/E multiple. The recent scrutiny of valuation does not change those physical project risks, but it can sharpen market reactions if delivery slips.
Recent commentary has leaned heavily on the updated Mt Gibson pre feasibility study, which outlines a 19.25 year mine life, around 3.5 million ounces of production and an estimated A$12b in pre tax free cash flow. For Capricorn Metals, that study effectively defines what investors are underwriting when they look past the current earnings base.
That same update highlights an estimated A$474 million in pre production capital, a forecast 14 month payback period and projected all in sustaining costs of A$1,870 per ounce. Those numbers frame both the opportunity and the risk, because any material deviation in build cost, ramp up or unit costs would directly affect the cash flow profile underlying today’s premium P/E.
Capricorn Metals’ current narrative points to A$2.0b of revenue and A$863.3 million of earnings by 2029, anchored to analyst forecasts that assume revenue expands by 40.9% per year and earnings rise from A$282.2 million today, roughly tripling over that period.
Uncover why Capricorn Metals' fair value indicates a 40% potential upside to its current price before that discount closes.
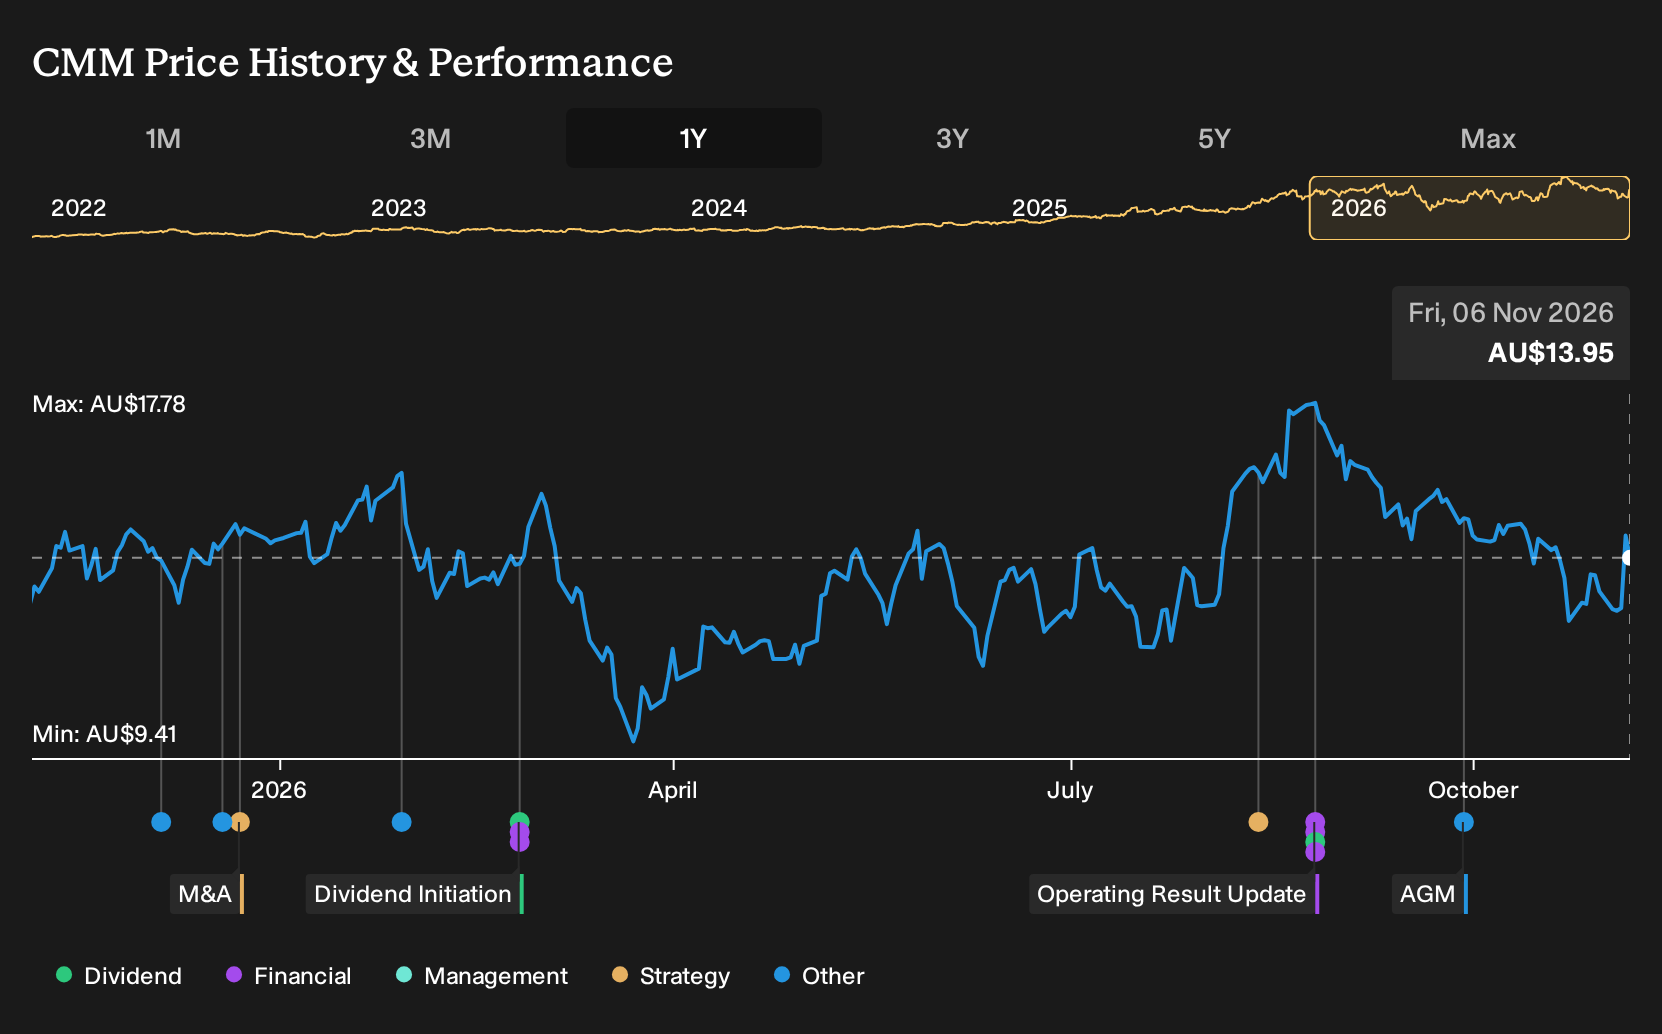
Exploring Other Perspectives
One alternate view on Capricorn Metals leans heavily on upside from the Golden Range processing hub. Bullish analysts were pencilling in A$2.3b of revenue and about A$1.0b of earnings by 2029, compared with the baseline A$2.0b and A$863.3 million. Your takeaway is that credible opinions already span a wide range, and this latest news could prompt those narratives to shift again.
Explore 4 other Capricorn Metals fair value estimates, including one that suggests as much as 219% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Capricorn Metals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Capricorn Metals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capricorn Metals' overall financial health at a glance.
Looking For More Ideas Beyond Capricorn Metals?
If the valuation debate around Capricorn Metals has sharpened your thinking, use that momentum to broaden your watchlist. The Simply Wall St Screener can help you quickly filter for other businesses that better fit your risk tolerance and return goals.
- If you want companies where quality and pricing look more aligned, start with a tight short list of 4 high quality undervalued stocks that already clear high fundamental hurdles.
- If capital preservation sits high on your agenda, focus on resilience first and check out a curated set of 6 resilient stocks with low risk scores that score well on stability metrics and balance sheet strength.
- If you are hunting for fresh ideas the market may have overlooked, cast a wider net across 14 high quality undiscovered gems with solid fundamentals that are still off most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com