


EN
Alibaba Group Holding (BABA) Could Be 55% Undervalued After Dakar 2026 Cloud Win
Alibaba Group Holding (NYSE:BABA) is back in the spotlight after announcing it will run the digital backbone of the Dakar 2026 Youth Olympic Games using its cloud and AI technology.
These Dakar 2026 headlines land at a time when Alibaba Group Holding has seen its share price fall 30.61% year to date and its 1-year total shareholder return decline 34.94%. However, the latest 7-day share price return of 8.57% hints at short-term momentum stabilising after a weaker 90-day stretch that left the stock down 15.84%.
Spot opportunities across AI infrastructure by scanning the hand picked 53 AI infrastructure stocks powering everything from global events like Dakar 2026 to everyday cloud and data workloads.For Alibaba Group Holding, a 7 day rebound against a much weaker year tells two stories. Is this a reassessment of the business, or just sentiment snapping back before the valuation work really starts?
Most Popular Narrative: 55% Undervalued
Alibaba Group Holding closed at $108.07, while the most followed narrative on the stock pins fair value at $241.91. This frames the Dakar 2026 contract as just one piece of a much larger value gap story.
Alibaba is one of the few large-cap companies in the world where there appears to be a meaningful gap between market perception and the underlying value of its assets. At current prices, many investors still view Alibaba primarily as a Chinese e-commerce company. However, a closer look reveals a much broader technology ecosystem with exposure to some of the most important long-term trends in AI, cloud computing, fintech, and digital infrastructure.
See why 18 investors see Alibaba Group Holding as 55% undervalued.
Result: Fair Value of $241.91 (UNDERVALUED)
Still, the Alibaba Group Holding narrative can strain quickly if sentiment toward China weakens again or if cloud and AI projects demand heavier, lower-return investment.
Find out about the key risks to this Alibaba Group Holding narrative.
Another View: What Alibaba Group Holding's P/E Ratio Signals
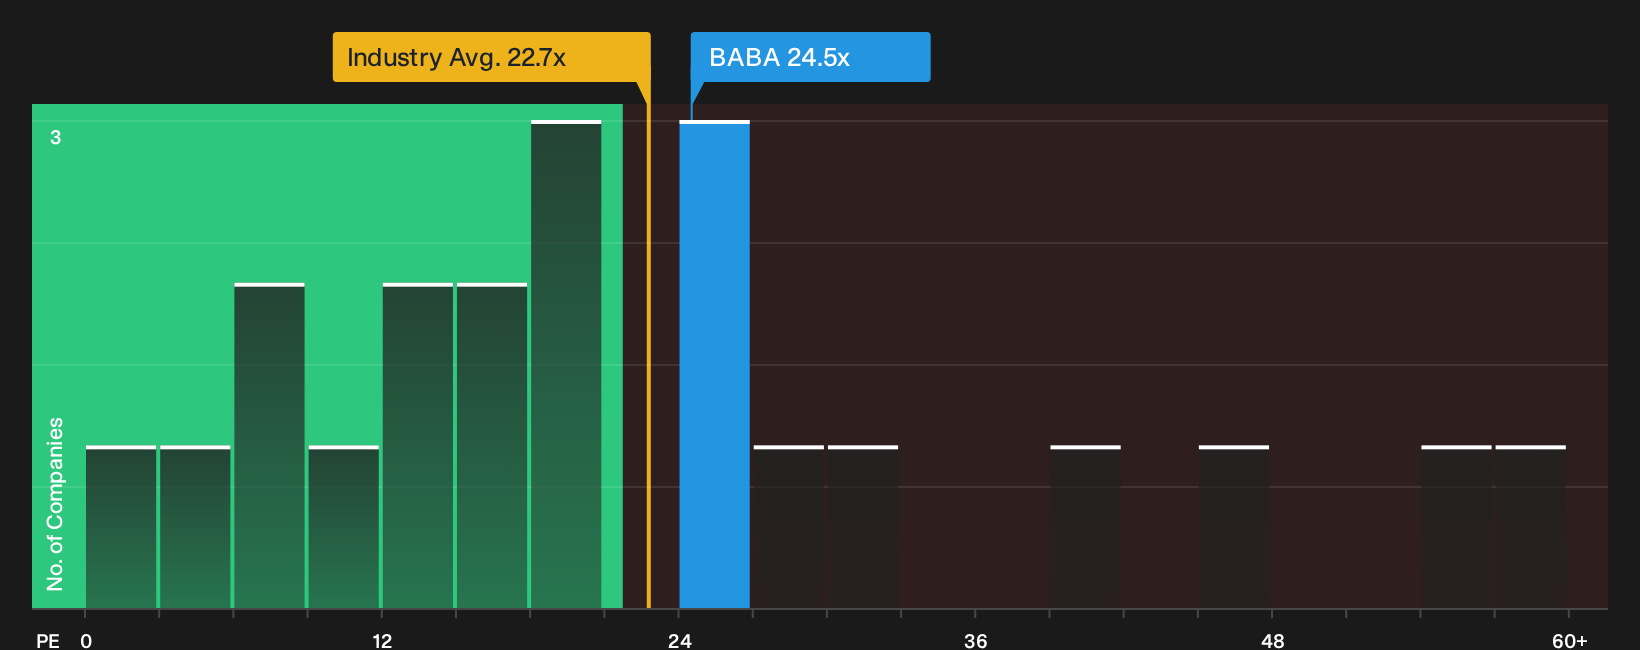
The narrative pegs Alibaba Group Holding as deeply undervalued, yet the market is pricing the shares at a P/E of 24.5x. That is above both peers at 23.2x and the North American Multiline Retail average at 22.7x, while still below a fair ratio of 38.4x.
So investors are looking at a business that screens expensive against current peers but discounted against a fair ratio the market could eventually lean toward. The key consideration is whether earnings quality and future growth justify paying a richer multiple today, or whether this gap simply reflects additional valuation risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the current mood around Alibaba Group Holding is too optimistic or too cautious? Act quickly, review the underlying data for yourself, and weigh both sides of the debate by starting with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Alibaba Group Holding?
If you only stop at Alibaba Group Holding, you risk missing other opportunities that match your style, your risk comfort, and the outcomes you care about most.
- Target resilience by scanning a curated 32 resilient stocks with low risk scores that aims to limit surprises when markets turn choppy.
- Hunt for mispriced quality through a focused 21 high quality undiscovered gems that highlights companies with strong fundamentals yet limited attention.
- Prioritise balance sheet strength with a list of solid balance sheet and fundamentals (24 results) that filters for businesses backed by sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com