


EN
TJX Companies Stock: Is Wall Street Bullish or Bearish?
Valued at a market cap of $159.2 billion, The TJX Companies, Inc. (TJX) is a leading global off-price retailer of apparel, footwear, accessories, and home fashions, headquartered in Framingham, Massachusetts. The company operates more than 5,200 stores across 10 countries through well-known retail chains, including TJ Maxx, Marshalls, HomeGoods, Homesense, Sierra, Winners, and TK Maxx.
TJX Companies shares have plunged 3.6% over the past 52 weeks and 9.8% over the past six months. In contrast, the S&P 500 Index ($SPX) has climbed 8.2% over the past year and 7.4% over the past six months.
Narrowing the focus, the State Street SPDR S&P Retail ETF (XRT) has gained about 12.2% over the past year and 6.8 in 2026, outperforming the stock.
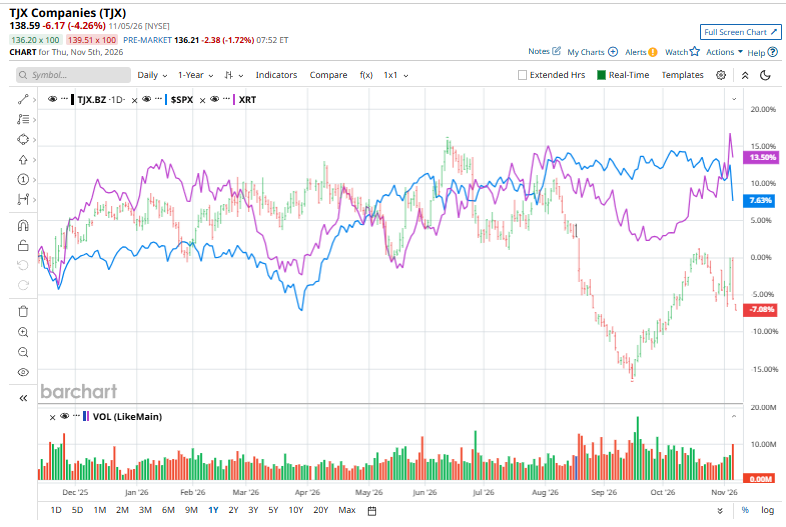
The TJX Companies has lagged the broader market over the past year as investor concerns about slowing comparable-sales growth, merchandising execution challenges and intensifying competition have weighed on its valuation. The biggest setback came from its Marmaxx division, which includes TJ Maxx and Marshalls and accounts for more than 60% of company sales.
Meanwhile, growing price sensitivity among consumers and stronger competition from traditional retailers have raised concerns about TJX's ability to sustain its market-share gains. Higher wage and freight costs have also pressured margins, while cautious near-term earnings guidance and analyst downgrades added to investor uncertainty.
For fiscal 2027, ending in January, analysts expect TJX to deliver EPS of $5.22, up 10.4% year over year. Moreover, the company has a robust earnings surprise history. It has surpassed the Street’s bottom-line estimates in each of the past four quarters.
Among the 24 analysts covering the TJX stock, the consensus rating is a “Strong Buy.” That’s based on 17 “Strong Buys,” one “Moderate Buy,” and six “Holds.”
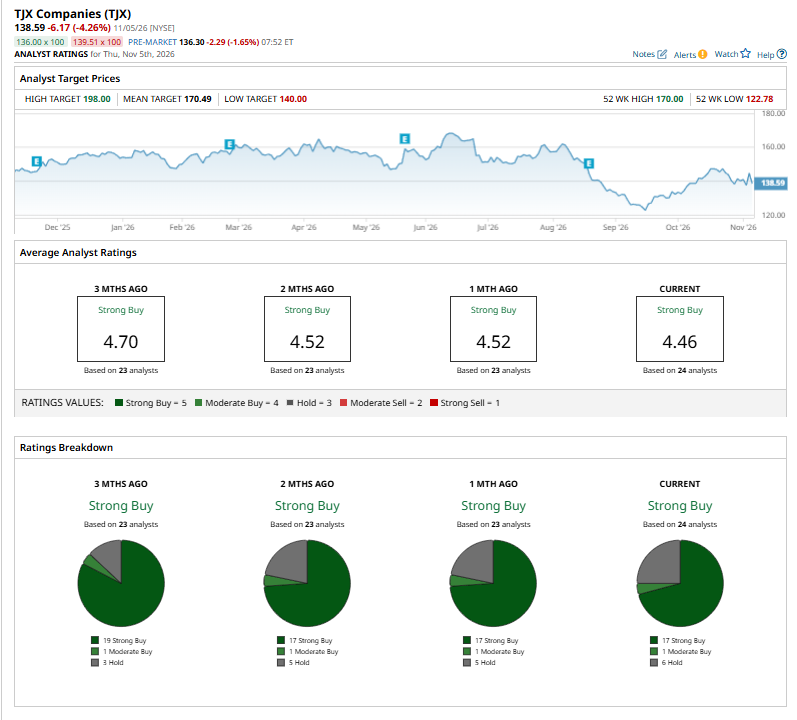
This configuration is more bearish than three months ago, when 19 analysts gave “Strong Buy” recommendations.
Earlier in August, Jefferies downgraded TJX Companies to “Hold” from “Buy” and set a $145 price target, citing a more pronounced slowdown at its Marmaxx division than a typical merchandising setback. Analyst Corey Tarlowe highlighted that Marmaxx comparable sales growth decelerated to 1% from 6%, marking its weakest performance since fiscal 2018, excluding the pandemic.
TJX’s mean price target of $170.49 suggests a 23% upside potential.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.