


EN
Do Wall Street Analysts Like ConocoPhillips Stock?
Houston, Texas-based ConocoPhillips (COP) is a leading independent exploration and production (E&P) company. With a market cap of $164.5 billion, the company explores for, produces, transports, and markets crude oil, natural gas, natural gas liquids (NGLs), bitumen, and liquefied natural gas (LNG) across 15 countries
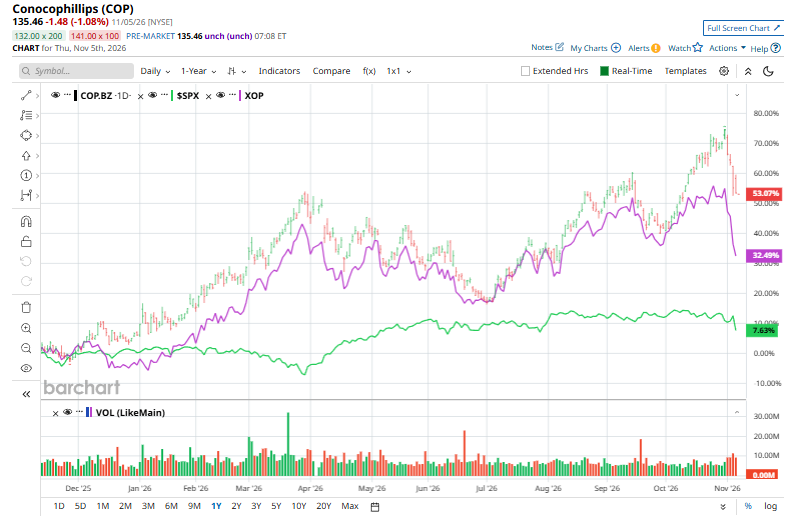
Shares of this oil giant have outperformed the broader market over the past year. COP has gained 55.7% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 8.4%. In 2026, COP stock is up 45.8%, surpassing the SPX’s 7.6% rise on a YTD basis.
COP has also surpassed the State Street SPDR S&P Oil & Gas Exploration & Production ETF (XOP). The exchange-traded fund has gained about 40.7% over the past year and 39% on a YTD basis.
ConocoPhillips delivered strong Q3 2026 earnings on Nov. 5, with higher commodity prices driving substantial earnings growth, stronger operating cash flow, and increased shareholder distributions. Revenue rose 29.3% year over year to $19.44 billion, while adjusted earnings climbed 95.2% to $3.92 billion, and adjusted EPS advanced 103.1% to $3.27. However, total production declined 4% to 2.30 million barrels of oil equivalent per day (BOE), while average realized prices increased 32.2% to $61.40 per BOE, highlighting the significant contribution of higher commodity prices to the company's earnings growth.
ConocoPhillips repurchased approximately $2.4 billion of shares during the quarter and raised its quarterly base dividend by 11% to $0.93 per share. Management also reaffirmed its commitment to returning 45% of cash flow from operations to shareholders and projected low-single-digit production growth in 2027 with lower capital expenditures.
For the current fiscal year, ending in December, analysts expect COP’s EPS to grow 91.2% to $11.78 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in three of the last four quarters while missing the forecast on another occasion.
Among the 29 analysts covering COP stock, the consensus is a “Moderate Buy.” That’s based on 17 “Strong Buy” ratings, four “Moderate Buys,” and eight “Holds.”
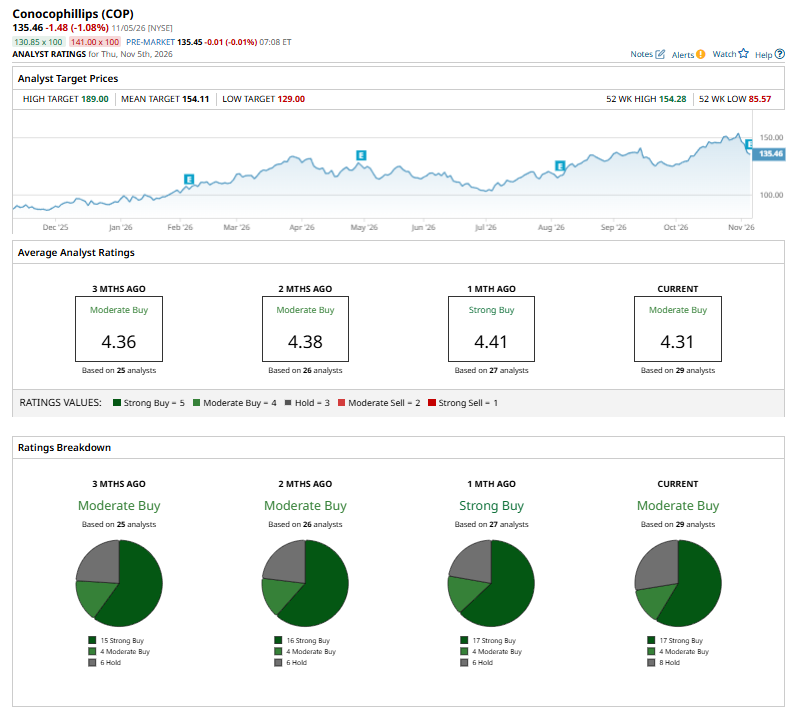
This configuration is bearish than two months ago, with 16 analysts suggesting a “Strong Buy.”
On Nov. 5, Mizuho raised its price target on ConocoPhillips to $149 from $146 while maintaining an “Outperform” rating. The revision followed better-than-expected third-quarter cash flow, which exceeded the firm's and consensus estimates by approximately 4%. Mizuho also highlighted progress on the Willow project, improved Permian efficiency, expanding LNG offtake agreements, and increased shareholder returns.
The mean price target of $154.11 represents a 13.8% premium to COP’s current price levels. The Street-high price target of $189 suggests an ambitious upside potential of 39.5%.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.