


EN
Astellas Pharma Stock In Focus After Earnings Guidance Upgrade
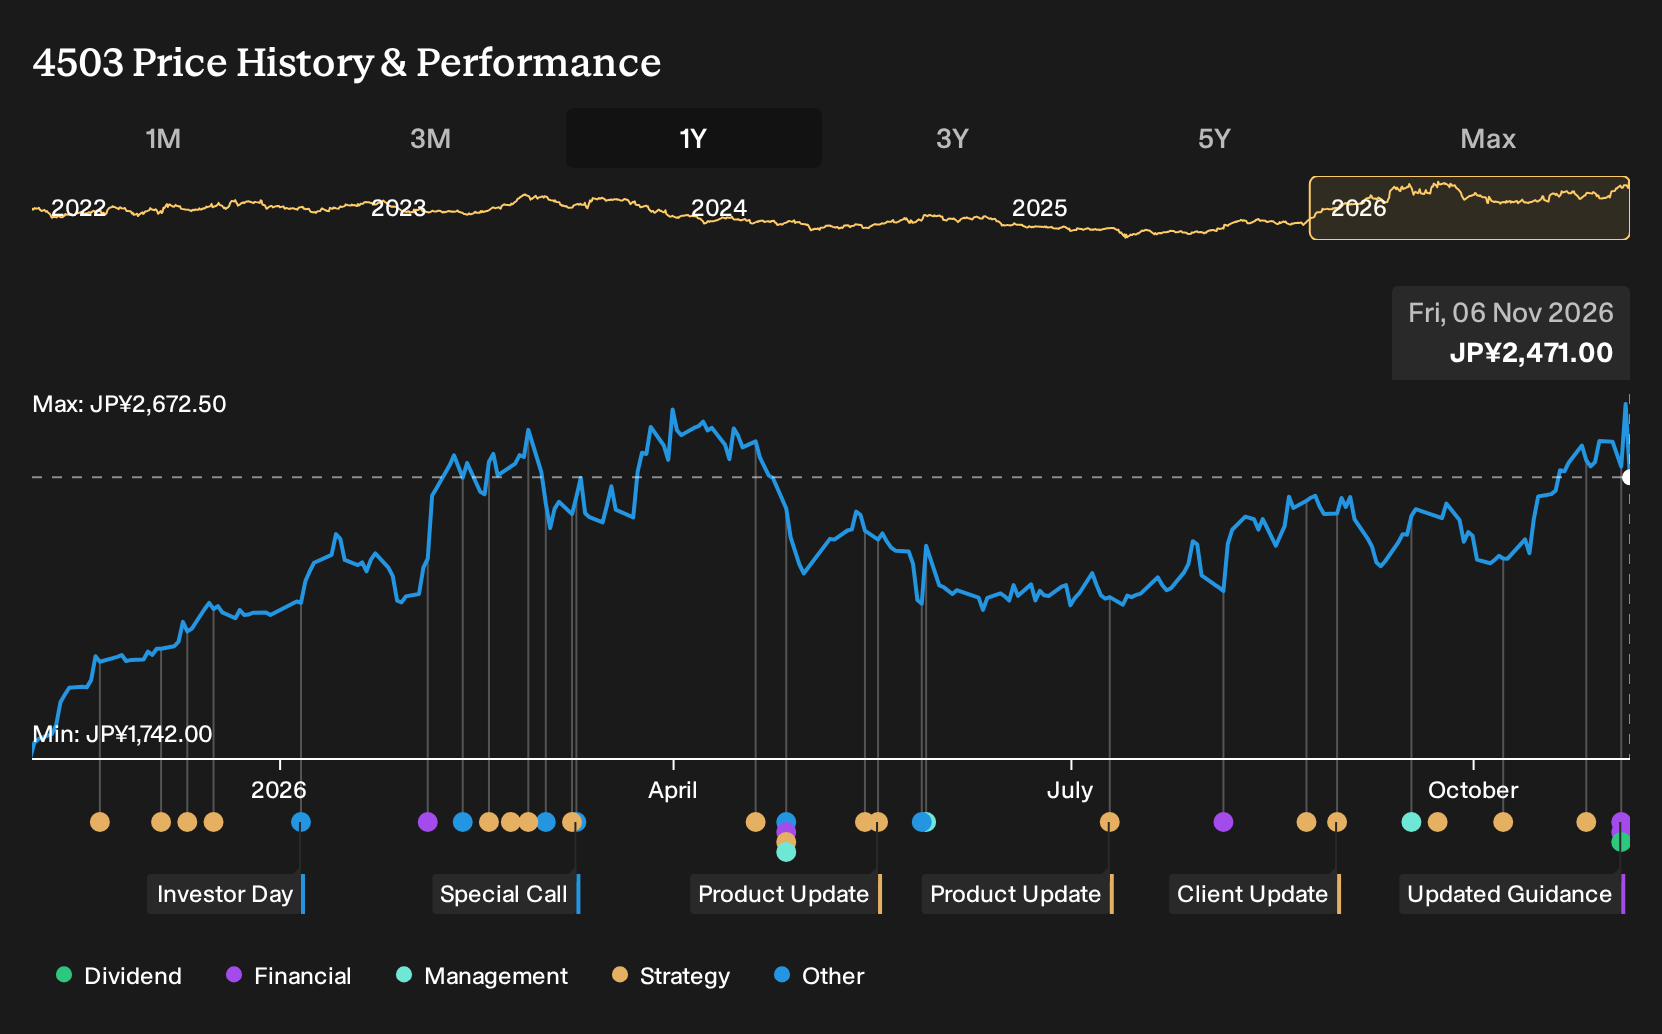
- Astellas Pharma reported half year sales of ¥1,270,861 million and net income of ¥241,677 million, and issued full year guidance that includes expected revenue of ¥2,330,000 million and basic earnings per share of ¥195.22 for the year ending March 31, 2027.
- The board also outlined a dividend plan of ¥40 per share for the current fiscal year, signaling ongoing cash returns while the business invests in pipeline assets such as the DAX-044 immuno oncology option licensed from Audax Biosciences.
- We will now look at how Astellas Pharma's half year earnings and updated guidance could influence its broader investment narrative.
See how Astellas Pharma’s latest earnings, dividend plans and pipeline moves compare to peers by reviewing our hand picked list of 9 healthcare AI stocks
Astellas Pharma Investment Narrative Recap
Astellas Pharma asks you to consider a shift from heavy XTANDI reliance toward a broader mix of oncology, ophthalmology and women’s health drugs, supported by tighter cost control. The half year results, with sales and profit figures in line with the new full year guidance, point to an operating base that currently supports that transition.
The key near term catalyst remains execution on the Sustainable Margin Transformation program, while XTANDI pricing and future generic pressure loom as the biggest risk. The upgraded guidance itself does not remove that risk, but it helps reduce concern that cost savings or newer brands are falling behind management’s own timetable.
The updated outlook to revenue of ¥2,330,000m and profit attributable to owners of ¥350,000m for the year ending March 31, 2027, is the announcement that ties closest to the current story. Those figures give you a clearer yardstick to judge whether Astellas Pharma is keeping earnings resilient as legacy products face policy pressure and eventual competition.
Guided basic EPS of ¥195.22 also matters for how you think about funding pipeline moves such as the DAX-044 option and the regular dividend plan of ¥40 per share. If the business tracks close to these targets, management has somewhat more room to keep investing in oncology assets while still honoring its commitment to steady shareholder returns.
Astellas Pharma Consensus Forecasts In Context
Astellas Pharma's current analyst narrative leans on forecasts that are already baking in softer top line trends and slimmer profitability over the next few years. Analysts expect annual revenue to decline by 4.9% on average, which frames the shift away from XTANDI as a period of adjustment rather than expansion. Profit margins are modeled to ease from 16.0% today to 13.5% in three years, so the bar for the Sustainable Margin Transformation program is not set unrealistically high in consensus numbers.
On earnings, the gap between where Astellas Pharma is today and where analysts think it lands by the end of the decade is clear. Consensus points to earnings of ¥263.7b and earnings per share of ¥154.19 by about 2029, compared with current earnings of ¥364.9b. That is a decline of ¥101.2b in absolute profit, which gives a concrete sense of how much XTANDI pressure and lower margins are already built into expectations.
The same 2029 snapshot also includes forecast revenue of ¥1,953.3b and assumes the stock trades on a P/E of 20.0x at that point, up from 11.3x today and above the current 13.9x P/E for the wider JP Pharmaceuticals industry. That higher multiple is what has to do the heavy lifting if earnings are moving lower, because it relies on investors paying more for each yen of profit in return for a more diversified product mix and a de-risked pipeline. The valuation framework uses a 5.0% discount rate and modest share count growth of 0.1% per year, which are relatively standard assumptions but still worth stress testing against individual hurdle rates.
Astellas Pharma's narrative projects ¥1,953.3b revenue and ¥263.7b earnings by 2029. This lines up with an assumed 4.9% yearly revenue decline and a ¥101.2b earnings decrease from ¥364.9b today.
Discover how Astellas Pharma's fair value reflects a valuation gap consistent with its current price.
Exploring Other Perspectives
For a sharper contrast, look at the most bearish view on Astellas Pharma. Those analysts were pencilling in revenue of about ¥1,719.7b and earnings near ¥187.2b by 2029, with margins easing faster than consensus. That skews much more pessimistic. The latest earnings and guidance could shift that debate. Explore both narratives before deciding what makes sense for you.
Explore 2 other Astellas Pharma fair value estimates, including one that suggests it could be worth just ¥2529.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Astellas Pharma research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Astellas Pharma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Astellas Pharma's overall financial health at a glance.
Looking For More Investment Ideas Beyond Astellas Pharma?
If Astellas Pharma has sharpened your focus on how forecasts, balance sheets and dividends fit together, use that same checklist across a wider list of companies. The Simply Wall St Screener can help you quickly narrow the universe to businesses that better match your risk tolerance, income needs, or valuation preferences.
- If you care most about price and quality, start with companies that combine strong fundamentals with room for a potential re rating through our 29 high quality undervalued stocks.
- If resilience matters more than headline growth, look for businesses with sturdier finances and lower risk scores using the 21 resilient stocks with low risk scores.
- If you want balance sheets that can better absorb bumps in the cycle, filter for companies with healthier leverage and liquidity through this list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com