


EN
Bausch + Lomb (BLCO) Stock Could Be Cheap After Its 28% Gain
Bausch + Lomb has delivered a 28.3% gain over the past year, while its latest results and guidance have refocused attention on how much investors are actually paying for its cash flows. With the stock recently closing at US$19.92, the key issue is whether that share price lines up with what the business can generate in future cash.
- The 28.3% one year return puts more weight on the question of whether recent buyers are paying a price that its cash flow profile can reasonably support.
- Fresh earnings news, including a swing to profit and revenue ahead of prior expectations, may support a view that Bausch + Lomb can grow cash generation over time and improve the visibility of those cash flows.
- What if you looked at Bausch + Lomb through its sales instead? See what Bausch + Lomb's 1.3x P/S says about the price.
The issue now is whether the current market value of Bausch + Lomb is justified by what a Discounted Cash Flow (DCF) view of its cash flows suggests the shares are worth.
If you want to pressure test Bausch + Lomb's cash flow valuation against a wider field, compare it with companies in the 42 high quality undervalued stocks
Is Bausch + Lomb a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) approach here uses a 2 Stage Free Cash Flow to Equity model built on Bausch + Lomb's cash generation. Latest twelve month free cash flow sits at about $212.6 million, and the projections assume this cash pool grows over time rather than shrinks, with higher levels expected by the end of the decade.
Those rising cash flow estimates, when discounted back, point to an intrinsic worth that the model suggests is substantially above the current share price of $19.92. The recent Q3 update, which included a move back to net profit and full year revenue guidance of $5.45 billion to $5.55 billion, helps explain why the cash flow outlook used in the model leans toward ongoing growth rather than contraction. That gap between what the DCF implies and where the stock trades is what the valuation link below is designed to quantify in more detail. Find out what Bausch + Lomb could be worth using our Discounted Cash Flow (DCF) estimate.
The Bausch + Lomb Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St act as the missing link between Bausch + Lomb's DCF puzzle above and the assumptions that would need to hold on growth, margins and earnings for the share price to move meaningfully away from where it is today, and they sit on the stock's Community page. Each scenario ties a specific fair value to a clear storyline about Bausch + Lomb's possible catalysts and risks so you can track over time which version appears to be unfolding.
Community views on Bausch + Lomb are split between a moderate upside case and a more cautious read on how much is already reflected in the price.
Bull case: 6% undervalued
"Rising global prevalence of dry eye and greater diagnosis in both primary care and specialist settings support sustained prescription growth for Miebo, Xiidra and future combination therapies…"
Discover why this Narrative puts Bausch + Lomb at 6% undervalued.
Bear case: 25% overvalued
"Bearish analysts expect Bausch + Lomb to struggle to generate attractive returns on new eye care investments, given historically low ROIC, earlier EPS and free cash flow margin pressure…"
Explore why this Narrative puts Bausch + Lomb at 25% overvalued.
One more Bausch + Lomb check that could change how you read the story
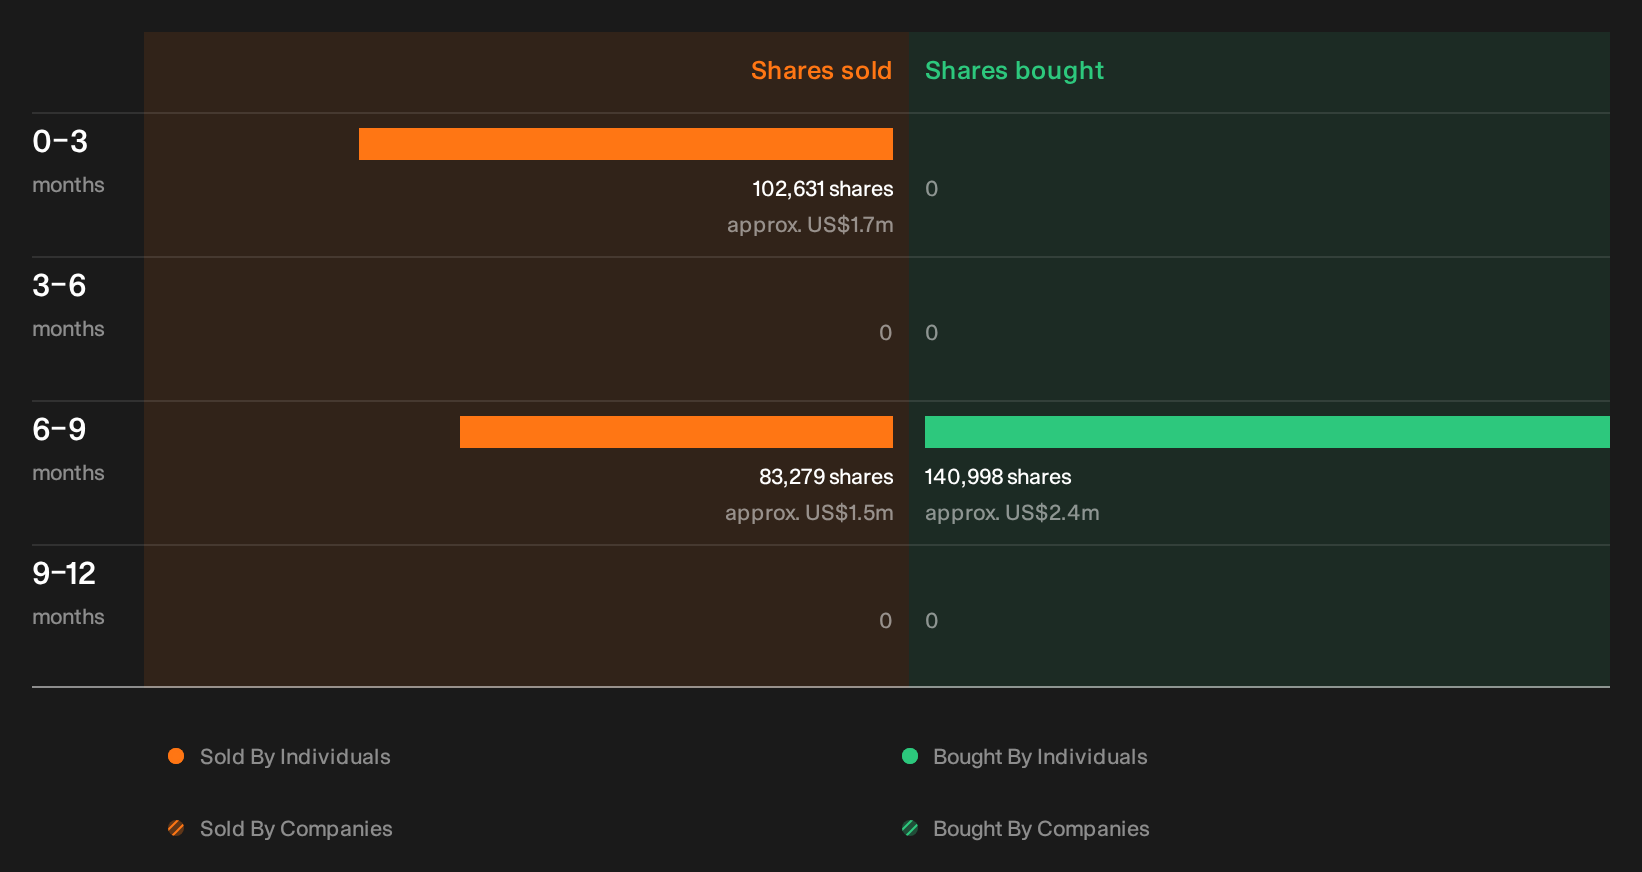
Price and cash flows tell only part of the picture, because recent insider transactions have also been flagged by our checks and the who, how much and what it might signal are still for you to unpack. See the recent insider selling flagged for Bausch + Lomb.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com