


EN
Fastly (FSLY) Stock May Trade Near Fair Value Despite AI Expansion
Fastly has seen its share price swing sharply in recent years, and after the latest moves investors are asking whether the current market value lines up with what its cash flows can reasonably support. With fresh headlines around new partnerships and an expanded AI offering, the question now is how much of that story is already embedded in the price.
- The stock has fallen about 69.6% over the past 5 years, which puts the focus squarely on whether the underlying cash generation can justify where the market is willing to value Fastly today.
- Recent record revenue and stronger operating cash flow suggest the business may be in a better position to turn growth initiatives, including its AI portfolio and partnerships, into more durable cash inflows.
- Prefer to judge Fastly on sales? See why Fastly's 3.4x P/S tells a different valuation story.
For investors, the debate is whether Fastly's current share price is supported by its cash flows when measured against an intrinsic value estimate based on a Discounted Cash Flow (DCF) approach.
If you are comparing Fastly with other AI infrastructure companies that face similar cash flow considerations, it may be helpful to evaluate it alongside 53 AI infrastructure stocks.
Does Fastly Look Fairly Valued on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash that Fastly can return to shareholders over time. Latest twelve month Free Cash Flow sits at about $65.2 million, and the projections used in the model point to growing Free Cash Flow over the coming decade rather than a shrinking stream.
Those higher forecast cash flows, once discounted back, put the estimated intrinsic worth broadly in line with the current share price of $15.38. Because Fastly recently reported record Q3 2026 revenue and stronger operating cash flow, the market seems to be treating that AI expansion story as largely reflected in today’s valuation rather than as untapped upside. Find out what Fastly could be worth using our Discounted Cash Flow (DCF) estimate.
The Fastly Narrative: What Would Justify Today's Price?
Fastly's Simply Wall St Narratives pick up where the DCF debate leaves off and spell out which combinations of growth, margins and earnings paths would need to play out for the stock to be worth materially more or less than today’s price, based on community views on the company’s future. Rather than a single multiple or model figure, each narrative lays out the key levers behind its fair value so you can compare those assumptions with actual results as they are reported.
Bulls and bears on Fastly are reading the same AI and edge story, yet they draw very different conclusions about what is already in the price.
Bull case: 46% undervalued
"Ongoing adoption of advanced security solutions including next-generation WAF, DDoS and bot mitigation remains a live driver and is now reinforced by Fastly being named a Leader in a 2026 web application and API protection assessment…"
Discover why this Narrative puts Fastly at 46% undervalued.
Bear case: 209% overvalued
"FSLY is one of those companies, offering Edge Computing services (processing data in localised servers rather than sending it to a central location)…"
Explore why this Narrative puts Fastly at 209% overvalued.
One more Fastly check that sits outside the cash flow story
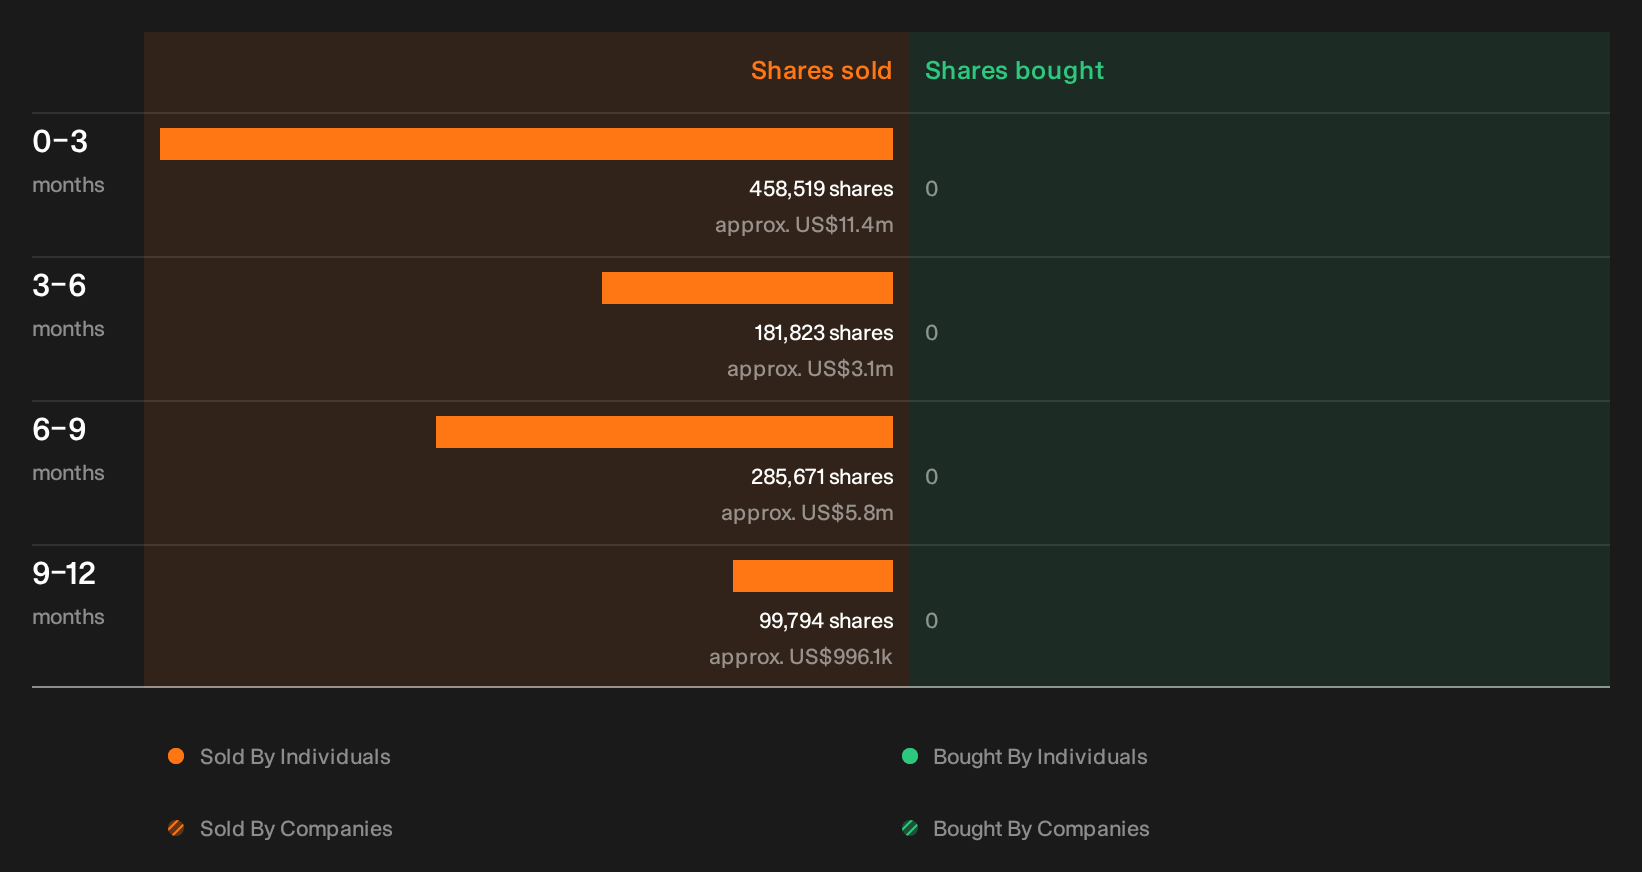
Price and projections only tell part of the Fastly picture, because recent trades by people inside the business have also been flagged by our checks, and the specific sellers, sizes and context are there for you to review. See the recent insider selling flagged for Fastly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com