


EN
Is Terreno Realty (TRNO) Fairly Valued After Soft FFO And A New Buyback?
Terreno Realty (TRNO) just delivered a mixed quarterly update that paired softer funds from operations with stronger revenue, a fresh share repurchase authorization and a reaffirmed cash dividend of $0.57 per share.
Terreno Realty’s share price has risen 13.67% year to date to US$67.09, with a 1 year total shareholder return of 17.64% pointing to improving sentiment, despite a 90 day share price return that slipped 2.43% after softer earnings, as investors weigh recent acquisitions, the fresh buyback authorization and the reaffirmed dividend together.
Scan industrial-focused REIT peers reacting to similar earnings and dividend stories by focusing on our curated list of list of solid balance sheet and fundamentals (24 results)
Terreno Realty now trades only slightly below both analyst targets and an intrinsic value estimate, after a strong year-to-date move. Is that small discount a margin of safety, or a warning that the market’s caution is warranted?
Price-to-Earnings of 21.1x: Is it justified?
Terreno Realty now trades on a P/E of 21.1x, which the data flags as good value versus some peers but expensive versus the broader industrial REIT group. As a result, the current $67.09 share price sits in a tight valuation band rather than at an obvious bargain or premium.
The P/E ratio compares what investors pay for each dollar of Terreno Realty’s earnings. This matters a lot for a real estate trust that investors often assess on earnings stability and dividend support. A lower multiple can hint that the market is cautious about future profit trends, while a higher one can suggest investors are comfortable paying up for perceived quality or income.
Relative to similar companies where the peer average multiple is 27.8x, Terreno Realty’s 21.1x P/E is flagged as good value. The estimated fair P/E of 27.8x points to a level the market could move towards if sentiment on its earnings stream and dividend holds up. That said, compared with the wider Global Industrial REITs industry at 15.5x, the stock trades at a clear premium, which implies investors currently accept a higher price for each dollar of earnings than they do for many industrial REIT alternatives.
Explore the SWS fair ratio for Terreno Realty.
Result: Price-to-Earnings of 21.1x (ABOUT RIGHT)
Still, Terreno Realty’s annual revenue growth, combined with declining net income and a modest intrinsic discount, leaves little cushion if leasing momentum or capital costs disappoint.
Find out about the key risks to this Terreno Realty narrative.
Another View on Terreno Realty’s Value
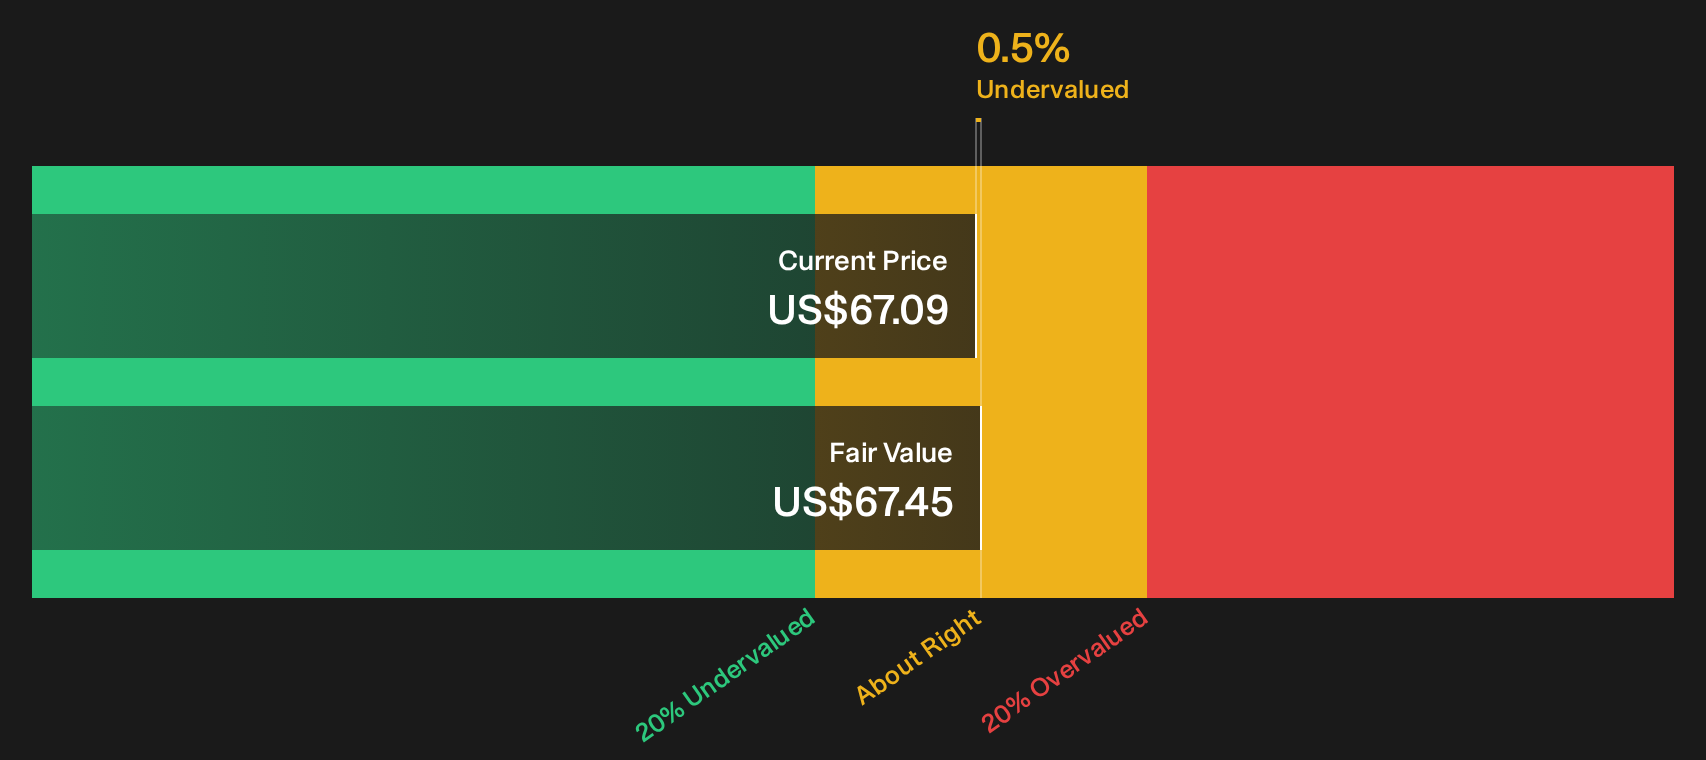
A second lens comes from the SWS DCF model, which estimates Terreno Realty’s future cash flow value at $67.45, slightly above the current $67.09 price. That 0.5% discount is tiny. Is this a narrow mispricing or simply a sign the market already has Terreno Realty priced appropriately?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Terreno Realty for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around valuation and fundamentals can feel confusing, so move quickly from headlines to hard numbers and make your own call. To weigh both sides properly, take a close look at the 3 key rewards and 3 important warning signs.
Looking for more Terreno Realty sized opportunities?
If Terreno Realty has you thinking harder about value and income, do not stop at one ticker. Broader ideas often reveal better fits for your goals.
- Target potential mispricing by scanning a focused set of companies that screen as attractively valued using the 42 high quality undervalued stocks.
- Prioritize steadier sleep at night and filter for businesses that clear a higher bar on financial resilience with the 32 resilient stocks with low risk scores.
- Aim for reliable income streams and sort through companies offering stronger yields and consistency through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com