


EN
How Investors May Respond To Centrus Energy (LEU) Earnings Beat
- Centrus Energy reported Q3 2026 revenue of US$55.5 million with net income of US$31.6 million, while also shipping its first new centrifuge from Oak Ridge as part of a multibillion dollar uranium enrichment expansion.
- The company combined a strong earnings surprise with tangible execution on its fully domestic enrichment and supply chain buildout, including the Westerman acquisition and the first production centrifuge shipment to Ohio.
- Next, the focus is on how Centrus Energy's investment narrative evolves as strong earnings intersect with visible progress on its enrichment capacity expansion.
Scan how Centrus Energy’s enrichment push compares with other nuclear-focused plays by reviewing the hand-picked 16 nuclear energy infrastructure stocks shaping the next phase of uranium infrastructure.
What Is Centrus Energy's Investment Narrative?
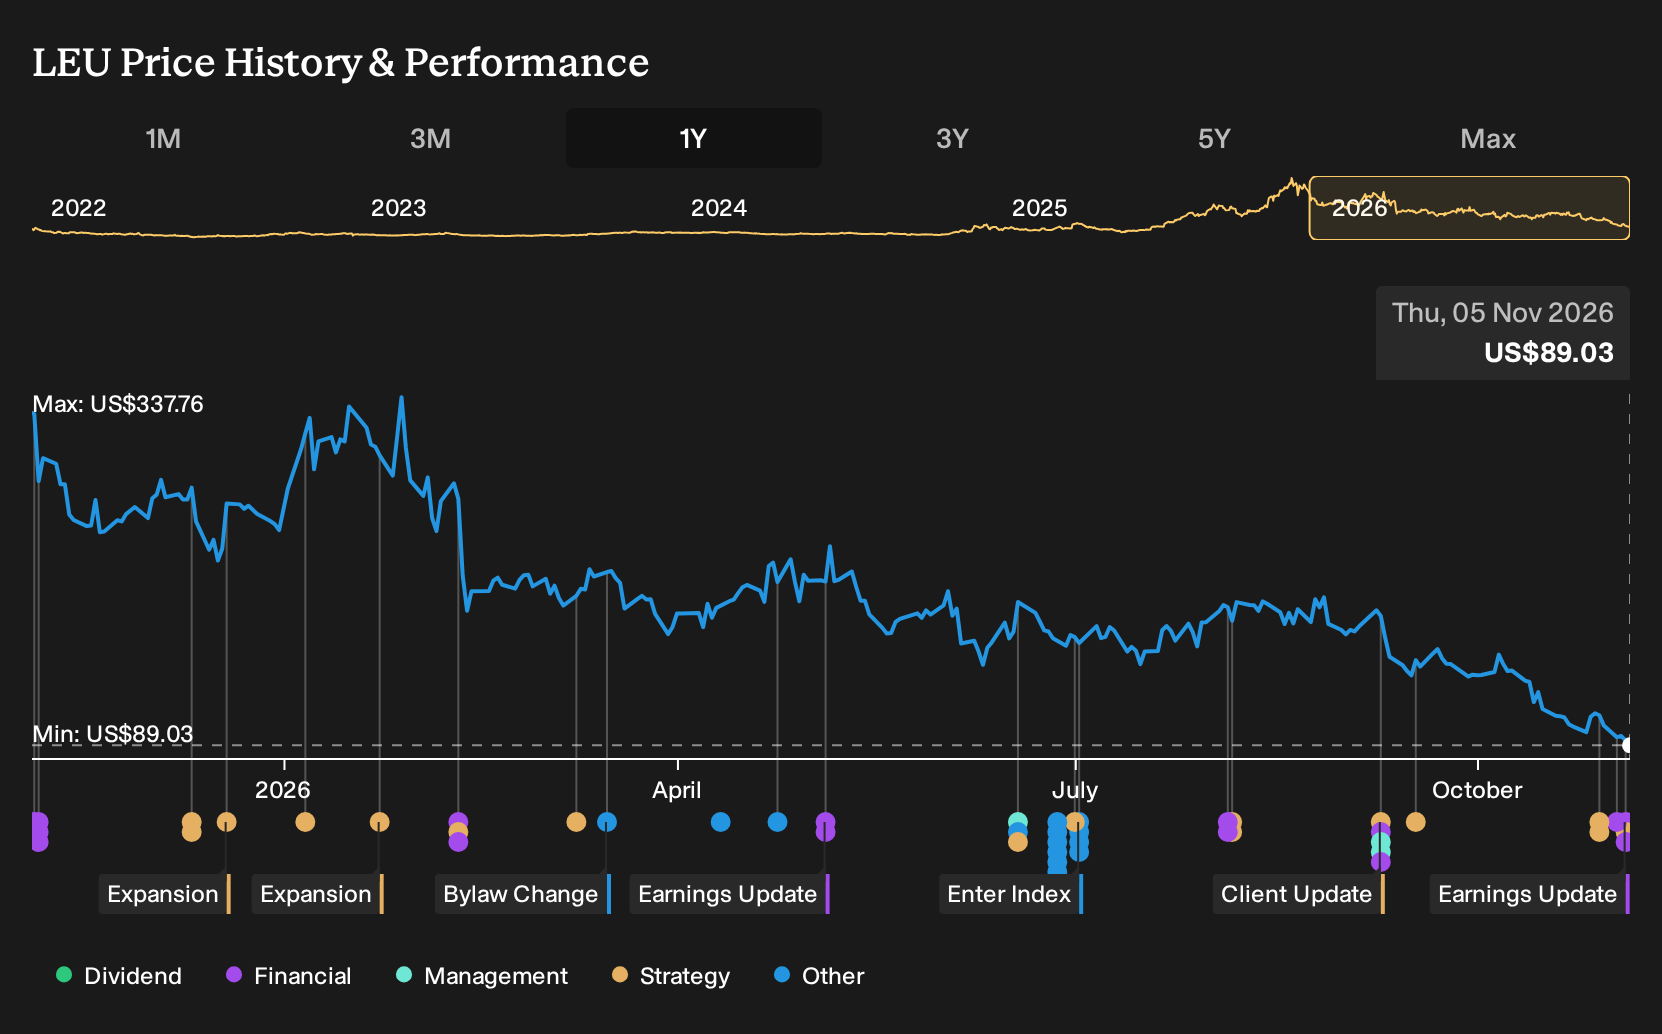
Centrus Energy is a bet on uranium enrichment capacity turning into durable cash flow, not just a short squeeze on headlines. To stay comfortable as a shareholder, you need to believe the multibillion dollar centrifuge buildout and HALEU positioning eventually justify heavy capital needs and a premium P/E. The latest quarter showed Q3 revenue of US$55.5 million but a much higher net income of US$31.6 million, alongside a US$5.4b enrichment backlog, which keeps the commercial story very real even as the share price has fallen sharply over the past year.
The recent move to deploy US$350 million to US$500 million of capital, hire hundreds of employees, ship the first new centrifuge ahead of schedule and file a US$17.1 million shelf registration all point in the same direction. Centrus Energy is leaning into a capital intensive plan just as profit margins are lower than last year and earnings are forecast to decline slightly over the next three years. In the short term, the key swing factors are execution on Oak Ridge and Piketon, contract timing and funding costs rather than analyst targets or sentiment.
That said, before treating this enrichment buildout as a straightforward upside story, there is one pressure point that keeps coming up in the numbers...
There's only one way to know the right time to buy, sell or hold Centrus Energy. Head to Simply Wall St's company report for the latest analysis of Centrus Energy's Fair Value.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Centrus Energy’s HALEU contracts as a potential catalyst, with prior models penciling in revenue reaching about US$677.3 million and earnings of roughly US$107.7 million by around 2029. That is a far more aggressive story than consensus and could shift again after this latest earnings and centrifuge news.
Explore 5 other Centrus Energy fair value estimates, including one that suggests as much as 585% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Centrus Energy research is our analysis highlighting 3 important warning signs that could impact your investment decision.
- See our latest analysis for Centrus Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Centrus Energy's overall financial health at a glance.
Looking For More Ideas Beyond Centrus Energy?
If this Centrus Energy story has sharpened your thinking about risk, balance sheets and future contracts, use that same lens across a broader watchlist. The Simply Wall St Screener can help you quickly surface other businesses that line up with the kind of profile you want to research next.
- If capital preservation comes first for you, focus on companies with sturdier finances by starting with a 32 resilient stocks with low risk scores that have historically shown more resilient characteristics.
- If you want a mix of quality and potential mispricing, look through a curated 21 high quality undiscovered gems that might not yet be widely followed.
- If balance sheet strength is your anchor, filter for robust fundamentals using a list of solid balance sheet and fundamentals (24 results) that can help support your long-term thesis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com