


EN
Learn Why The Bull Case For Northwest Natural Holding (NWN) Could Change Following Nine Month Profit Growth
- Northwest Natural Holding reported third quarter 2026 sales of US$177.97 million and a net loss of US$29.84 million, with nine month sales of US$911.93 million and net income of US$68.25 million.
- The shift from a quarterly loss to higher nine month earnings, along with improved diluted results per share, highlights how seasonality and longer period performance both shape Northwest Natural Holding’s operating picture.
- We will look at how Northwest Natural Holding’s investment narrative aligns with nine month earnings strength and a relatively unchanged quarterly loss.
Compare Northwest Natural Holding’s latest earnings swing against a curated 6 dividend fortresses that pairs income potential with more resilient results across different parts of the market.
Northwest Natural Holding Investment Narrative Recap
To own Northwest Natural Holding, you need to be comfortable with a regulated utility that leans on long duration projects, Texas meter growth and water expansion, while its core Pacific Northwest gas territories face decarbonization and electrification risk. The latest results fit that story. Nine month net income of US$68.25 million and earnings per share of US$1.62 show the plan working over a longer stretch despite a seasonal third quarter loss.
In the near term, the key swing factor is still execution on rate frameworks and cost control, because higher operating, depreciation and interest expenses have already pressured coverage of interest and free cash flow against dividends. The third quarter loss of US$29.84 million looks broadly consistent with last year, so it does not radically change either the main earnings catalyst or the biggest risk around ongoing cost inflation and policy pressure on gas usage.
The most relevant datapoint for this earnings release is the step up in nine month profitability. Sales of US$911.93 million and net income of US$68.25 million, compared with last year’s nine month figures, line up with the earlier narrative that analysts expect steady progress from SiEnergy’s Texas backlog, the MX3 storage project and water platform growth, all within a regulated framework that targets smoother earnings.
This improvement in year to date diluted earnings per share to US$1.62 from US$1.36 also connects directly to the catalyst list around expanding multiyear rate mechanisms in Washington, Oregon, Texas and Arizona, and the ongoing broadening of the water and wastewater footprint. For you as a shareholder, the question is whether that execution is enough to offset the listed risks, including weaker interest coverage, rising expenses and long term headwinds from electrification and efficiency policies.
Northwest Natural Holding's narrative projects US$1.6 billion in revenue and US$162.2 million in earnings by 2029. This projection is based on an assumed 6.6% yearly revenue growth and an earnings increase of about US$36.2 million from current earnings of US$126.0 million.
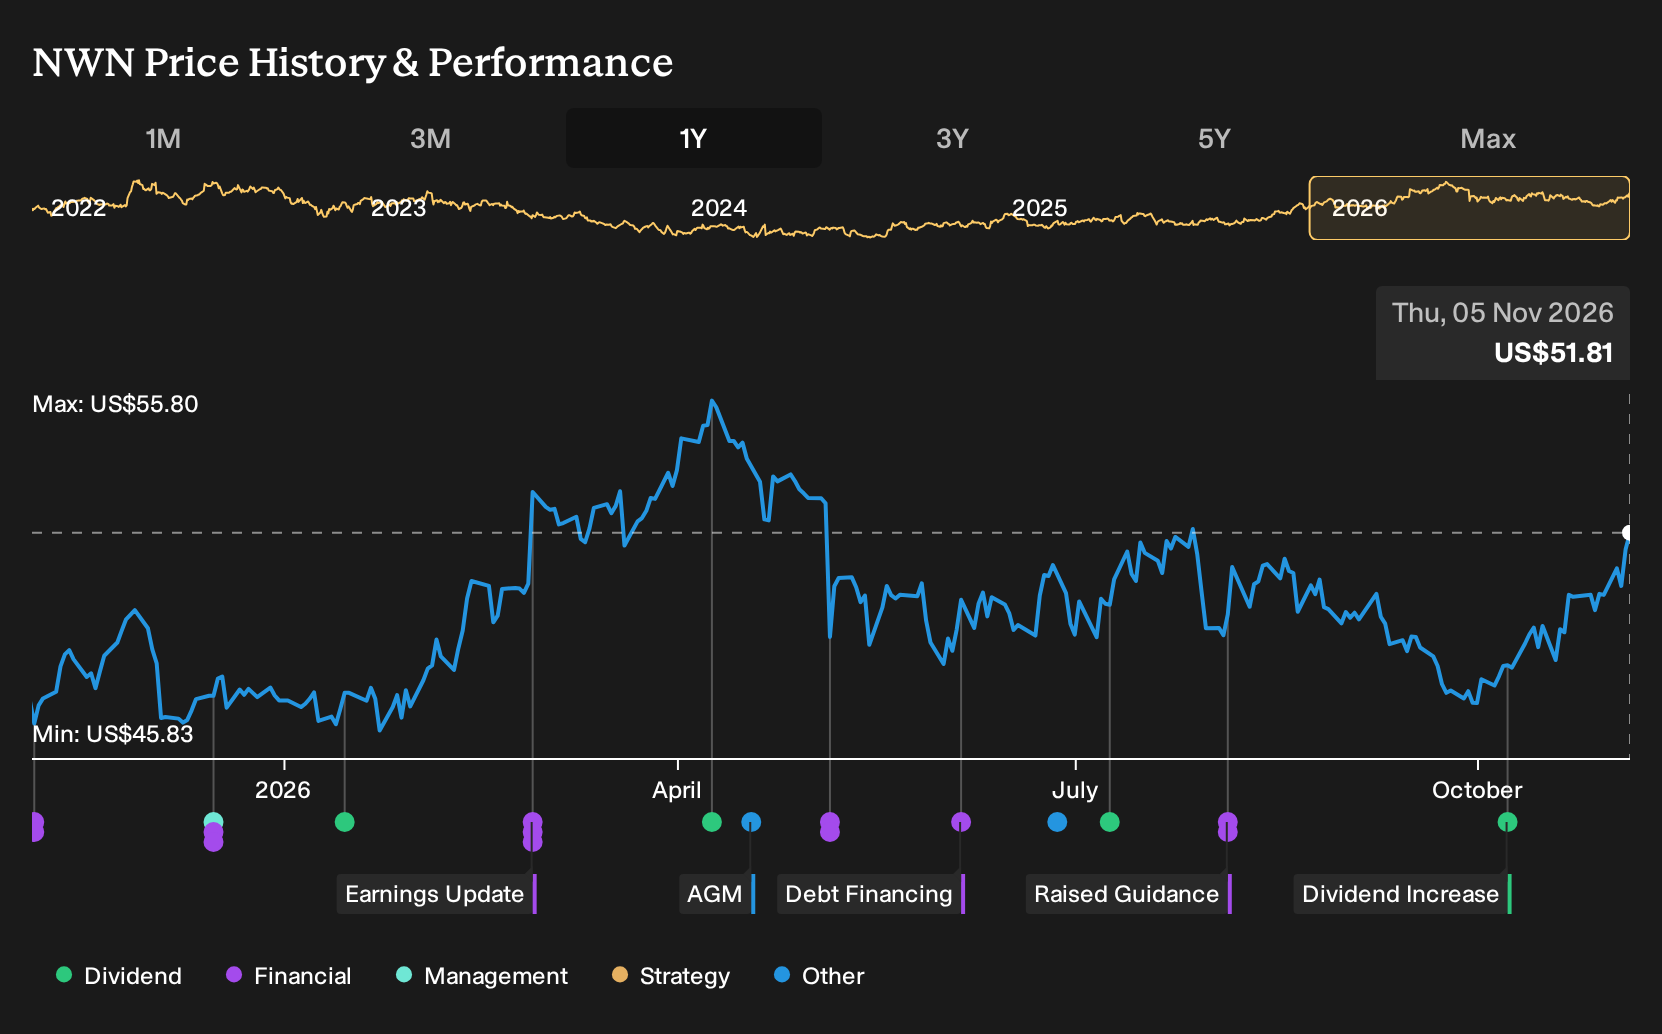
Uncover why Northwest Natural Holding's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$37.86 and US$57.40, which shows how far apart private views on Northwest Natural Holding can sit. When these opinions are considered alongside risks from electrification, higher costs and equity issuance, they reveal a wide spectrum of possible outcomes worth exploring.
Explore 2 other Northwest Natural Holding fair value estimates, including one that suggests up to 11% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Northwest Natural Holding research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Northwest Natural Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northwest Natural Holding's overall financial health at a glance.
Looking for more Northwest Natural Holding sized ideas?
If Northwest Natural Holding has you thinking about income, risk and balance sheet strength, it can help to line it up against other options that share similar traits. The Simply Wall St Screener lets you scan for stocks that match your own preferences on quality, resilience and payout profile in a structured, repeatable way.
- If capital protection is high on your list, sort the market by resilience and financial risk, then narrow in on a 32 resilient stocks with low risk scores that keep downside pressure in focus.
- If you care most about getting paid while you wait, compare Northwest Natural Holding’s income profile against a curated set of 6 dividend fortresses that prioritise yield along with business durability.
- If balance sheet strength matters more than headline growth, filter for companies with cleaner finances and cash support using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com