


EN
Earnings Miss Could Be A Game Changer For NorthWestern Energy Group Stock
- NorthWestern Energy Group reported third quarter 2026 revenue of US$423.8 million with net income of US$30.7 million, while reaffirming full year earnings guidance and maintaining its quarterly dividend at US$0.67 per share.
- The earnings shortfall largely reflected higher costs tied to additional ownership in Colstrip Units 3 and 4, highlighting how NorthWestern Energy Group’s generation mix and cost recovery shape current profitability, even as management remains committed to the planned Black Hills merger.
- We will now look at how NorthWestern Energy Group’s earnings miss but reaffirmed guidance could reshape its longer term investment narrative.
NorthWestern Energy Group Investment Narrative Recap
To own NorthWestern Energy Group, you need to be comfortable with a regulated utility that relies heavily on executing its capital plan and on data center load growth, while still carrying meaningful exposure to Colstrip coal costs and weather-driven usage swings. The latest quarter shows higher revenue but softer earnings, so the business story today is more about cost pressure than sales momentum.
The reaffirmed full-year earnings guidance indicates that management still views the near-term path as intact. The pending Black Hills merger and the large load tariff process remain key swing factors. The biggest risk at the moment appears to be operational and regulatory, centered on recovering rising generation and financing costs without eroding margins further.
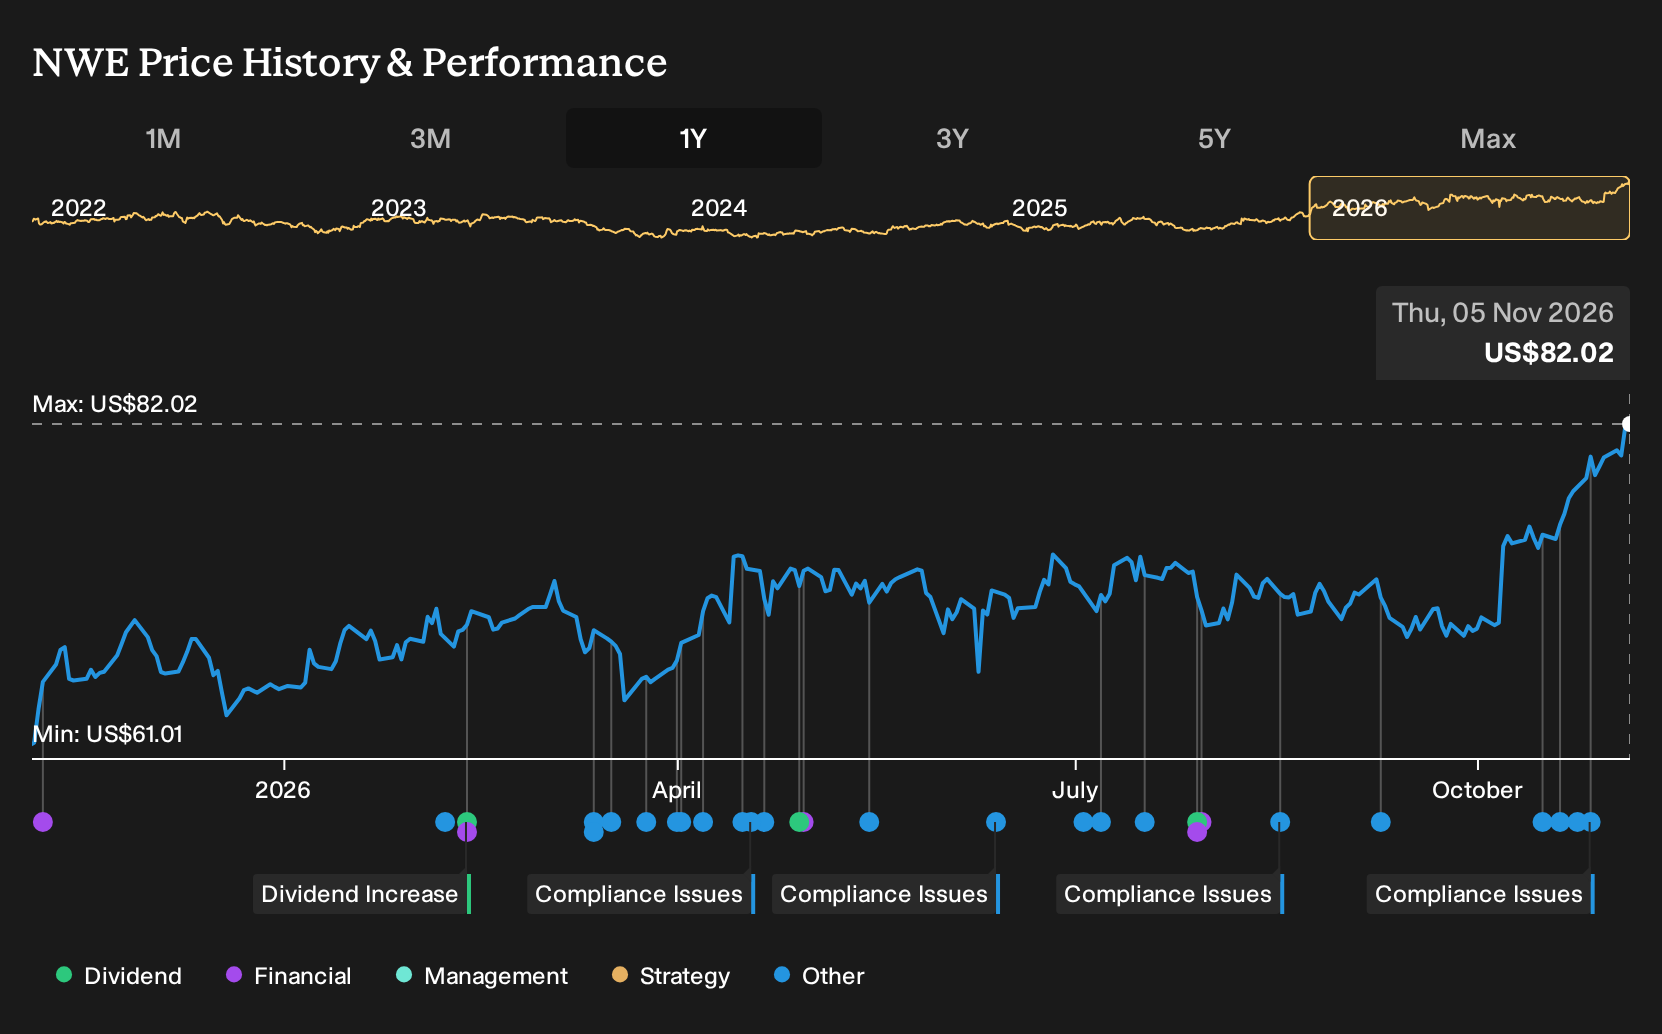
The dividend affirmation at US$0.67 per share for December 2026 is the announcement that may matter most in this context. It signals that NorthWestern Energy Group is maintaining its current capital return rhythm despite year-to-date net income of US$119.2 million coming in lower than the prior year.
For an investor, that dividend decision sits next to two main questions. First, whether earnings pressure from Colstrip ownership, weather, and higher interest costs can be contained within the reaffirmed guidance range. Second, how the prospective Black Hills merger and data-center-driven load growth might, over time, support both bill recovery and the capacity to keep that payout policy in place.
What The Current Forecasts Assume For NorthWestern Energy Group
Analysts are effectively asking you to underwrite a version of NorthWestern Energy Group that looks meaningfully more profitable a few years from now. Their models point to revenue growth of 4.4% a year over the next three years, with profit margins rising from 10.1% today to 13.9% by around 2029. That is a material step up in earnings power for a regulated utility that still has meaningful exposure to coal, weather and rate decisions.
On the earnings line, the consensus view calls for net income to reach US$266.7 million by about 2029, compared with US$171.4 million today. The shift from roughly 10% to almost 14% margins is doing a lot of the heavy lifting in that story, on top of incremental growth in the rate base tied to the capital plan and any Black Hills merger impact. For a reader, that means the current analyst numbers assume a cleaner path on cost recovery for Colstrip, construction execution and financing, with fewer surprises from warm winters or wildfire related expenses.
The valuation overlay is straightforward on paper. In order for the analyst price target to stack up, NorthWestern Energy Group would be generating about US$1.9b of revenue and US$266.7 million of earnings by 2029, and the stock would trade on a P/E of 22.7x on those future earnings, compared with 28.2x today and 21.4x for the broader US integrated utilities peer group. That set of assumptions effectively bakes in both higher profit margins and a still premium earnings multiple, even as the company leans on secured debt and works through regulatory decisions that affect how much of its cost base is actually recovered from customers.
As you weigh those estimates, it helps to separate what is within management’s control from what is not. Execution on the US$3.2b capital plan, progress on the large load tariff and integration of Black Hills are largely internal or regulatory process questions. Weather, wholesale power prices around Colstrip and the broader rate backdrop sit outside that circle. The more dependent your own investment case is on the full 4.4% revenue trajectory and margin lift to 13.9%, the more sensitive it becomes to any disappointment in those external factors.
NorthWestern Energy Group's narrative projects about US$1.9b of revenue and US$266.7 million of earnings by 2029. This setup assumes 4.4% yearly revenue growth and an earnings increase of roughly US$95 million from today’s US$171.4 million level.
Uncover why NorthWestern Energy Group's fair value indicates a 3% potential downside to its current price, suggesting a premium that may not be sustainable.
Exploring Other Perspectives
One alternate story around NorthWestern Energy Group focuses on merger risk rather than data center upside. The most cautious analysts were already using lower 3.3% annual revenue growth and a US$70.0 fair value before this quarter’s earnings. You can treat their stance as a stress test and explore how this latest update might shift either camp’s conviction.
Explore 2 other NorthWestern Energy Group fair value estimates, including one that suggests as much as 77% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NorthWestern Energy Group research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NorthWestern Energy Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NorthWestern Energy Group's overall financial health at a glance.
Looking for more investment ideas beyond NorthWestern Energy Group?
If NorthWestern Energy Group is only one piece of your watchlist, it can help to compare it against other businesses with different income profiles, balance sheets, and dividend approaches. The Simply Wall St Screener gives you a way to line those options up side by side and see which ones genuinely fit your goals.
- If you want income that aims for durability rather than drama, you can start with a shortlist of tougher payout profiles through the 6 dividend fortresses.
- If your focus is on paying less for quality, you can test your valuation discipline by scanning a curated pool of potential bargains using the 42 high quality undervalued stocks.
- If capital preservation ranks high on your checklist, you can cut down the noise and concentrate on sturdier balance sheets and lower risk scores via the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com