


EN
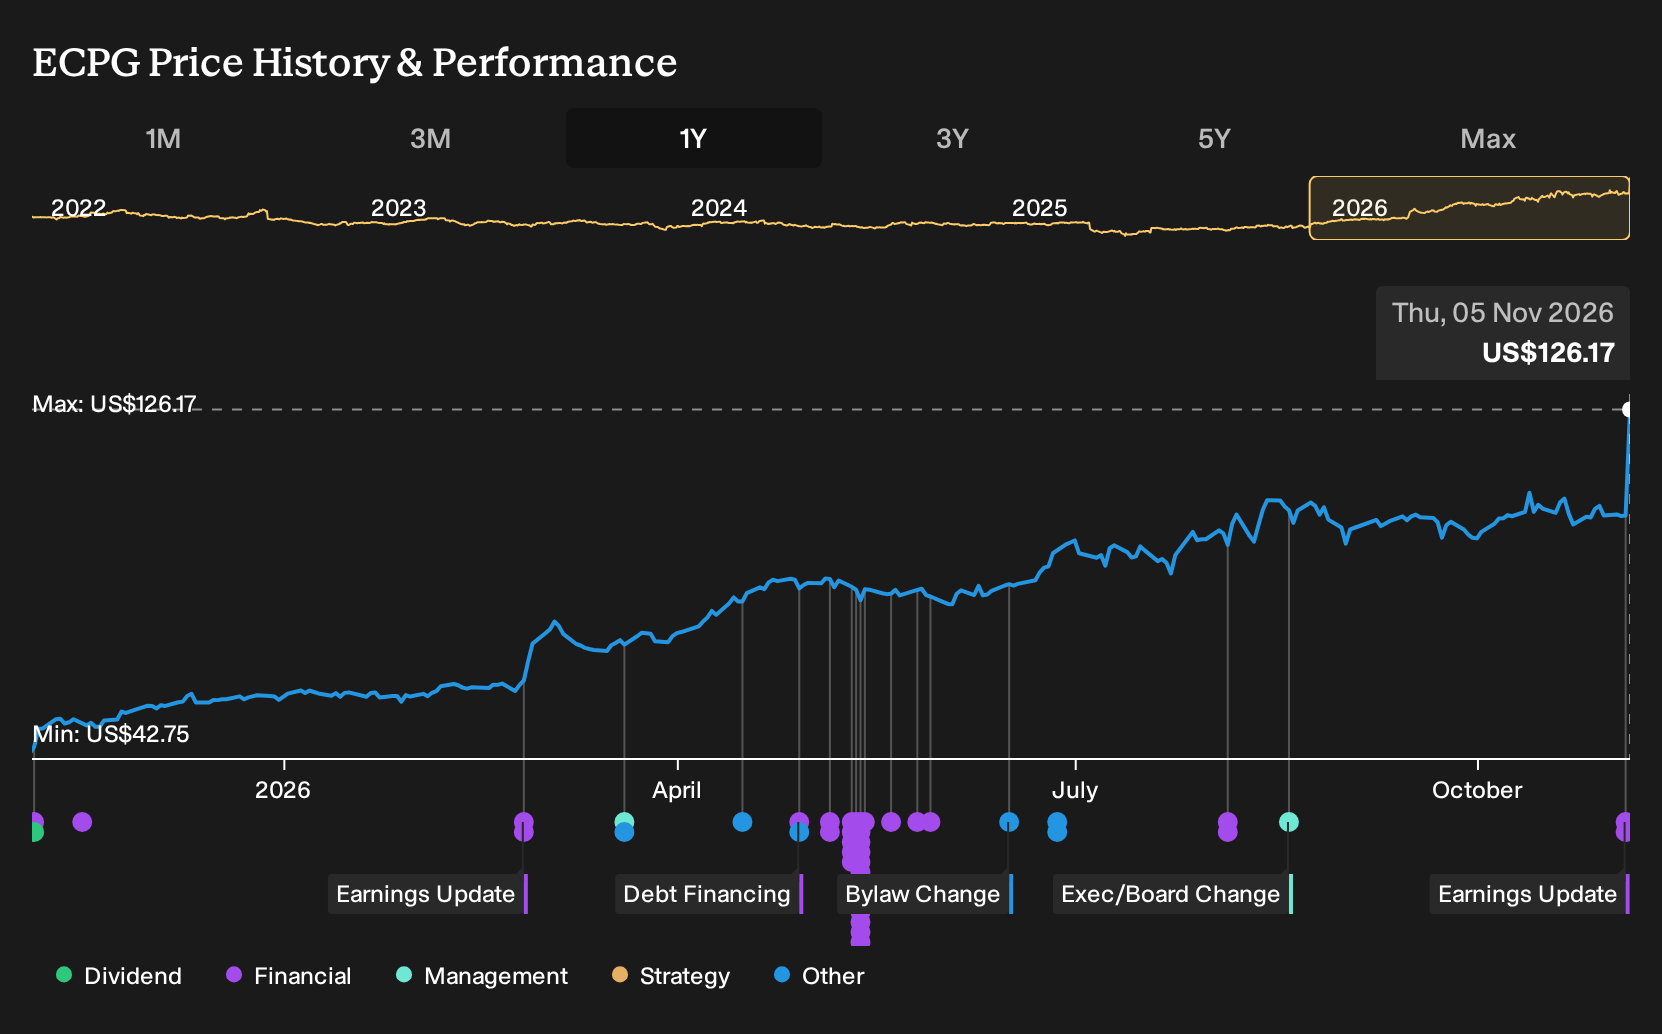
Encore Capital Group Stock In Focus After Earnings Beat And Higher 2026 Guidance
- Encore Capital Group reported Q3 2026 revenue of US$544.54 million and net income of US$124.01 million, with diluted EPS from continuing operations of US$5.57, alongside raised full year 2026 EPS guidance to US$15.50 to US$16.00 per share.
- Record global collections of US$754 million and heavier U.S. portfolio purchasing show Encore Capital Group leaning into rich debt supply and operational efficiencies.
- Now attention turns to how Encore Capital Group's raised 2026 earnings guidance reshapes the existing investment narrative and risk reward balance.
Compare Encore Capital Group's guidance upgrade with a curated set of financially resilient opportunities in our 32 resilient stocks with low risk scores to see how this earnings story compares with other lower risk profiles.
Encore Capital Group Investment Narrative Recap
To own Encore Capital Group, you need to be comfortable with a business built on buying distressed consumer receivables and trying to collect more than it pays, especially in the U.S. market. The latest quarter shows strong collections and higher earnings, which supports that thesis. The near term catalyst is continued rich debt supply in the U.S. The biggest risk remains any shift in credit conditions or regulation that reduces portfolio availability or collection economics.
The new 2026 EPS guidance tightens the focus on execution. Investors now have a clearer earnings bar to watch, which makes collection performance, funding costs and portfolio pricing even more important. If interest expense keeps rising or supply quality weakens, that same guidance range could become harder to meet.
The most relevant update is Encore Capital Group lifting full year 2026 EPS guidance to US$15.50 to US$16.00 per share, described as more than 40% above 2025. That sits on top of Q3 diluted EPS of US$5.57 and record global collections of US$754 million, which gives you a concrete benchmark for near term earnings power.
This raised outlook ties directly into the current catalysts around elevated charge offs, strong U.S. portfolio purchasing and more efficient digital collections. It also magnifies existing risks. Higher leverage, interest costs that have already moved up and reliance on stressed consumer credit conditions all matter more now that the earnings bar is higher and explicitly stated.
Encore Capital Group Analyst Expectations At A Glance
Consensus forecasts for Encore Capital Group sketch out a fairly specific earnings path. Analysts are working off current earnings of US$296.3 million and project that by 2029, earnings could be around US$278.1 million, with an earnings per share figure of US$14.55. That view assumes revenue grows at 1.1% a year over the next three years, while profit margins ease from 16.0% today to 14.5% in that same window. The shift from US$296.3 million to US$278.1 million implies an earnings decline of about US$18 million, which is material when you stack it against the raised 2026 guidance the company has just put on the table.
Encore Capital Group's narrative projects US$1.9b revenue and US$278.1 million earnings by 2029. This assumes 1.1% yearly revenue growth and implies an earnings decrease of about US$18 million from current earnings of US$296.3 million.
Forecasts do not line up perfectly. While the consensus sits at US$278.1 million of profit by 2029, the most optimistic analysts in the group see a path to US$316.8 million. That kind of spread indicates there is real disagreement about how sustainable recent collection strength, portfolio supply, and margin structure will be over the next several years. When forecasts already include a move from a 16.0% margin to 14.5%, any surprise on funding costs, regulation, or portfolio pricing can tilt that earnings number meaningfully in either direction.
On valuation, the consensus framework leans on that US$1.9b revenue and US$278.1 million earnings line in 2029, paired to a P/E of 10.0x, to support a price target of US$113.33 per share. That multiple is higher than the current 6.0x that Encore Capital Group trades on and above the 8.4x P/E cited for the wider U.S. consumer finance peer group. For that gap to make sense to you as an investor, the question is not just whether US$278.1 million in earnings is achievable but also whether a higher multiple on those earnings feels reasonable given the firm’s leverage, regulatory exposure, and dependence on stressed consumer credit conditions.
Uncover why Encore Capital Group's fair value points to a 10% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
The Simply Wall St Community currently contributes 2 fair value views for Encore Capital Group, clustered between US$113.33 and US$120.38 per share. That tight band sits beside much richer 2026 guidance, strong Q3 earnings and higher interest costs. Use those retail forecasts as a reference point and explore how sharply opinions can diverge from updated fundamentals.
Explore another Encore Capital Group fair value estimate, including one that suggests it could be worth as much as $120.38.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Encore Capital Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Encore Capital Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Encore Capital Group's overall financial health at a glance.
Looking for more Encore Capital Group style ideas?
If Encore Capital Group has sharpened your sense of risk and reward, you can broaden your watchlist by scanning for other businesses that fit the kind of profile you want to research next.
- For investors who care most about resilience and capital preservation, start with a 32 resilient stocks with low risk scores that filters for companies with steadier risk profiles.
- If value is the priority and you want to focus on stronger fundamentals at reasonable prices, check out a 21 high quality undiscovered gems that highlights underfollowed stocks with solid financials.
- Income seekers who prefer cash in hand can turn to a 6 dividend fortresses designed to surface higher yielding companies that still clear key quality checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com