


EN
Can Repligen (RGEN) Justify Its Valuation After Revenue Growth And A Large Impairment?
Why Repligen’s latest quarter caught investors’ attention
Repligen (RGEN) just posted third quarter results that paired 10.9% year over year revenue growth with a sharp 65.9% drop in earnings per share, partly tied to US$41.24 million of intangible asset impairments.
Repligen’s share price has retraced sharply in the short term, with a 1 day share price return of down 5.45% and a 7 day share price return of down 10.69%. This comes even though the 1 year total shareholder return is 16.21% and the 5 year total shareholder return is down 36.9%, which points to some recent momentum but a mixed longer term picture.
The latest quarterly loss, the US$41.24 million intangible impairment and the recently announced US$458.6 million 0.25% convertible senior notes due 2031 at an initial conversion price of US$226.37 all contribute to how investors are reassessing both growth potential and risk around Repligen at the current US$168.48 share price.
See how Repligen compares with other specialty healthcare and bioprocessing players facing earnings pressure by checking our curated 32 resilient stocks with low risk scores if you are looking for companies with more resilient risk profiles.
After Repligen’s drop on the impairment news, the choice is simple but uncomfortable: accept today’s reset price, or wait and risk missing any rebound if the valuation already bakes in the bad news?
Most Popular Narrative: 16% Undervalued
Repligen’s most followed valuation storyline pegs fair value at $199.70, above the recent $168.48 close. This puts the latest selloff in a different light for anyone focused on long term cash flows rather than just one rough quarter.
Repligen is investing in expanding dual manufacturing (U.S. and Europe) and increasing APAC presence to address growing customer demand for greater supply chain security and regionalization. This approach is described as a potential driver of resilient sales globally and as a way to reduce revenue concentration risk.
Strategic push into modalities such as cell therapy and ADCs, combined with continued innovation in filtration and PAT-enabled systems, is described as a potential way to enhance product mix toward higher-margin offerings and to support gross margin expansion over the next several years.
See why 10 investors see Repligen as 16% undervalued.
Result: Fair Value of $199.70 (UNDERVALUED)
Still, the narrative around Repligen can change quickly if funding for smaller biotech customers stays weak, or if trade and tariff costs further pressure margins and earnings.
Find out about the key risks to this Repligen narrative.
Another View: What Repligen’s price is baking in
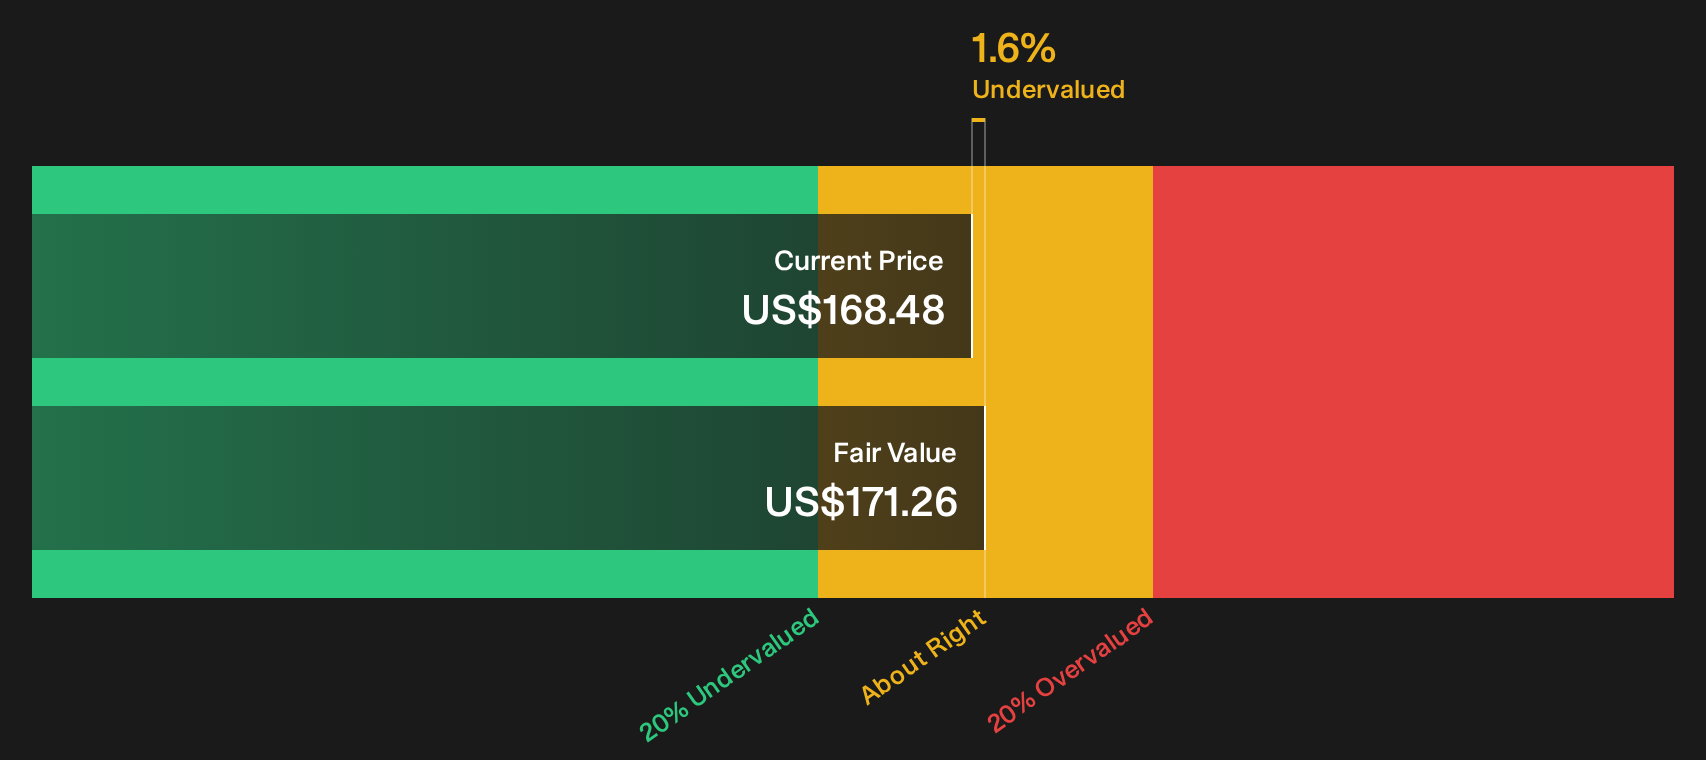
DCF suggests Repligen is only slightly undervalued, with the $168.48 share price sitting about 1.6% below an estimated future cash flow value of $171.26. That is a thin margin of safety. If the story stumbles even a little, how quickly could that gap flip the other way?
For a closer look at how this result is built up over time and how sensitive it is to small changes in assumptions, Look into how the SWS DCF model arrives at its fair value.
Next Steps
After everything you have just read on Repligen, do not let the headlines do the thinking for you. Take a few minutes to review the underlying data, pressure test the assumptions that matter most to you, then weigh those against the 3 key rewards.
Looking for more investment ideas beyond Repligen?
If Repligen has you rethinking risk and reward, do not stop here. Broaden your opportunity set now or you may leave strong ideas on the table.
- Target businesses with pricing power and quality metrics by scanning a 42 high quality undervalued stocks that combines solid fundamentals with potential mispricing.
- Prioritise capital strength and downside protection by filtering through a list of solid balance sheet and fundamentals (24 results) to spot companies with sturdier financial foundations.
- Hunt for less crowded opportunities by reviewing a 21 high quality undiscovered gems that highlights financially sound stocks fewer investors are watching.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com