


EN
Is Eagle Materials (EXP) Cheap After Record Revenue And Buybacks?
Eagle Materials has delivered a solid run over the past few years, even though the share price has pulled back year to date. This puts fresh focus on what investors are actually paying for its cash flows today. With the stock last closing at US$189.24 and the business investing heavily in its operations, the question is how that price lines up with the cash the company can generate over time.
- The share price has gained 21.9% over 5 years, which makes it important to ask whether that journey in the chart is matched by the cash being produced underneath.
- Management is spending on plant modernization and has been buying back stock, which can reshape future cash flows between reinvestment needs and money returned to shareholders.
- If you'd rather focus on earnings, this one's for you. See why Eagle Materials's 15.3x P/E tells a different valuation story.
The issue now is whether Eagle Materials' current share price is adequately supported by the cash flows implied by a Discounted Cash Flow (DCF) view.
If you are weighing Eagle Materials through the lens of its cash flows and DCF, it can help to compare that thinking with other companies screened on similar fundamentals using the 42 high quality undervalued stocks
Does Eagle Materials Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) approach here focuses on the cash Eagle Materials can return to shareholders over time. Over the last twelve months the group produced roughly $356.9 million of free cash flow, and the model expects that pool of cash to grow rather than shrink, with forecasts extending into the early 2030s.
Projected free cash flows rise from analyst estimates into management style extrapolations, which suits a business investing heavily in cement and wallboard capacity. At a share price of US$189.24, the DCF output suggests those future cash streams imply an intrinsic value that is substantially above where the market currently prices Eagle Materials. Record Q2 2027 revenue, together with modernization projects and buybacks, helps explain why the cash flow outlook in the model appears firmer even though the share price has pulled back. Find out what Eagle Materials could be worth using our Discounted Cash Flow (DCF) estimate.
The Eagle Materials Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DCF puzzle on Eagle Materials leaves off by spelling out which paths for growth, profitability and earnings would need to hold for the shares to justify a meaningfully higher or lower price than today. Each scenario links a fair value estimate to a particular mix of potential catalysts and risk factors, so you can watch over time which interpretation of Eagle Materials' future seems to be gaining traction.
One of the top community narratives on Eagle Materials: roughly fairly valued
"The main thing that has to go right is that Eagle Materials completes its Mountain Cement and Duke Wallboard modernization projects on schedule..."
Discover why this Narrative puts Eagle Materials at roughly fairly valued.
The Eagle Materials story is not just about price
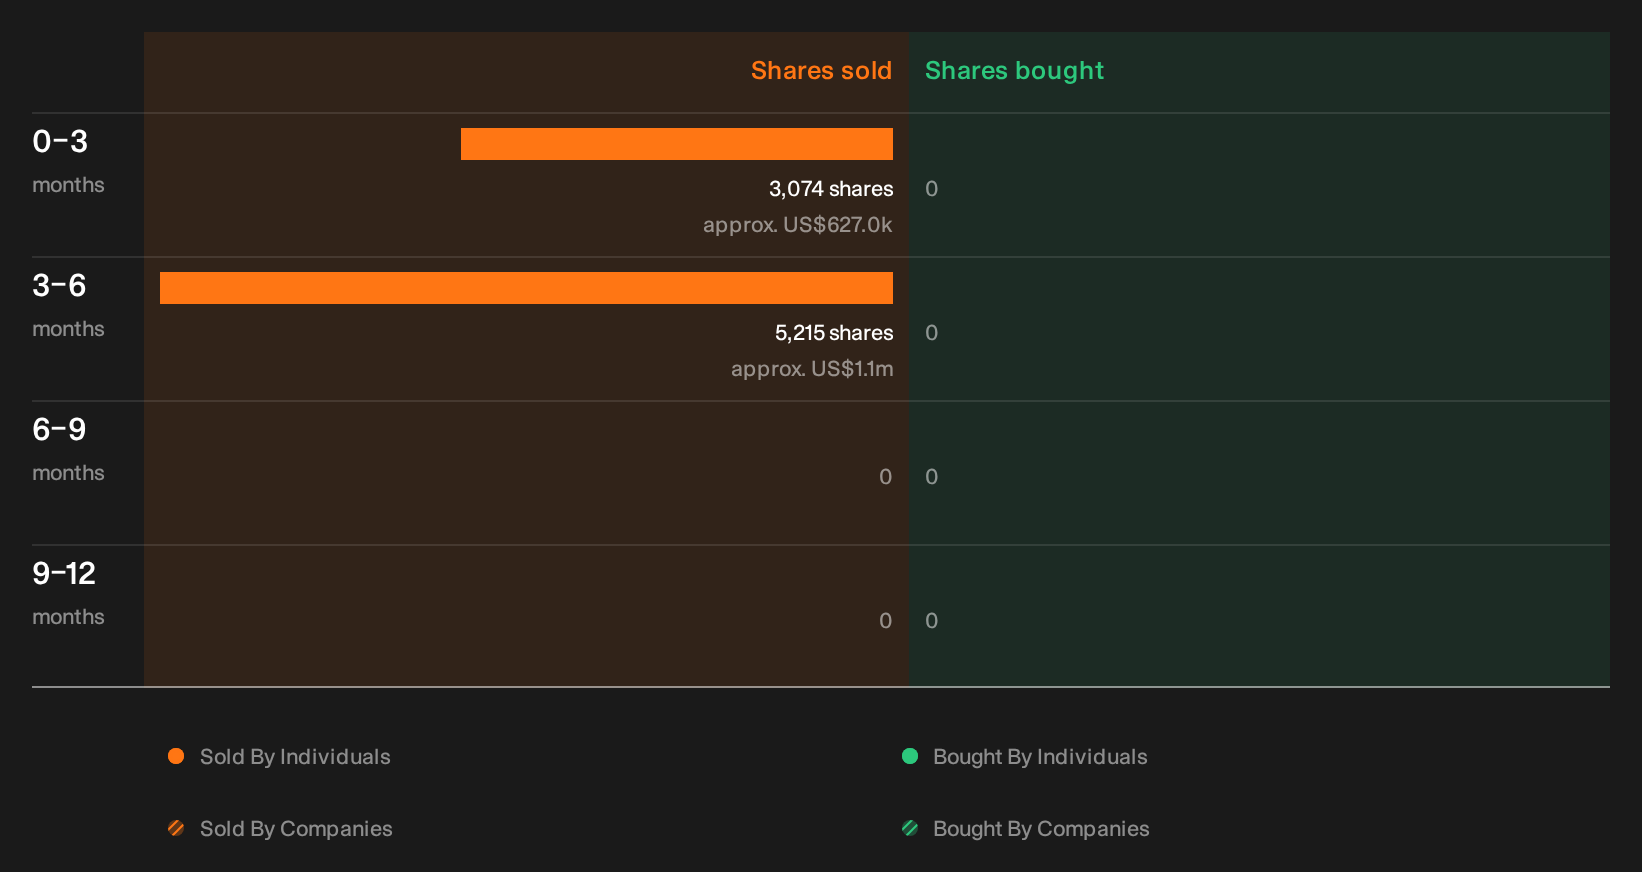
Before deciding what Eagle Materials is worth to you, it helps to know that recent insider trades have been flagged by our checks, and the who, how much and what it might signal are still for you to unpack. See the recent insider selling flagged for Eagle Materials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com