


EN
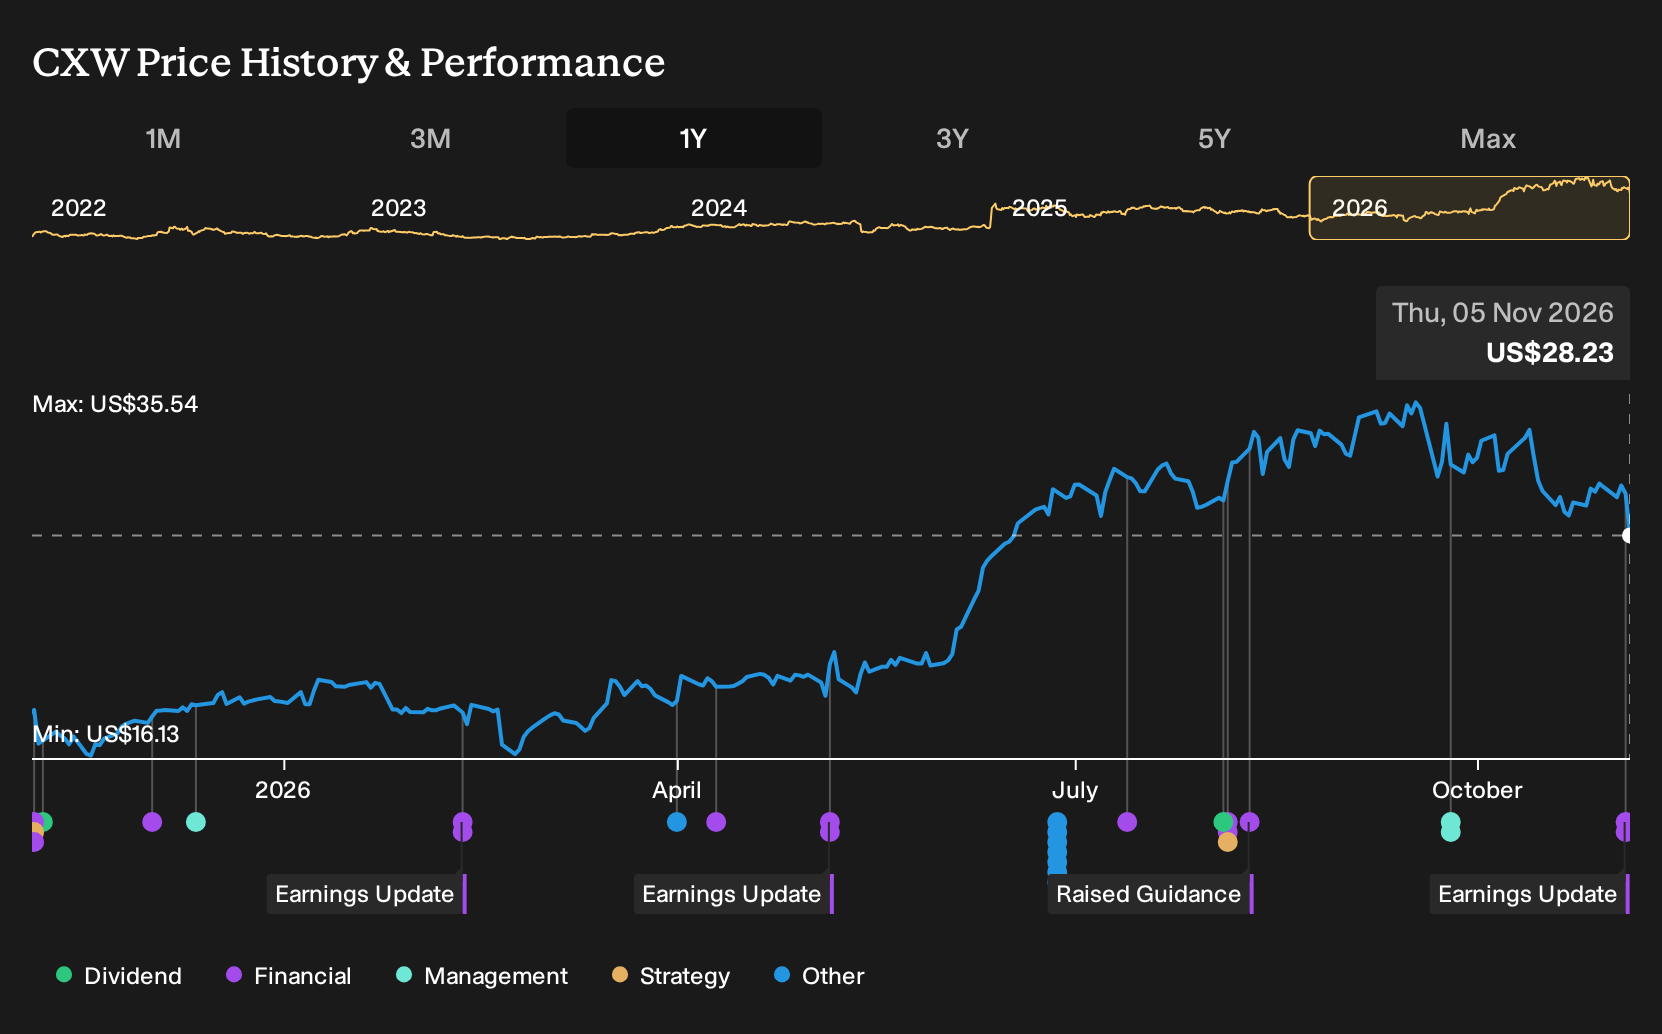
Why CoreCivic Stock Is Down 7.5% And What's Next After Facility Sale
- CoreCivic reported Q3 2026 revenue of US$744.09 million and net income of US$1.34414 billion, aided by a US$2.2 billion sale of four detention facilities to the federal government, while also executing large debt repayment and share repurchases.
- The company slightly reduced full year 2026 earnings guidance after a very large earnings jump, as investors weighed political change, regulatory scrutiny of prison operators and a leadership transition alongside higher federal detention usage and new service offerings such as Clinical Solutions Pharmacy.
- This article examines how CoreCivic's investment narrative is reshaped by Q3 earnings and the US$2.2 billion facility sale to the government.
Scan how other corrections, debt clean ups and political crosswinds are playing out by lining up CoreCivic against the hand picked 32 resilient stocks with low risk scores in one view.
CoreCivic Investment Narrative Recap
For CoreCivic, the core belief is that federal detention demand and related contracts stay supportive enough for high facility utilization, while the newer services arm such as Clinical Solutions Pharmacy builds into a second earnings pillar. The latest quarter showed very high reported profit due to the US$2.2b asset sale and strong ICE usage, but the slight full year guidance trim indicates that management sees some near term noise.
The key near term catalyst is execution on operations and services after the facility sale, especially keeping occupancy healthy while integrating Clinical Solutions Pharmacy. The biggest risk remains policy and funding exposure to ICE and other federal partners, now combined with a leadership transition and recent political change that has already pressured the stock price.
The most relevant update for that thesis is CoreCivic’s refined 2026 earnings guidance. Management now expects diluted EPS of US$15.42 to US$15.48 and net income of US$1.461b to US$1.467b, modestly below prior ranges. That adjustment came directly after a quarter where revenue and earnings from continuing operations were much higher than a year earlier.
For you as a shareholder or potential investor this matters because it helps clarify what portion of the Q3 surge is repeatable. The guidance band, together with the earlier raise to adjusted EPS and EBITDA expectations tied to stable populations and services growth, keeps the focus firmly on contract stability, policy risk and CoreCivic’s ability to translate its reshaped balance sheet into consistent operating performance.
Based on current analyst work, CoreCivic's narrative projects US$3.4b revenue and US$516.8m earnings by 2029. This assumes revenue growth of 11.6% per year and an increase in earnings of about US$388.9m from the current US$127.9m level.
Uncover why CoreCivic's fair value indicates a 48% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate narrative leans hard into CoreCivic’s idle capacity as a potential upside catalyst. Before this Q3 surprise, the most optimistic analysts were sketching out about US$3.6b of 2029 revenue and US$162.1m of earnings, backed by continued ICE demand and new state contracts. Those projections did not factor in this earnings print or the facility sale, so you may see those views shift as fresh forecasts roll in. Use this as a reminder that credible opinions can sit far apart and that your own judgement should weigh several competing stories before you commit capital.
Explore 2 other CoreCivic fair value estimates, including one that suggests an upside potential of as much as 48% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CoreCivic research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CoreCivic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CoreCivic's overall financial health at a glance.
Looking For More Investment Ideas Beyond CoreCivic?
Once you have a view on CoreCivic, it can help to zoom out and compare it with other listed businesses that match the kind of balance sheet strength, income focus, or valuation profile you are looking for. The Simply Wall St Screener can surface different shortlists that you can then filter further based on your own risk tolerance and return goals.
- If capital preservation is high on your list, start by reviewing a curated group of companies with relatively resilient profiles through the 32 resilient stocks with low risk scores.
- If income is your priority, check whether any of the 6 dividend fortresses line up with your yield targets and payout preferences.
- If you are hunting for overlooked opportunities with solid fundamentals, see which of the 21 high quality undiscovered gems align with your own thesis and time horizon.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com