


EN
Greif (GEF) Stock Looks Reasonable As Cost Savings Goals Expand
Greif has treated shareholders to a strong 31.8% gain over the past year, yet recent share price weakness now has investors asking whether that earlier enthusiasm is still supported by the company’s earnings power.
- The 31.8% one year return puts real pressure on the question of whether Greif’s current valuation can still be explained by its profit profile.
- Management’s decision to exit the Coated Recycled Board business and focus on areas where it reports stronger positions may support earnings quality and margin sustainability over time.
- There is a second opinion on Greif worth weighing. See what analysts think Greif's shares could be worth.
The issue now is whether Greif’s recent share price, after a strong year and a softer few weeks, is adequately backed by the earnings it generates today.
If you want a wider set of earnings focused ideas alongside Greif, a targeted screen of 42 high quality undervalued stocks can be a useful next step in your research.
Where Does Greif Sit on Earnings?
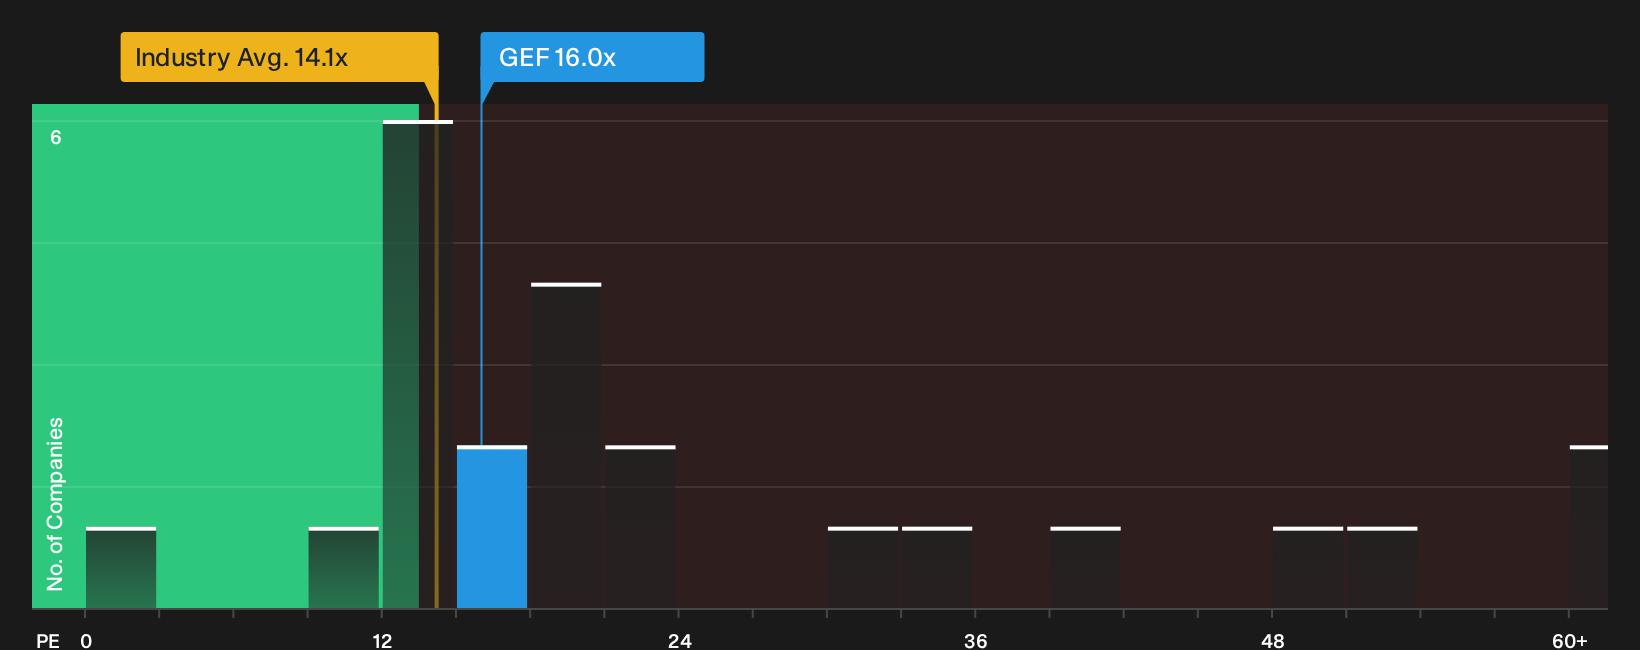
For a mature industrial group like Greif, the P/E ratio gives a clear snapshot of what the market is willing to pay for its earnings stream. The stock trades on roughly 16.0x P/E, which sits slightly above the packaging sector average of about 14.1x and well below the broader peer set closer to 30.0x. That mix points to investors assigning Greif a premium to the typical packaging business while still pricing it below faster rated peers that carry much richer earnings tags.
The Fair Ratio model, which adjusts the benchmark multiple for Greif’s specific mix of margins, growth assumptions, scale and risk, lines up closely with where the shares trade today, so the current P/E screens about right on this framework. Because management has already flagged an exit from the Coated Recycled Board unit and reported higher adjusted earnings in the recent 2026 results, the market seems comfortable keeping the P/E near this tailored mark rather than marking the stock sharply higher or lower. Explore the numbers behind Greif's P/E valuation.
The Greif Narrative: What Would Justify Today's Price?
Greif’s valuation puzzle only really comes into focus once you spell out the future paths for earnings, margins and growth that would need to hold for the share price to sit meaningfully higher or lower than it does today. This is exactly what Simply Wall St Narratives aim to do on the Community page. Each scenario treats Greif’s fair value as a thesis about the business that can be revisited over time rather than a one off snapshot.
One of the top community narratives on Greif: 16% undervalued
"Greif's ongoing cost optimization program, with a defined US$120 million structural savings target by fiscal year-end 2027 and a US$90 million run rate already reached by Q3 2026..."
Discover why this Narrative puts Greif at 16% undervalued.
Before you wrap up on Greif, one more check belongs beside the price tag
All the valuation work only goes so far if you skip the specific risk checks that research has already flagged for Greif, and those red flags are the next thing to weigh. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com