


EN
Expro (XPRO) Swung To A Third Quarter Loss, Is The Stock Still Undervalued?
Expro (XPRO) is back in focus after third quarter results showed a shift from profit to loss, along with tighter full year revenue guidance that narrowed the outlook and appeared to pressure the stock.
Recent trading shows how quickly sentiment around Expro has shifted. The share price has fallen 7.36% over the last day and 25.61% over the past week, while the one year total shareholder return is down 0.85%. This points to fading momentum after a weaker third quarter and tighter guidance, despite the ongoing buyback program.
Scan how Expro’s setback compares with other potential rebound candidates by reviewing our hand picked 42 high quality undervalued stocks that currently screen well on both cash flows and balance sheet strength.
The recent slide leaves Expro trading well below both analyst targets and some intrinsic value estimates, yet the business has just reported a quarterly loss and tighter guidance. Is that discount a sign of caution, or is it an opportunity that reflects the pricing of risk?
Most Popular Narrative: 27% Undervalued
Expro’s most followed valuation view anchors fair value at $17.50 against a last close of $12.84. This frames the recent pullback as a sizeable gap between price and narrative expectations that now hinges on execution.
The planned rollout of Enhanced Drilling’s managed pressure drilling technology from Norway and the U.S. Gulf into additional deepwater basins such as Guyana, Brazil, West Africa, the Caribbean and Australia provides Expro with a path to increase its share on roughly 130 global floating rigs and to support revenue and EBITDA margins.
See why 5 investors see Expro as 27% undervalued.
Result: Fair Value of $17.50 (UNDERVALUED)
Still, the Expro narrative leans heavily on cost cuts and integration going smoothly, while geopolitical shocks in key offshore regions could easily unsettle those assumptions.
Find out about the key risks to this Expro narrative.
Another View: What Expro’s Ratios Are Really Saying
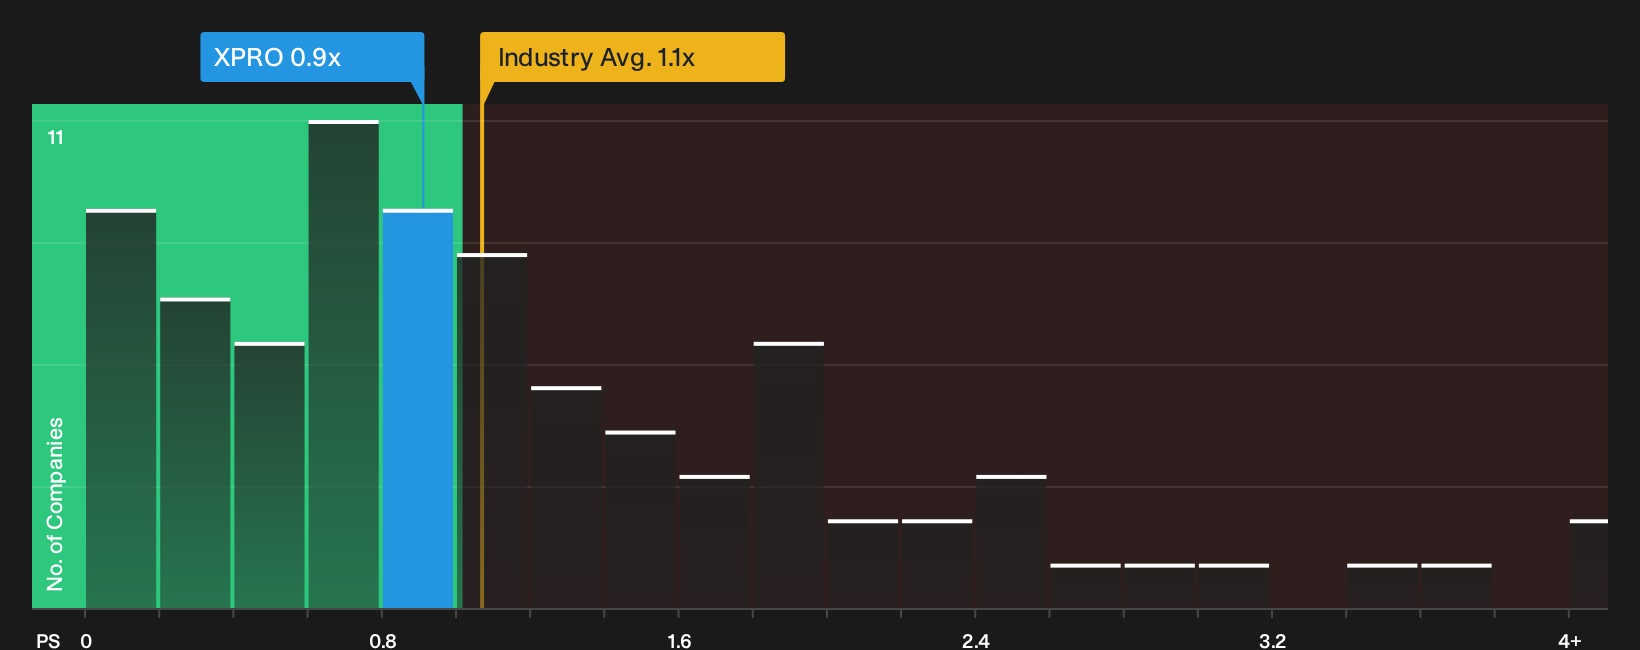
The DCF narrative paints Expro as materially undervalued, yet the simple P/S picture is less generous. The stock trades at 0.9x sales while the fair ratio is 0.7x, and both the US Energy Services industry at 1.1x and direct peers at 1.2x tell a different story about risk and upside. Which signal do you trust more when earnings are this volatile?
For a closer look at how those sales multiples stack up against what the numbers imply as a fair ratio for Expro, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Expro’s setback and potential upside can feel messy, so move quickly to review the underlying data and stress test your own thesis. A good place to start is by weighing the 3 key rewards and 2 important warning signs.
Ready for more investment ideas beyond Expro?
Do not stop at Expro. Broaden your watchlist with a few targeted angles that can surface fresh ideas before the crowd does.
- Target dependable income by scanning for potential yield opportunities in our 6 dividend fortresses and see which payouts look supported by current fundamentals.
- Pressure test your downside risk by reviewing a curated 32 resilient stocks with low risk scores that keeps balance sheet resilience front and center.
- Hunt for underfollowed opportunities by checking a focused 21 high quality undiscovered gems that pairs solid business quality with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com