


EN
3 Great Canadian Quality Stocks To Own In November 2026
Global markets have been hit hard as AI focused stocks slide and high profile chip indices record their worst day since 2020. For Canadian investors, that kind of shock can push money away from crowded tech trades and toward companies with resilient balance sheets, healthy return on equity and solid track records. This article highlights three such Canadian stocks from our quality focused screener.
The three stocks below are just a starter pack from this quality focused screen, and the full results include 2 more Canadian companies with equally compelling stories that are not covered in this article.
If you want to quickly identify candidates with strong return on equity, proven fundamentals and cleaner balance sheets, head straight into the Solid Balance Sheet and Fundamentals screener to filter and analyze the highest conviction ideas for your watchlist.
Lundin Gold (TSX:LUG)
Lundin Gold is a CA$22.1b precious metals producer that develops and operates gold and silver concessions in Ecuador. Its 100% owned Fruta del Norte mine anchors the cash flows that support the company’s balance sheet strength and return profile.
Lundin Gold fits this screener because its entire investment story leans on a single, large producing asset that already generates the kind of cash flows and return on equity profile many miners target in their planning.
"Sustained high margin production at Fruta del Norte, with recent quarters showing strong free cash flow after tax and profit sharing, supports the view that Lundin Gold can continue funding dividends and buybacks from internal cash generation."
The key question is what happens if one pressure point in that setup shifts and those margins come under an unexpected squeeze.
If that single asset risk is what you keep circling back to, read the full narrative for Lundin Gold to see how those pressures could reshape Lundin Gold’s trajectory.

Sprott (TSX:SII)
Sprott is a Toronto based asset manager focused on natural resources and precious metals, where its mutual funds and ETFs generate fee based recurring revenue that ties closely to a solid balance sheet theme. The stock is valued at about CA$4.0b.
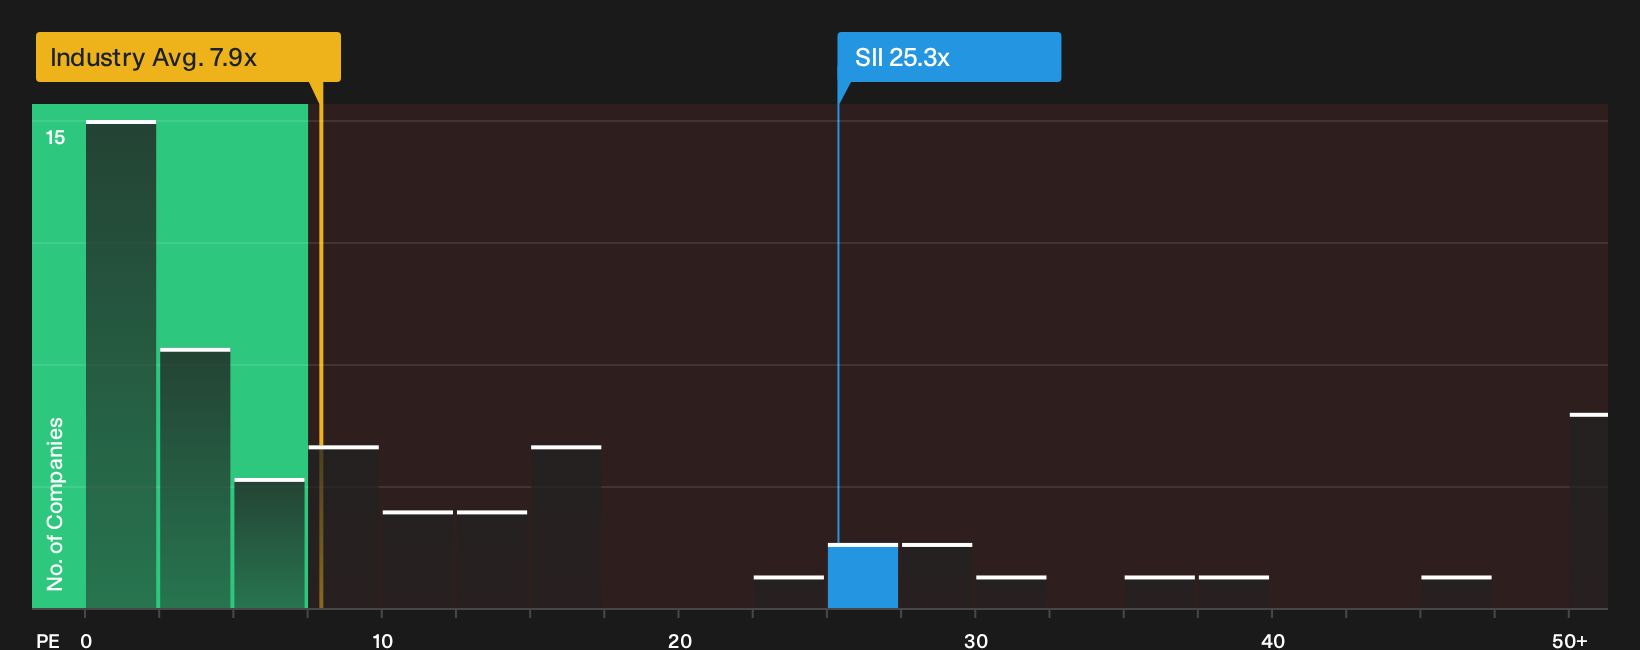
Sprott leans into this quality screen through its resource focused funds and ETFs, which feed recurring fees into a high 28.5% ROE and 27.9% profit margin. That combination of strong earnings and a premium P/E of 25.3x has appeal, depending on how one unseen pressure plays out.
That trade off makes it worth running through the analysis report for Sprott to see whether Sprott’s premium multiples reflect durable economics or just headline excitement.
OceanaGold (TSX:OGC)
OceanaGold is a CA$7.9b gold and copper producer with mines in the United States, the Philippines and New Zealand, where cash generating operations like Haile and Didipio underpin the solid balance sheet and high return on equity profile that fits this quality focused screen.
For the Solid Balance Sheet and Fundamentals theme, OceanaGold matters because its producing mines already generate the kind of cash and returns most miners only model on paper. This sets up a very different discussion when you look at how those assets are being expanded.
"Optimization and expansion at Didipio, including restoration of normal underground rates and a targeted 2.5 million tonne annual mining rate by 2026, is expected to increase copper and gold output from an already low cost asset, enhancing consolidated cash flow and margins."
The central issue is what happens to those margins and cash returns if a single assumption in that wider growth and capital return plan does not hold.
If that single weak link is what you keep coming back to, read the full narrative for OceanaGold to see how OceanaGold’s expansion plans could accelerate or stall.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the next breakout ideas rarely stay quiet for long. Use these curated lists while they are still under the radar for now and consider them while conditions remain favorable.
- Look for potential opportunities early by scanning curated 6 high quality undervalued stocks before momentum traders notice them and strong cash generators attract more attention.
- Focus on the AI infrastructure build out by examining 53 AI infrastructure stocks ahead of shifts in demand, funding and headlines that may draw more interest to these enablers.
- Prepare for possible moves in materials by tracking curated 33 elite gold producer stocks before capital returns to producers and high-quality opportunities become more widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com