


EN
Earnings Beat Could Be A Catalyst For Albemarle Stock (ALB)
- Albemarle reported third quarter 2026 revenue of US$1.55b and net income of US$296.8 million, with adjusted EPS of US$2.58 exceeding analyst expectations and reversing a loss from the prior year.
- Alongside the earnings beat, Albemarle raised its Specialties outlook and trimmed capital spending plans, which points to tighter cost control and improved operational efficiency, while lithium driven Energy Storage sales showed strong year over year growth.
- We now look at how Albemarle's earnings beat and higher profitability reshape the investment narrative that previously centered on cost discipline.
Albemarle Investment Narrative Recap
To own Albemarle, you need to believe its lithium and Specialties businesses can earn solid returns through volatile pricing cycles. The latest quarter supports that case at an operating level. Net sales of US$1.55b and net income of US$296.8 million point to a business that is currently converting volumes and pricing into profit, even as lithium markets stay choppy.
The key near term swing factor is still lithium pricing and how quickly contracts reset. Management is trimming capital spending and lifting Specialties expectations, which helps near term cash generation. The biggest risk remains a long stretch of weak lithium prices or oversupply that keeps pressure on Energy Storage earnings despite current cost savings.
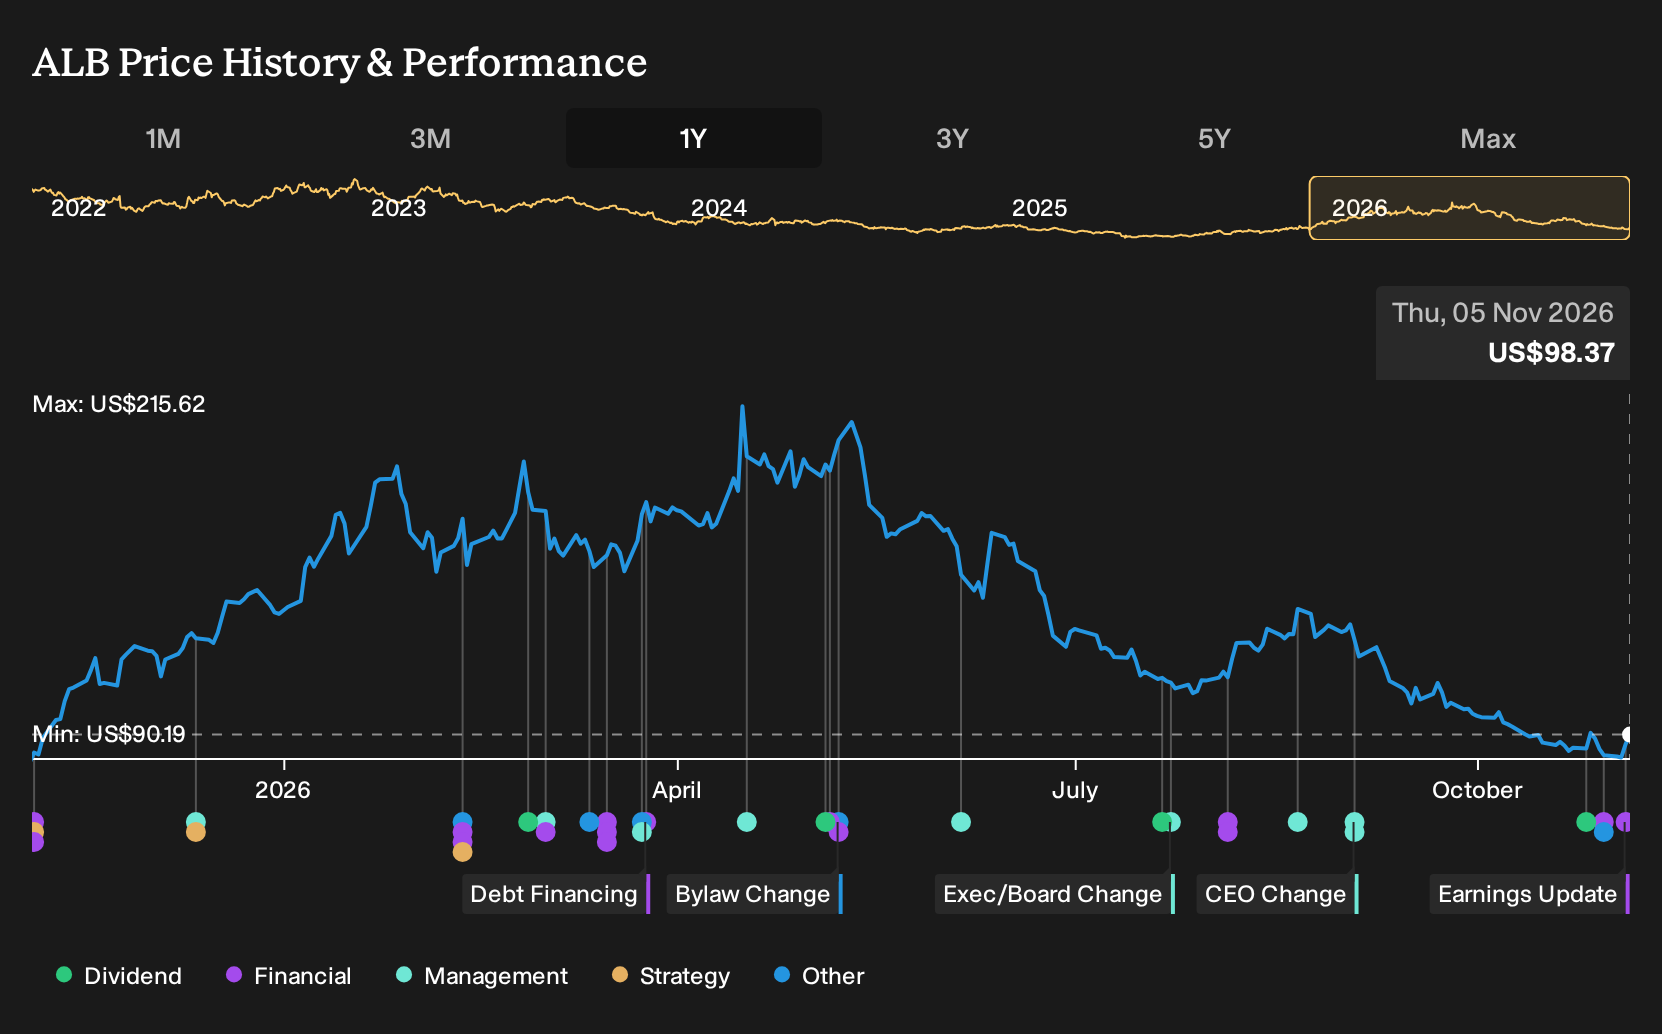
The revolving credit facility announced on October 29, 2026 is important for this earnings story. Albemarle now has access to up to US$1.5b of unsecured liquidity out to 2031, with a leverage covenant set at 3.50x and a small step up allowed around larger debt funded acquisitions.
For you as a shareholder, that facility affects how credible the current playbook looks. A longer dated, covenant based pool of funding can support working capital through lithium pricing swings, fund selective growth projects and back the dividend that was recently reaffirmed, while still keeping an explicit ceiling on leverage as management balances opportunity and risk.
Albemarle's current earnings are US$57.4 million, with analysts projecting revenues of US$6.8b and earnings of US$2.5b by 2029. This outlook implies 4.8% yearly revenue growth and an earnings increase of about US$2.44b compared to current earnings.
Uncover why Albemarle's fair value indicates a 57% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist you might explore is the idea that Albemarle could lean into higher cost savings and volume growth than consensus assumes. The most optimistic analysts were already penciling in revenue of about US$8.4b and earnings of roughly US$3.1b by 2029, before this earnings beat. Their story may shift again from here.
Explore 3 other Albemarle fair value estimates, including one that suggests as much as 170% potential increase from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Albemarle research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Albemarle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Albemarle's overall financial health at a glance.
Looking for more Albemarle style ideas?
If Albemarle has sharpened your focus on balance sheets, cash generation and earnings quality, it can be useful to line it up against a broader set of opportunities that match your risk and income preferences.
- If you want potential upside but still care about fundamentals, start with a few of the most attractively priced quality companies through the 42 high quality undervalued stocks.
- For readers who put capital preservation first, filter for businesses with steadier profiles and stronger resilience using the 32 resilient stocks with low risk scores.
- If dependable payouts matter to your plan, scan companies that combine higher yields with more durable cash flows via the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com