


EN
What Investors Overlooked Before Banco Bradesco Slid
If you only glanced at Banco Bradesco’s latest figures, with higher revenue, stronger profit and a wider net margin on record in Q3 2026, it might look like the kind of bank investors wanted to own. Holding Banco Bradesco over the past year would have meant a 20.9% loss, including dividends. If you had been weighing a position back in November 2025, what signals were already hinting that this gap between business and return could open up?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Banco Bradesco harder to judge, start where the gap is still open and scan 230 high quality undervalued stocks.
The Two Banco Bradesco Stories Investors Were Pricing In
The shares cost R$18.79 at the start of the period, and anyone looking at Banco Bradesco then had to choose between two very different stories that still sounded reasonable.
On the optimistic side, the bull Narrative put Fair Value at R$24, or 28% above the start price. It leaned on digital transformation, AI and proprietary tech to push efficiency. Expanding digital platforms and financial inclusion were expected to support stronger fee, insurance and wealth revenues.
The bear Narrative argued for Fair Value of R$15, or 20% below the start price. It focused on fintech and neobank competition eroding traditional income. High operational costs and regulatory pressures were seen as making meaningful cost reduction difficult.
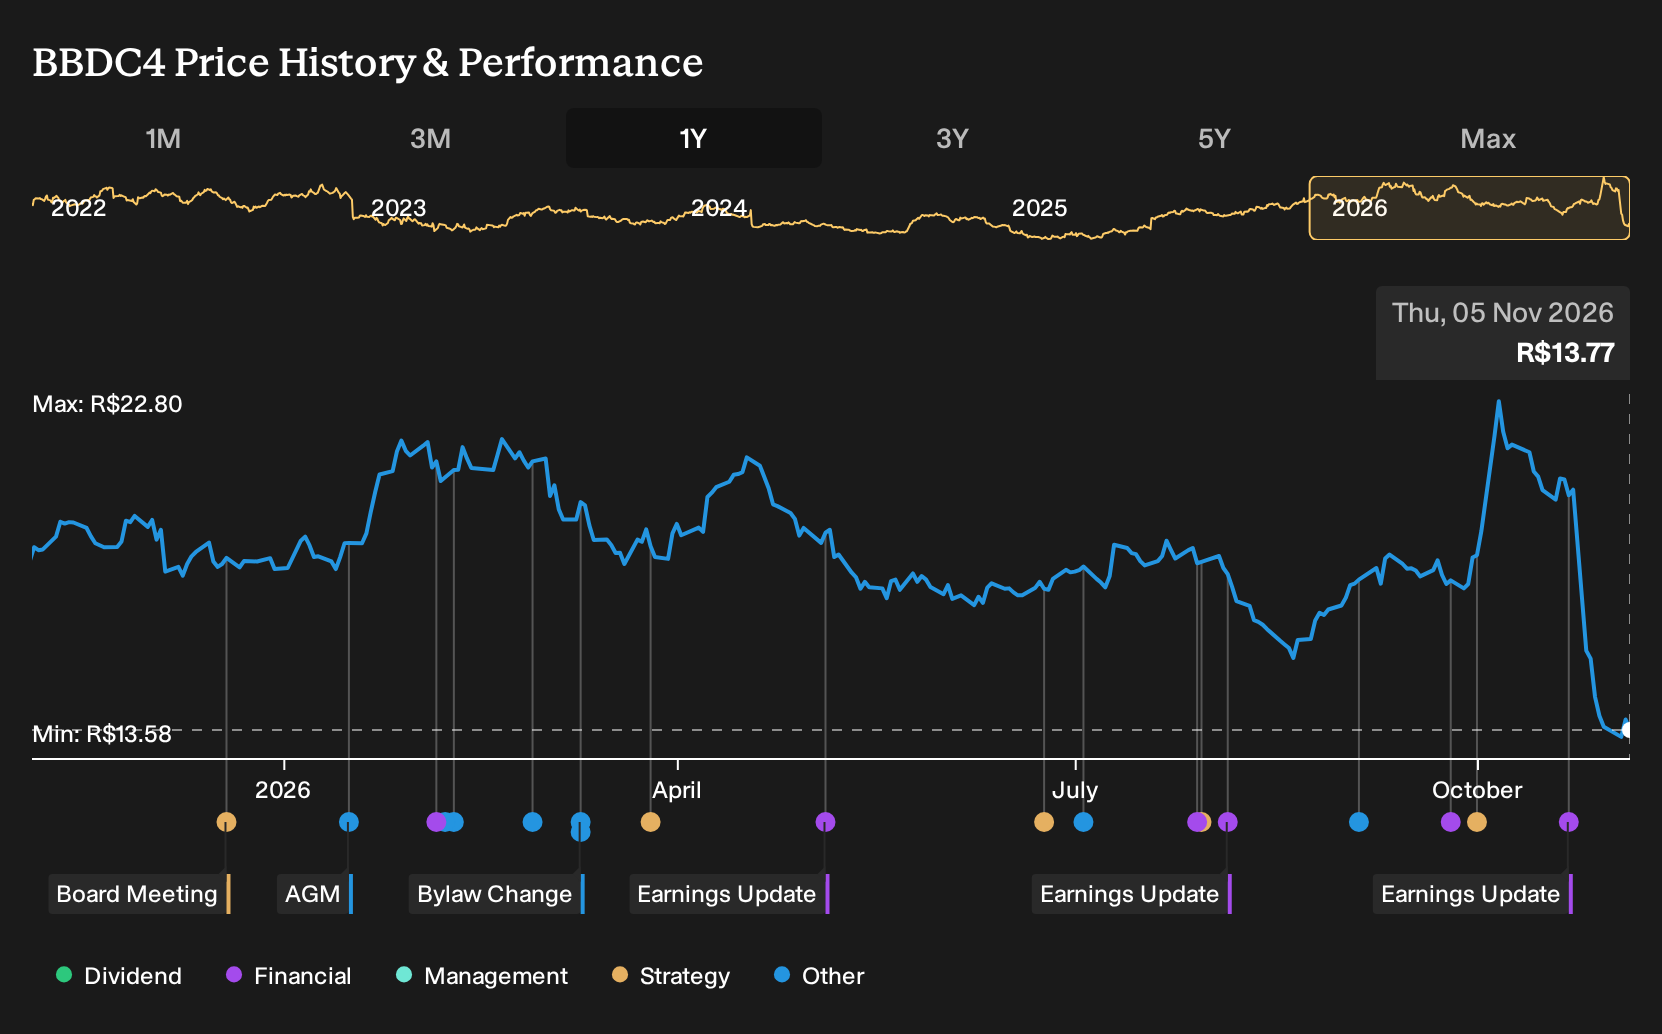
What The Results Changed For The Banco Bradesco Narratives
Lula’s runoff victory in late 2026 gave Banco Bradesco investors a fresh political curveball that leaned toward the cautious case, as Brazil-linked shares fell following the result. Q3 2026 briefly pulled attention back to the business itself. Revenue reached R$23,803.159m and net income R$7,330.161m, with net margin at 30.8% versus 26.0% a year earlier, so the evidence cut both ways.
The key lesson is simple. When a thesis hangs on efficiency and competitive pressure, watch net margin against the original decision date and test how it moves after political or regulatory shocks arrive.
What You Are Really Paying For In Banco Bradesco Today
Banco Bradesco now trades at R$13.77, after the share price fell 20.9% over the past year from R$18.79. The selected Narrative still places its Fair Value above that level, based on what it sees in the franchise rather than any guaranteed outcome.
The argument leans heavily on secured and government backed lending, plus fee and insurance lines, to do more of the earnings heavy lifting. For that higher Fair Value to be reached, a buyer today would need to assume Bradesco keeps cost of risk and operating expenses tight while also deepening those secured and digital client relationships.
"The main factor that has to go right is that Bradesco continues to grow secured and government-backed lending, fee and insurance income, and digital client relationships while keeping cost of risk and operating expenses under control."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
How Could You Get There Earlier?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 38% below our estimate - targets AI-driven freight demand and compliance projects to maintain forwarding utilization.
- Company 2 - 23% below our estimate - expands maintenance-oriented sales teams to accelerate contract signings and deepen route efficiency.
- Company 3 - 27% below our estimate - uses a unified technology platform and AI tools to handle investment inflows efficiently.
Those are three of them. See all 193 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com