


EN
Is Boise Cascade (BCC) Fully Priced After Strong Q3 Sales Growth?
Boise Cascade has delivered a 37.5% gain over the past 5 years, yet its recent share moves and news flow raise a straightforward question for you as an investor. Is the current US$73.75 price properly supported by the earnings power the business is generating today?
- The 37.5% return over 5 years puts real weight on whether Boise Cascade's current earnings can support that longer term share performance.
- Recent updates on sales growth, supplier transitions and capital returns can reshape how durable the company’s margins and future profit streams look.
- Your read on Boise Cascade is one view; the desks covering it have another. See what analysts think Boise Cascade's shares could be worth.
The issue now is whether Boise Cascade's present share price is justified by its earnings when measured against the Fair Ratio benchmark.
If you want to stress test the same earnings question you are asking of Boise Cascade against a wider field, scan through 42 high quality undervalued stocks.
Is Boise Cascade a Bargain on Earnings?
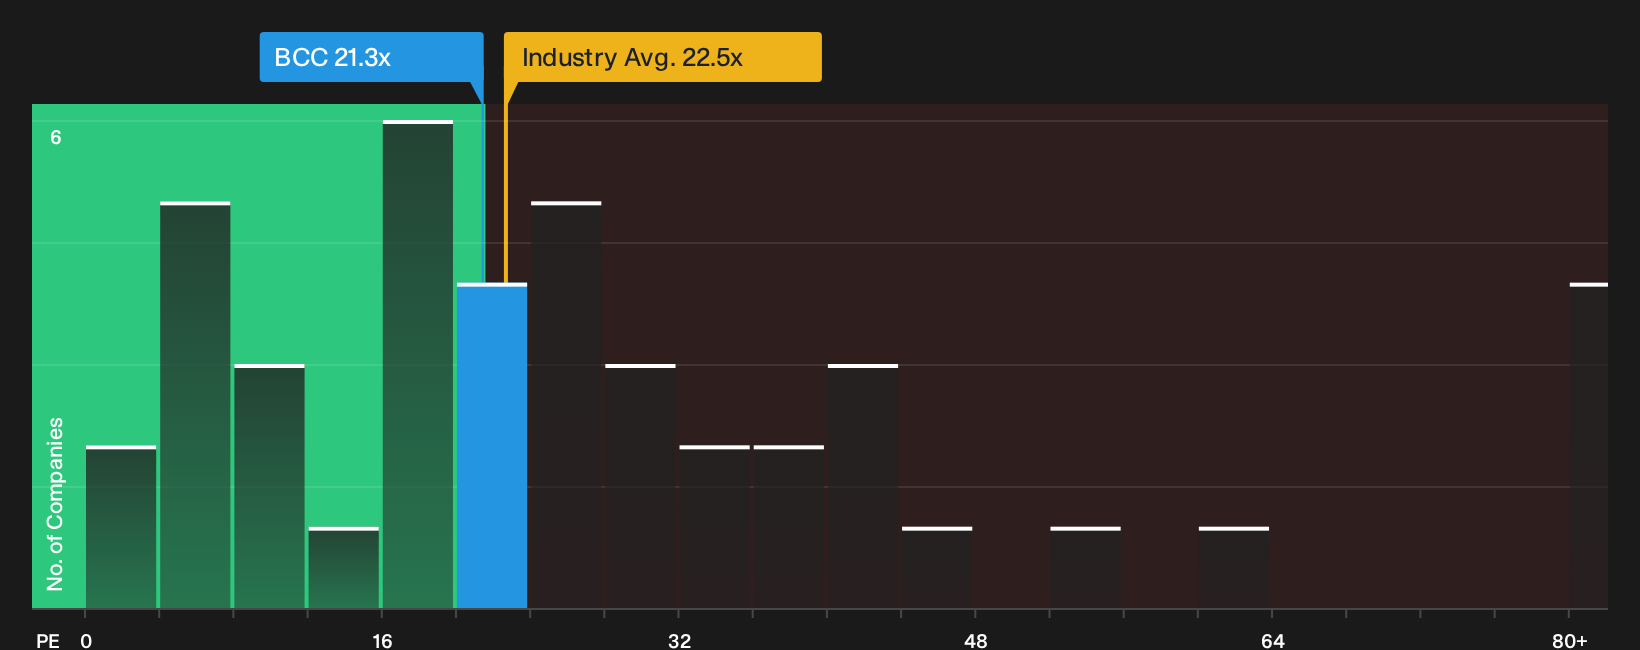
The P/E ratio is a useful lens here because earnings remain the main anchor for how investors weigh Boise Cascade against other distributors. On current numbers the stock trades on about 21.3x earnings, compared with roughly 22.5x for the wider Trade Distributors industry and a peer group closer to 66.0x, which puts Boise Cascade toward the lower end of the pack on this metric.
That discount comes even after solid Q3 2026 sales and the supplier transition news. The Fair Ratio framework suggests a higher P/E would be consistent with Boise Cascade's risk and return profile, so the present level screens as undervalued on earnings. The modelled Fair Ratio reflects factors such as sector, size and profitability rather than raw averages, so the gap implies the market is currently applying a more cautious label to the stock than that tailored benchmark. Explore the numbers behind Boise Cascade's P/E valuation.
The Boise Cascade Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle on Boise Cascade leaves off. They spell out what kind of future growth, margin profile and earnings path would need to line up for the shares to look meaningfully cheaper or more expensive than today. Rather than a single ratio or one model output, each narrative lays out the assumptions behind its fair value so you can compare those moving parts with Boise Cascade's actual results as they come through.
One of the top community narratives on Boise Cascade: 19% undervalued
"The current valuation implies that Boise Cascade’s share price does not fully reflect the company’s integrated model, long-term housing demand drivers, and recent capital returns…"
Discover why this Narrative puts Boise Cascade at 19% undervalued.
One more Boise Cascade check that belongs beside the P/E
Price ratios tell you what the market pays for Boise Cascade today. The next layer is how professional analysts currently map out the business a few years from now. Explore where analysts expect Boise Cascade to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com