


EN
Can Veeva Systems (VEEV) Justify Its Price On Future Cash Flow?
Veeva Systems has rewarded long term holders with a powerful share price run. That naturally shifts the spotlight to whether the current US$310.10 level lines up with the cash the business is expected to generate. With fresh product news in life sciences customer engagement, the question now is how much of that optimism is already embedded in the stock.
- Over the past 3 years the share price has gained 86.1%, putting a lot of weight on the durability and scale of Veeva Systems' future cash flows.
- New commitments such as UCB adopting Vault CRM, alongside broader interest in Veeva's AI driven commercial and data platforms, can support expectations for more recurring cash generation from pharmaceutical clients.
- If you'd rather focus on earnings, this one's for you. See why Veeva Systems's 49.5x P/E tells a different valuation story.
The issue now is whether that recent performance and product traction are justified by the intrinsic value suggested by Veeva Systems' cash flows.
If you want a wider watchlist of companies tying AI to recurring revenue, a focused screen of 41 profitable AI stocks that aren't just burning cash is a straightforward next step for research.
Where Does Veeva Systems Sit on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Veeva Systems can return to shareholders over time. Latest twelve month free cash flow sits at about $1.64b, and analyst projections in the model point to growing free cash generation through at least 2031, with the second stage assuming this expansion tapers rather than accelerates.
For a stock trading at $310.10, that pattern presents Veeva as a business already producing meaningful cash, rather than a pre-profit story where everything rests on distant hopes. The recent decision by UCB to adopt Vault CRM, together with interest in Veeva's AI driven platforms, helps explain why the DCF outcome places the estimated intrinsic value broadly in line with where the market currently prices the shares. Find out what Veeva Systems could be worth using our Discounted Cash Flow (DCF) estimate.
The Veeva Systems Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Veeva Systems valuation puzzle leaves off, spelling out which paths for growth, margins, and earnings would need to play out for the stock to make clear sense at meaningfully higher or lower levels than today’s price. Each Narrative treats Veeva Systems' fair value as a thesis about how the business might develop that can be tracked over time rather than a one off snapshot. These Narratives are available on Simply Wall St's Community page.
Community views on Veeva Systems split between those who see extra upside and those who think most of the story is already accounted for.
Bull case: 19% undervalued
"Switching costs are strongest when changing vendors creates professional, operational, or regulatory danger..."
Discover why this Narrative puts Veeva Systems at 19% undervalued.
Bear case: roughly fairly valued
"The main thing that has to go right is that newer areas like Vault AI, Falcon agentic labor, large clinical and quality applications, and data products such as Crossix and OpenData scale fast enough to offset slowing growth in mature R&D tools..."
Explore why this Narrative puts Veeva Systems at roughly fairly valued.
One more Veeva Systems check that sits alongside the cash flow story
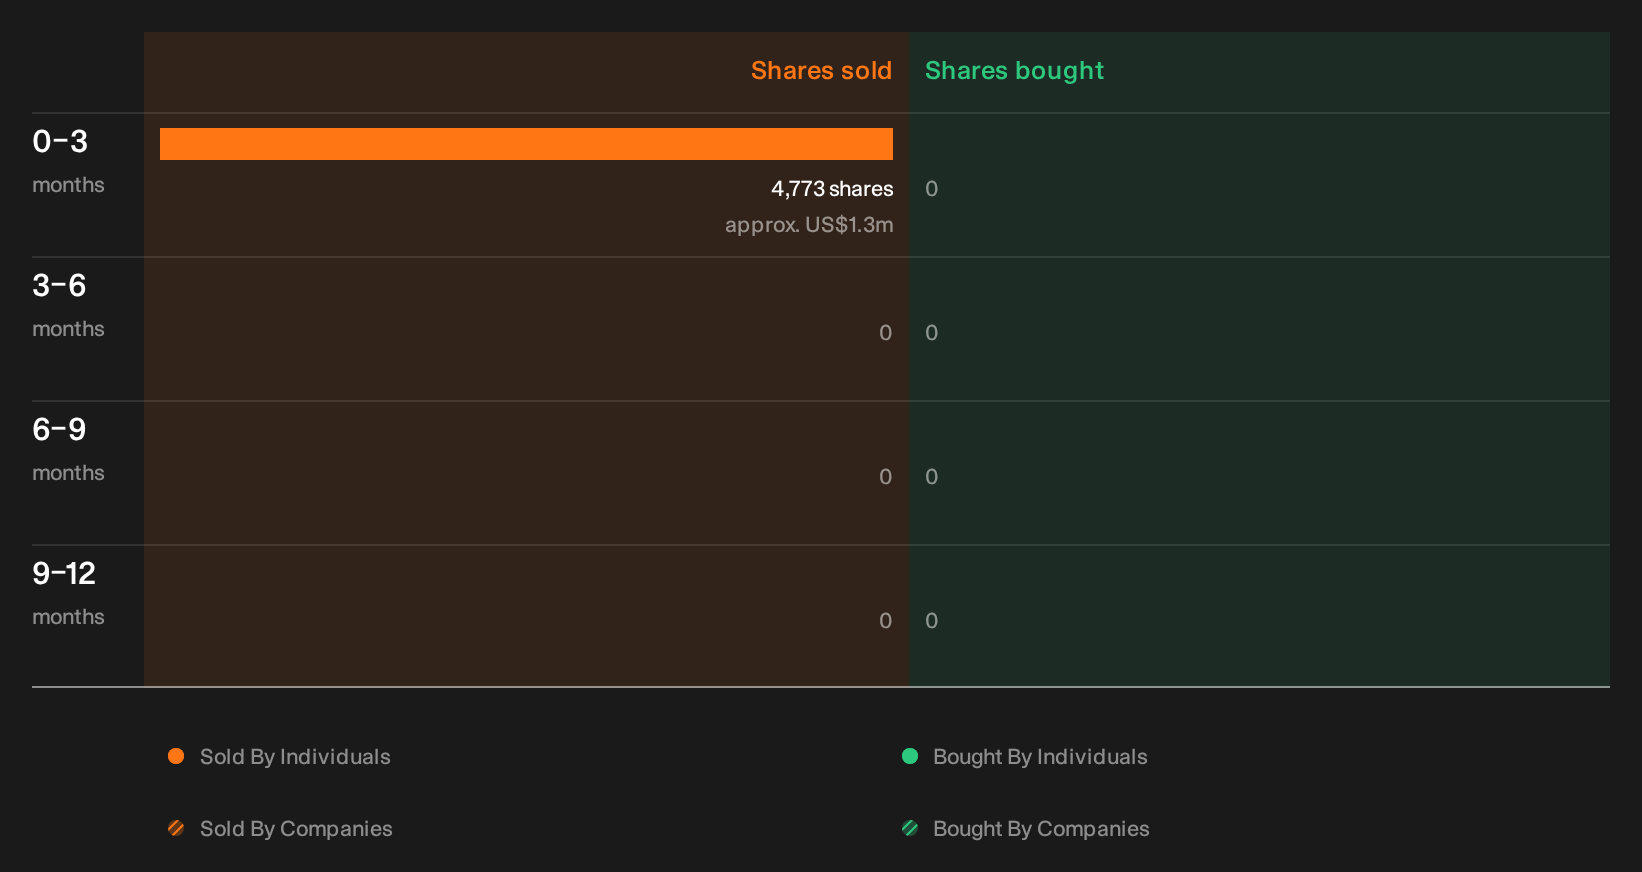
Price, cash generation and product traction tell only part of the Veeva Systems story, because recent trades by company insiders can add a very different clue about how those closest to the business are acting. See the recent insider selling flagged for Veeva Systems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com