


EN
What Is Going On With Trex Company (TREX)?
Trex Company (TREX) just reported record third quarter revenue and raised its full year outlook, after volume driven sales and a major distribution reshuffle outpaced expectations and caught the market’s attention.
Trex Company has ridden this earnings beat into a sharp near term rerating, with a 7 day share price return of 10.15% and a 30 day gain of 24.86%. This adds to a 56.32% year to date share price move and a 75.47% 1 year total shareholder return, even though the 3 and 5 year total shareholder returns remain in decline. This combination signals strong recent momentum building on a weaker longer term record.
Scan how Trex Company’s earnings momentum compares with other building and materials players by reviewing our curated list of list of solid balance sheet and fundamentals (24 results)
Trex Company now sits between two narratives. Either the sharp rerating simply caught up with improving fundamentals, or short term enthusiasm has pushed the stock ahead of what the business currently justifies.
Most Popular Narrative: 2% Overvalued
Trex Company closed at $56.01 while the most followed narrative pegs fair value at about $54.67. The recent rally now leans slightly ahead of that framework and puts more weight on whether its capacity and cash generation plans play out as expected.
The buildout and ramp of the Little Rock facility, designed as Trex's lowest cost and most automated plant with modular lines and advanced recycling technology that can handle dirtier waste streams, is expected to support up to about US$1.8 to US$2.0 billion of core product revenue capacity and can influence future gross margin and EBITDA margin as utilization improves.
See why 6 investors see Trex Company as 2% overvalued.
Result: Fair Value of $54.67 (OVERVALUED)
Still, Trex Company faces two pressure points that could flip this story: persistent manufacturing inefficiencies at Little Rock and high SG&A that limits margin progress.
Find out about the key risks to this Trex Company narrative.
Another View: Trex Company Through Cash Flow
The first narrative leans on analyst price targets around $54.67 and labels Trex Company as about 2% overvalued. A different lens tells a sharper story. The Simply Wall St DCF model estimates Trex at $73.16, which implies the shares trade about 23.4% below that cash flow based fair value. Which signal feels more convincing to you?
For readers who rely more on modeled cash flows than on earnings multiples or consensus targets, it can help to see exactly how those projected streams add up in practice. Look into how the SWS DCF model arrives at its fair value.
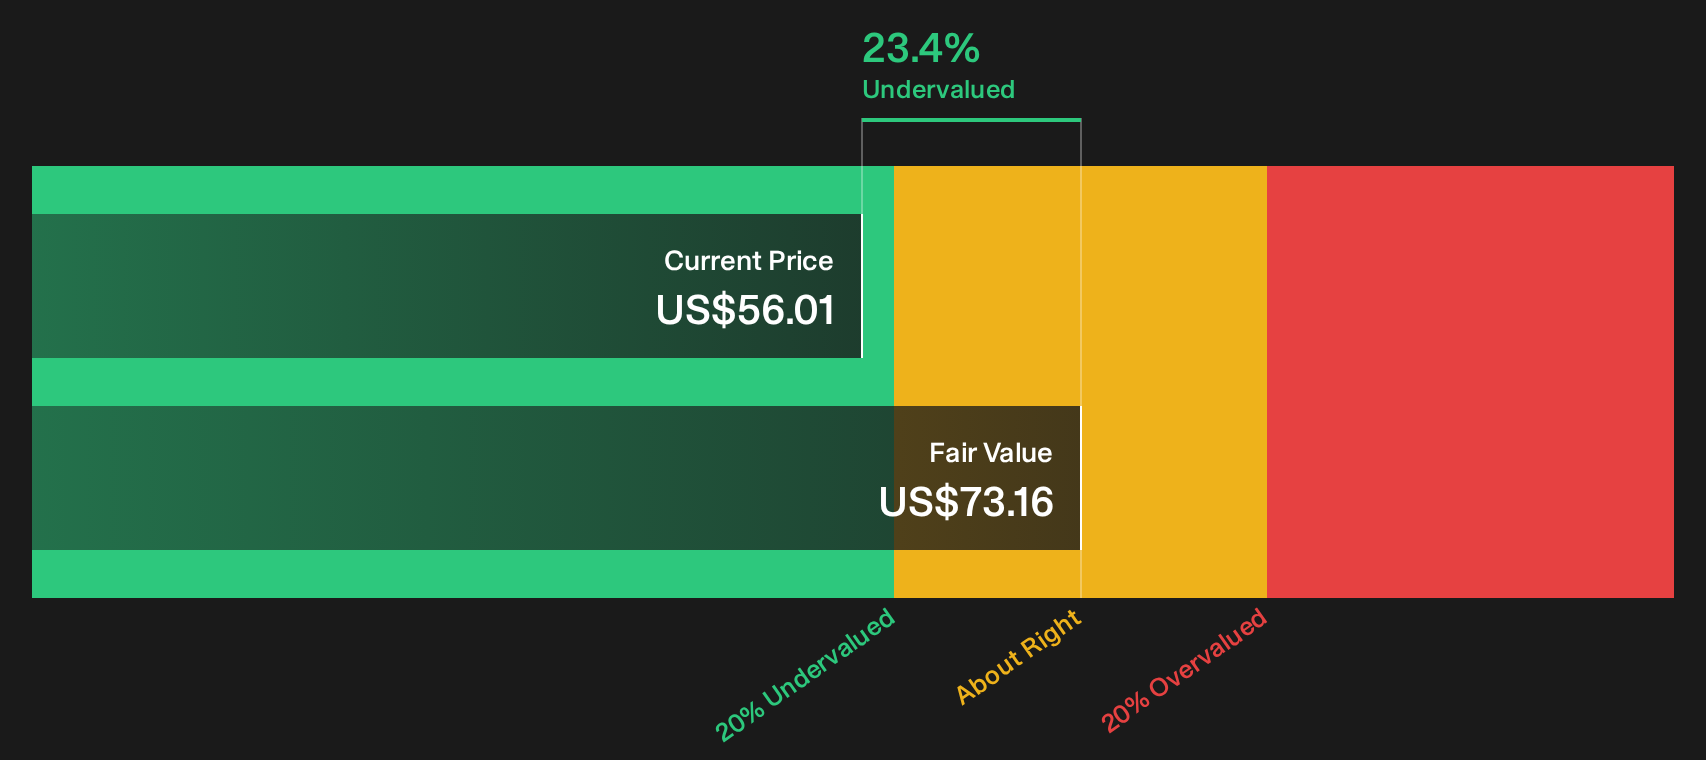
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Trex Company for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Trex Company feels familiar, do not sit on the sidelines. Review the upside drivers in the 2 key rewards
Looking for more investment ideas beyond Trex Company?
Trex Company might be front of mind right now, but your next strong idea could be waiting in a corner of the market you are not watching yet.
Use the Simply Wall St screener to widen your opportunity set before the market moves first.
- Target firms with strong cash generation and quality fundamentals through our 42 high quality undervalued stocks for ideas that may not yet be fully appreciated.
- Strengthen your income stream by focusing on companies in the 6 dividend fortresses that aim to combine resilience with higher yielding payouts.
- Dial down portfolio risk by scanning the 32 resilient stocks with low risk scores and concentrating on businesses that score well on financial strength and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com