


EN
Main Street Capital (MAIN) Stock Could Be 31% Overvalued After Dividend Hike
Main Street Capital has delivered strong long term share returns, and the recent dividend moves and funding decisions now put the focus on whether those gains line up with the returns the business earns on its capital.
- Over the past 5 years the stock has returned 83.8%, which raises the question of how closely that share performance tracks the profitability of the investments on Main Street Capital's balance sheet.
- Recent dividend increases and the continued use of supplemental payouts, alongside fresh debt funding at a fixed coupon, can signal how management balances distributing cash to shareholders with reinvesting at attractive returns.
- What if you looked at Main Street Capital through its earnings instead? See what Main Street Capital's 11.8x P/E says about the price.
The issue now is whether the current share price is fully supported by the returns Main Street Capital earns on the capital it deploys.
If you want to compare Main Street Capital's recent track record with other ideas that focus on quality and valuation, a focused starting point is 42 high quality undervalued stocks
Is Main Street Capital Getting Expensive on Excess Returns?
The Excess Returns model looks at how effectively Main Street Capital turns shareholder equity into earnings above its own funding cost. On these inputs, the framework uses a Book Value of $33.92 per share and a Stable Book Value of $31.65 per share, anchored to the median balance sheet level over the past five years. Stable EPS is set at $3.62 per share, while the Cost of Equity is $2.96 per share, which leaves an Excess Return of $0.66 per share and an Average Return on Equity of 11.43%.
Dividends are a central part of the Main Street Capital story, so the dividend discount work adds useful context. It uses a current dividend of $4.31 per share and an implied long run dividend growth rate of 3.7%, capped from a higher raw estimate, alongside an indicated return on equity of 18.69% and a payout ratio of 55.49%. The December 2026 supplemental dividend and higher monthly payouts into 2027 show management leaning into that income profile, even though the Excess Returns projections put Main Street Capital's estimated intrinsic value substantially below the current share price of $56.82. Find out what Main Street Capital could be worth using our Excess Returns estimate.
The Main Street Capital Narrative: What Would Justify Today's Price?
Narratives pick up where Main Street Capital's valuation gap leaves off by spelling out which specific paths for growth, margins and earnings would need to play out for the current share price to look conservative or stretched. They sit on Simply Wall St's Community page so you can see the reasoning behind each scenario. Rather than a single multiple or model output, each one lays out the key drivers behind its fair value so you can judge those assumptions as fresh results are reported.
One of the top community narratives on Main Street Capital: 6% undervalued
"The main thing that has to go right is that new lower middle market platforms and the expanded private loan and external management businesses keep producing realized gains and fee income large enough to offset higher funding costs and lower dividend income from exited positions..."
Discover why this Narrative puts Main Street Capital at 6% undervalued.
One more angle on Main Street Capital that could change the picture
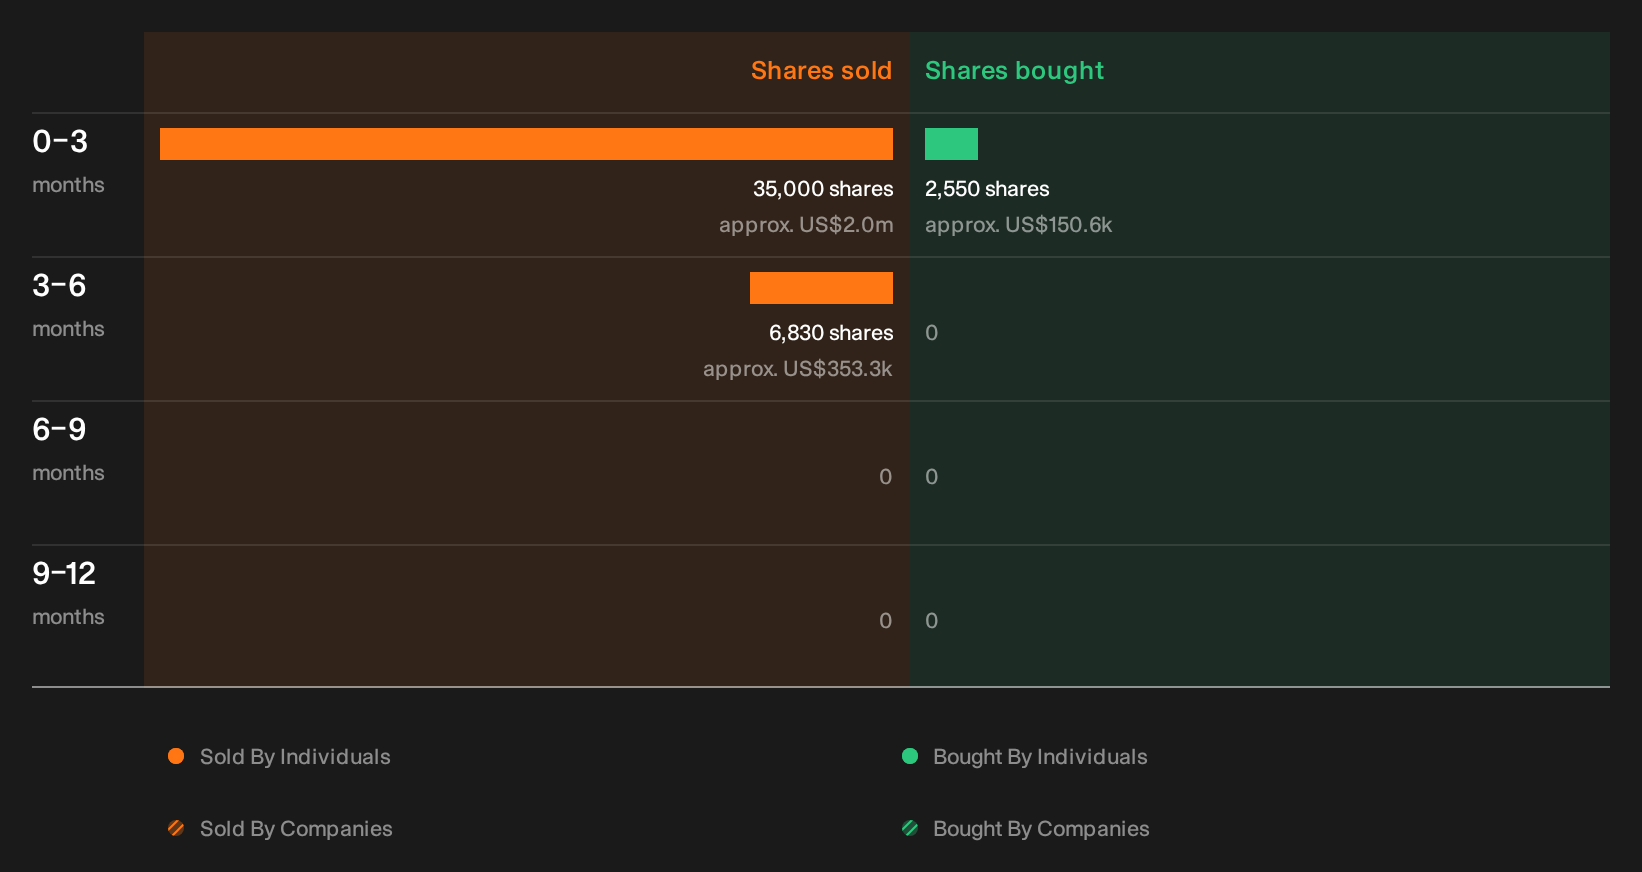
Before forming a view on Main Street Capital, it is worth seeing which insiders have recently been selling, how much stock changed hands, and what that pattern might signal for you. See the recent insider selling flagged for Main Street Capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com