


EN
Do Wall Street Analysts Like EQT Corporation Stock?
EQT Corporation (EQT) is a leading American natural gas producer headquartered in Pittsburgh, Pennsylvania, and one of the largest natural gas companies in the United States. The company carries a market cap of $32.9 billion, and operates an integrated natural gas business spanning upstream production, gathering and transmission, with operations concentrated in the Appalachian Basin, particularly the Marcellus and Utica shale formations across Pennsylvania, West Virginia and Ohio.
Despite its scale, EQT has tanked 9.6% over the past 52 weeks and 5.6% in 2026. Meanwhile, the S&P 500 Index ($SPX) delivered an 8.2% return over the past year and 7.4% rise in this year.
On a closer view, State Street Energy Select Sector SPDR ETF (XLE) has climbed 41% over the past year and 37.8% on a YTD basis, outperforming the stock.
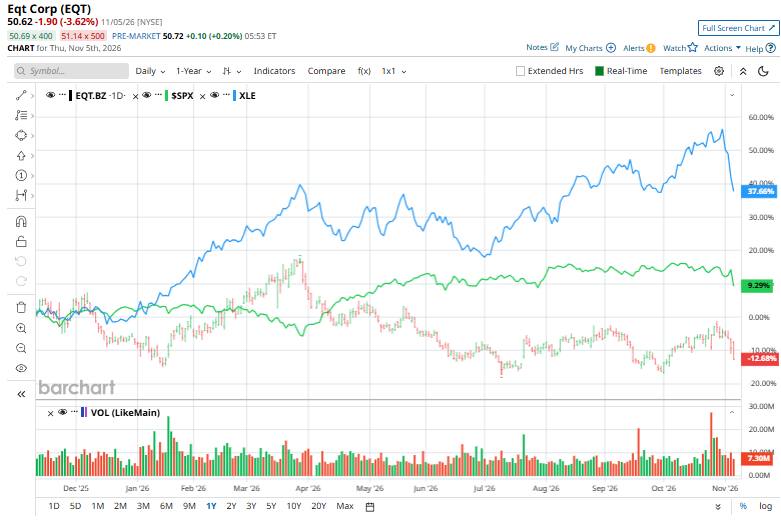
On Oct. 27, EQT announced its FY2026 Q3 earnings results and its shares jumped 2.6%. It reported an adjusted EPS of $0.42, down 19.2% year over year. EQT's total sales volume declined 8.1% to 583 billion cubic feet equivalent (Bcfe) from 634 Bcfe a year earlier.
For FY2026, ending in December, analysts expect diluted EPS of $3.88, representing 27.2% year-over-year growth. EQT Corporation has also topped Wall Street's EPS estimates in three of the past four quarters, while missing on another occasion.
Wall Street remains broadly optimistic despite recent share-price weakness. EQT stock carries an overall "Strong Buy" rating. Among 24 analysts covering the name, 18 assign a "Strong Buy," one recommends a "Moderate Buy," and five suggest investors "Hold."
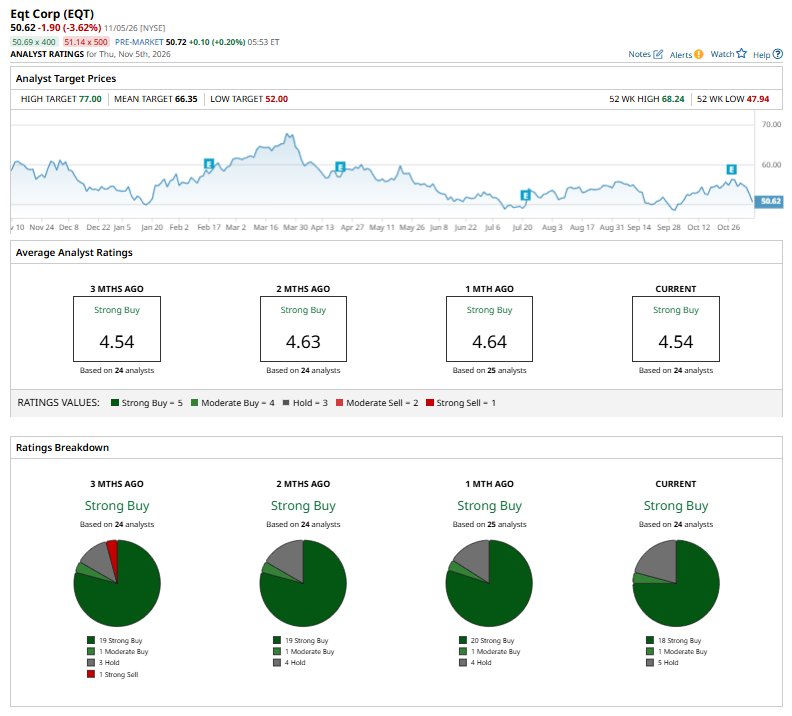
The configuration is more bearish than a month ago, when the stock had 20 “Strong Buy” suggestions.
On Nov. 2, Truist raised its price target on EQT to $70 from $65 while maintaining a “Buy” rating. The firm acknowledged that the proposed acquisition of Range Resources (RRC) could be dilutive and had raised questions among investors, but highlighted its long-term strategic benefits. Truist believes the deal positions EQT to capitalize on structural natural gas demand growth and other favorable industry trends.
Overall, analysts see room for additional upside. The average price target of $66.35 implies potential upside of 31.1%, while the Street-High target of $77 suggests the stock could climb 52.1% from its current levels.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.