


EN
Can CMS Energy (CMS) Justify Its Valuation After Weaker Earnings And A $1b Bond Deal?
Why CMS Energy’s latest earnings and bond deal matter
CMS Energy (CMS) has put two big data points in front of investors. Earnings per share from continuing operations dropped sharply year over year, and the company issued US$1b of long dated, variable rate junior subordinated notes.
Recent trading tells a mixed story. CMS Energy’s share price rose 8.62% over the past month, yet the 90 day share price return was slightly down. A 3 year total shareholder return of 41.88% suggests longer term holders have seen a much stronger payoff than short term traders.
Scan how CMS Energy compares with other utilities that combine balance sheet resilience with earnings power by reviewing the list of solid balance sheet and fundamentals (24 results).
The question now is simple. Does that recent share price bump signal improving confidence in CMS Energy’s long term earnings power, or is it just sentiment reacting to fresh headlines before the valuation work starts?
Most Popular Narrative: 5% Undervalued
On the most followed view, CMS Energy’s fair value sits at $74.69, slightly above the last close of $70.68. This puts recent price moves in the context of a modest valuation gap and a long regulated investment plan backed by analyst forecasts.
The exit from nonutility renewable development and redeployment of roughly $1.7b of planned capital into Michigan rate-base projects is expected to concentrate CMS Energy earnings on regulated assets that typically carry defined returns. This structure could support more predictable EPS and cash flow.
See why 5 investors see CMS Energy as 5% undervalued.
Result: Fair Value of $74.69 (UNDERVALUED)
Still, the narrative around CMS Energy can buckle if Michigan regulators take a tougher line on future rate cases or if severe storms keep driving unrecovered costs higher.
Find out about the key risks to this CMS Energy narrative.
Another View: CMS Energy looks pricey on earnings
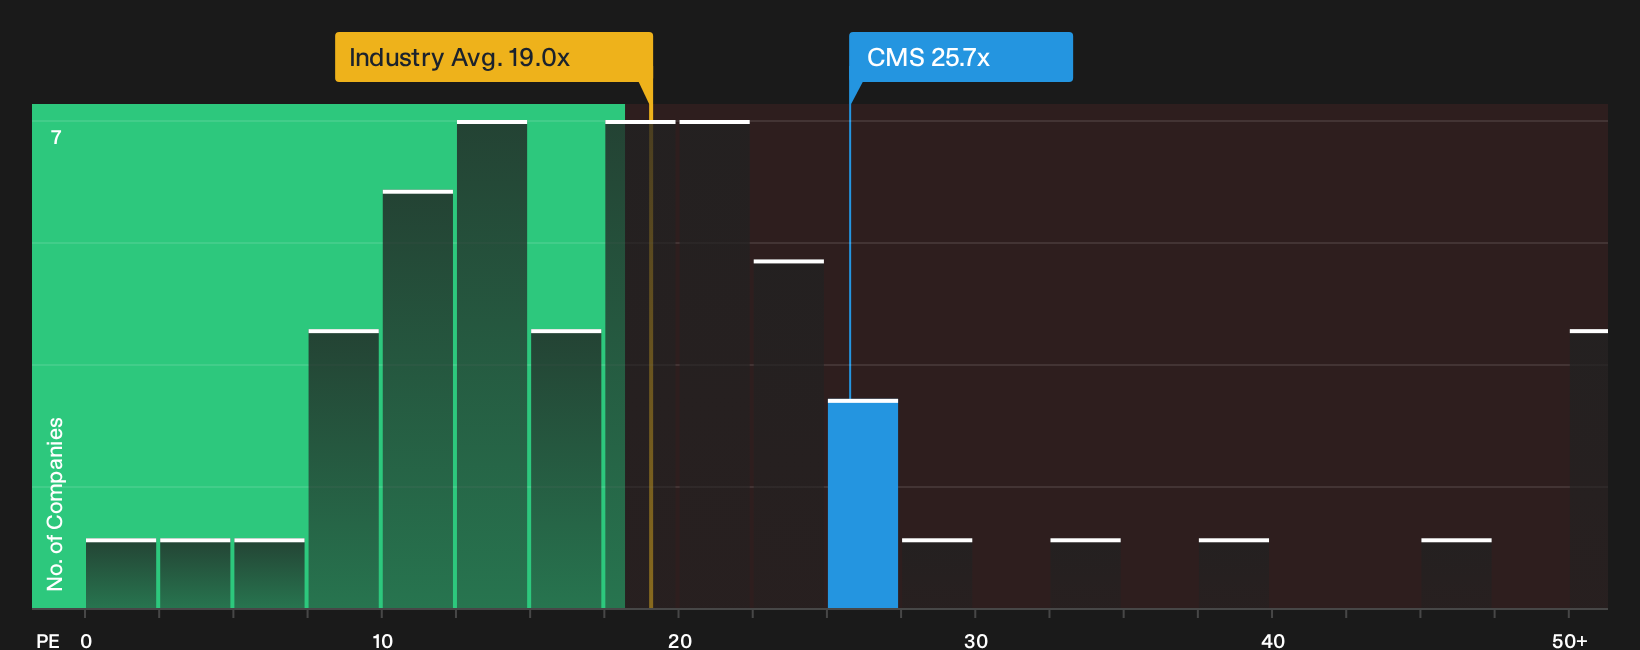
On analyst forecasts and rate base plans, CMS Energy screens modestly undervalued. On simple earnings multiples, the picture is very different. The stock trades on a P/E of 25.7x, compared with 18.8x for the global Integrated Utilities group and 21.7x for peers, and above a fair ratio of 23.1x. That richer multiple can shrink if sentiment cools or earnings slip even slightly. How much valuation stretch are you comfortable holding?
For a closer look at what the earnings multiple implies about upside and downside risk, take a few minutes with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Torn between caution and optimism around CMS Energy? Act quickly, review both sides of the story, and weigh the 1 key reward and 3 important warning signs against your own read of the numbers.
Looking for more investment ideas beyond CMS Energy?
If CMS Energy has your attention, do not stop there. Broaden your watchlist now and give yourself more options before the next round of headlines lands.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) that flags businesses with financial cushions built in.
- Hunt for potential value gaps by reviewing the 42 high quality undervalued stocks that filters companies combining quality metrics with prices that trail their fundamentals.
- Zero in on hidden opportunities by checking the 21 high quality undiscovered gems which highlights financially solid businesses that receive far less attention than larger peers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com