


EN
Did Sterile Filter Launch Just Shift Donaldson Company (DCI) Investment Narrative?
- Donaldson Company recently introduced its Alpha-Pore sterile filtration platform, a new LifeTec offering designed to extend filter service life, sustain flow characteristics, and support sterility for food and beverage processes, while tolerating up to 150 sterilization-in-place cycles.
- The Alpha-Pore design focuses on pore structure and cartridge architecture to balance run time, differential pressure, and contaminant retention, which directly targets customer pain points around changeout frequency, process stability, and operational efficiency in higher value filtration applications.
- Attention now turns to how Donaldson Company's investment narrative could be influenced by Alpha-Pore's push for longer filter run times.
Donaldson Company Investment Narrative Recap
To stay comfortable as a shareholder in Donaldson Company, you need to believe the shift toward higher technology filtration and a large, recurring aftermarket can keep supporting earnings quality even while certain areas remain mixed. Alpha-Pore fits that story, but on its own it does not materially change the short term picture.
The key near term swing factor is still execution in Industrial Solutions and Life Sciences, where Facet integration issues and a slower bioprocessing ramp have been pain points. The biggest risk is that operational inefficiencies and delayed high margin segments persist, which could keep group profitability under pressure despite solid aftermarket exposure.
The Alpha-Pore launch sits closest to the existing Life Sciences catalyst. Management has been leaning into higher purity and process critical filtration for food, beverage and bioprocessing. A sterile platform that targets longer run time and stable differential pressure is directly aligned with that push toward more complex, higher value cartridges.
Alpha-Pore’s focus on validated microbiological retention, consistent flow and up to 150 SIP cycles positions Donaldson Company more firmly in demanding process environments where uptime and filter changeout timing matter. For investors tracking catalysts, the real test will be execution, the pace at which this platform is adopted into recurring consumable spend, and the extent to which that helps offset any prolonged bioprocessing softness.
Donaldson Company Forecasts and Valuation Check
Analysts sketch a future for Donaldson Company where revenue reaches US$4.6b and earnings come in at US$610.5m by 2029, anchored to an assumed 5.9% yearly top line expansion and an earnings increase of roughly US$156.7m from US$453.8m today.
Those projections sit on a few key planks. The forecast assumes revenue expands at 5.9% a year over the next three years and that profit margins lift from 11.7% today to 13.2% by 2029. The earnings bridge runs from US$453.8m now to US$610.5m in that same year, which is a gain of about US$156.7m on current profit. Consensus also bakes in modest share count growth of 0.5% per year, which slightly dilutes per share outcomes even as aggregate earnings rise.
On valuation, the analyst framework ties the 2029 revenue target of US$4.6b and earnings of US$610.5m to a P/E multiple of 24.9x. That required future multiple sits above the 22.6x level cited for Donaldson Company today and slightly ahead of the current US Machinery industry P/E of 24.5x. The gap means the thesis is not only about earnings growth; it also rests on the market being willing to value those future profits at a somewhat richer multiple than the stock and sector carry at the moment.
Price targets reflect those inputs rather than a single clean line of sight. The consensus target sits at US$100.40, with the most optimistic forecast at US$123.00 and the most cautious at US$79.00. Against a recent share price of US$88.65 as of late 2026, that central target is 11.7% higher, which gives you a sense of how much of the expected revenue and earnings trajectory analysts believe is not fully reflected in the current quotation.
Uncover why Donaldson Company's fair value indicates a 21% potential upside to its current price that could narrow quickly.
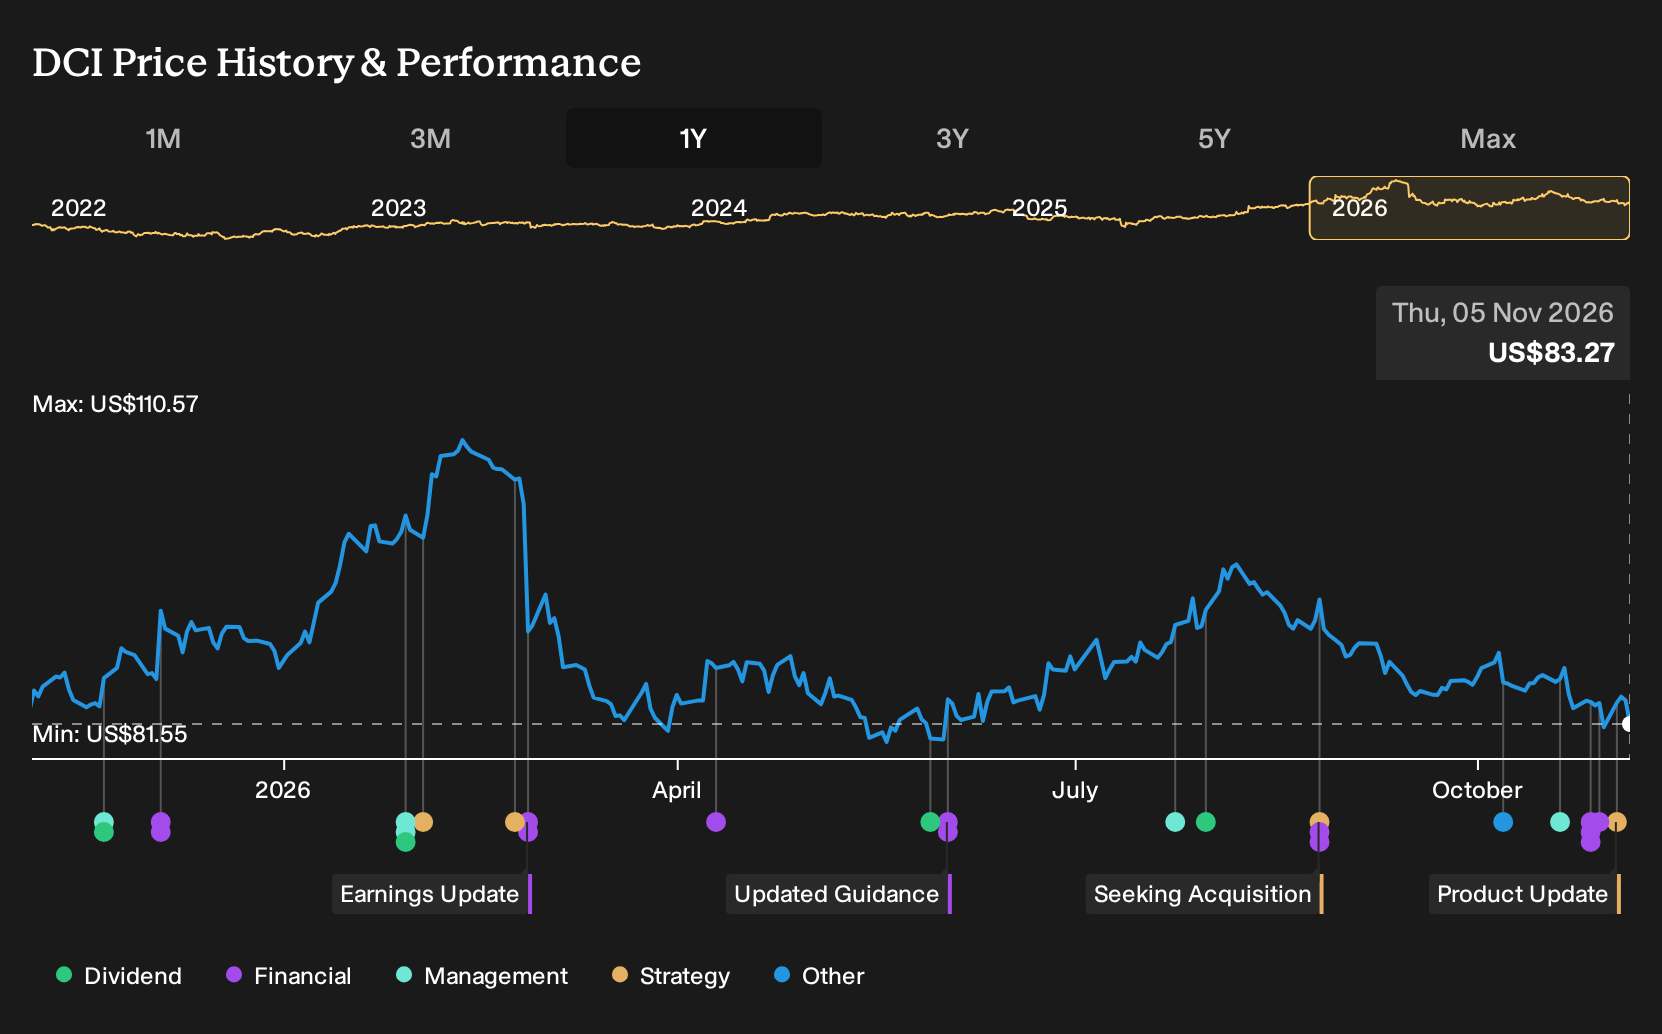
Exploring Other Perspectives
Some of the lowest priced Donaldson Company views focus on capital allocation risk instead of product upside. Those analysts saw 2029 revenue still landing near US$4.6b with earnings of about US$615.9m, yet only assigned a 19.3x P/E and a US$79 target. Your take on Alpha-Pore could nudge that story higher or lower.
Explore 4 other Donaldson Company fair value estimates, including one that suggests there may be as much as 5% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Donaldson Company research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Donaldson Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Donaldson Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Donaldson Company?
If the Donaldson Company story has you thinking about portfolio balance, it can help to compare it with other businesses that share some of the same financial traits or risk profiles.
The Simply Wall St Screener lets you scan wider markets quickly so you can see how Donaldson Company stacks up against peers that match your own risk tolerance and return goals.
- If capital preservation is front of mind, start with companies that show stronger resilience profiles and filter for 32 resilient stocks with low risk scores. These may better align with a steadier ride.
- Investors who want financial strength alongside room for compounding can shortlist firms with healthy balance sheets using the list of solid balance sheet and fundamentals (24 results) to widen the field beyond Donaldson Company.
- For those hunting for mispriced opportunities, build a watchlist anchored on valuation discipline by reviewing the 42 high quality undervalued stocks that fit your preferred mix of quality and price.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com