


EN
StoneCo (STNE) Stock Could Be Trading At A Deep Discount
StoneCo has gone through a steep reset in the market, and the depth of that share price slide raises a straightforward question about whether the current valuation can be explained by its earnings power. After several years of pressure on the stock, investors are now asking what the recent price says about the underlying profitability of the business.
- Over the past 5 years the share price has fallen 68.5%, which puts the focus squarely on whether the earnings multiple now reflects a more cautious outlook for the business.
- The sharp selloff that followed President Lula's re election in Brazil highlights how political shifts can affect expectations for StoneCo's growth, credit risk and funding costs, all of which feed directly into how much investors are willing to pay for its earnings stream.
- There is a second opinion on StoneCo worth weighing. See what analysts think StoneCo's shares could be worth.
The issue now is whether StoneCo's current price can be justified by the earnings it generates today and what investors expect those profits to look like over time.
To see how StoneCo's reset compares with other potential opportunities, line this up against 42 high quality undervalued stocks built on similar value focused criteria.
Is StoneCo Still Cheap on Earnings?
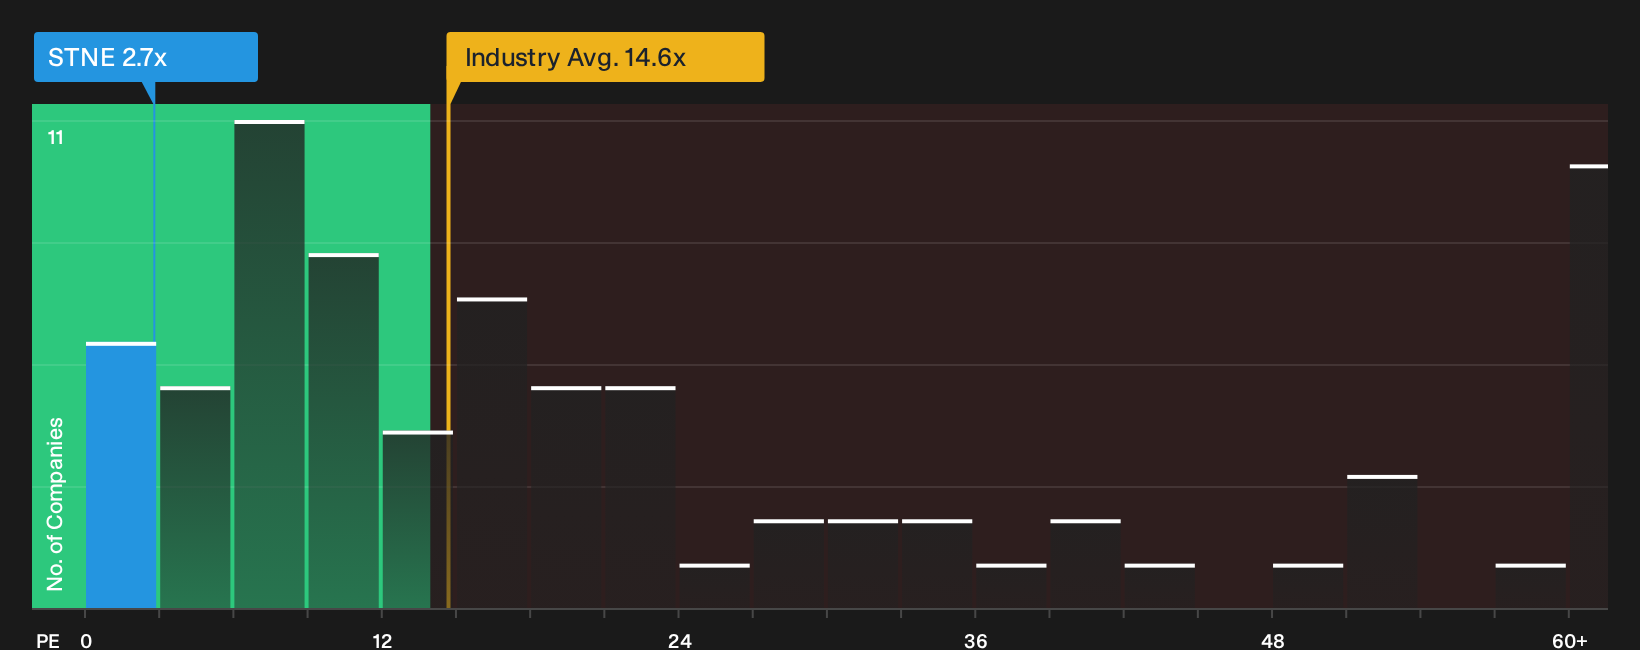
The P/E ratio suits StoneCo because earnings have become the main anchor for how the market prices this payments platform. On this yardstick, the stock trades on a P/E of about 2.7x, which is well below the diversified financial industry average of roughly 14.6x and also far under the broader peer group at about 22.5x.
Using a tailored fair multiple that factors in StoneCo’s forecast profitability, balance sheet intensity and risk profile, the current P/E comes in below what that framework would suggest for the business. Because the share price fell sharply after President Lula’s re election and political risk remains a live discussion for Brazil, this kind of discount on earnings may reflect investors demanding a wide margin of safety before paying up for StoneCo’s profit stream. Explore the numbers behind StoneCo's P/E valuation.
The StoneCo Narrative: What Would Justify Today's Price?
Narratives for StoneCo pick up where the P/E puzzle leaves off and set out which combinations of future growth, profitability and earnings power would need to hold for the stock to be worth meaningfully more or less than it is today on Simply Wall St's Community page. Instead of a single valuation output, they describe the business future that number relies on so you can watch over time whether those assumptions actually play out.
One of the top community narratives on StoneCo: 46% undervalued
"The main thing that has to go right is that StoneCo’s fast-growing credit and banking franchise, funded increasingly by client deposits…"
Discover why this Narrative puts StoneCo at 46% undervalued.
StoneCo's valuation is only part of the story
Price and earnings only tell one side of StoneCo, because the research also flags specific concerns that could change how you weigh everything just read. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com