


EN
Yelp (YELP) Stock Looks Cheap After a 53% Three Year Fall
Yelp has seen its share price move around sharply in recent years, which puts a spotlight on whether the current US$20.52 level is actually supported by the earnings the business produces. For anyone following the stock, the question now is how that price lines up with what the company earns today and is expected to earn over time.
- Over the past 3 years, Yelp shares have fallen 52.9%, which makes the current valuation question far more about the staying power of its earnings than about short term sentiment.
- The business model leans heavily on monetising local business reviews and advertising, so any shift in advertiser budgets or pricing power can reshape the earnings base that underpins the stock.
- The analysts covering Yelp have run their own numbers. See what analysts think Yelp's shares could be worth.
The stock's next move may depend on whether the earnings that Yelp generates today are enough to justify where the share price now sits.
If you are weighing whether Yelp's earnings justify the recent share price swings, it can help to compare it with a broader set of 42 high quality undervalued stocks as another starting point for research.
Is Yelp Still Cheap on Earnings?
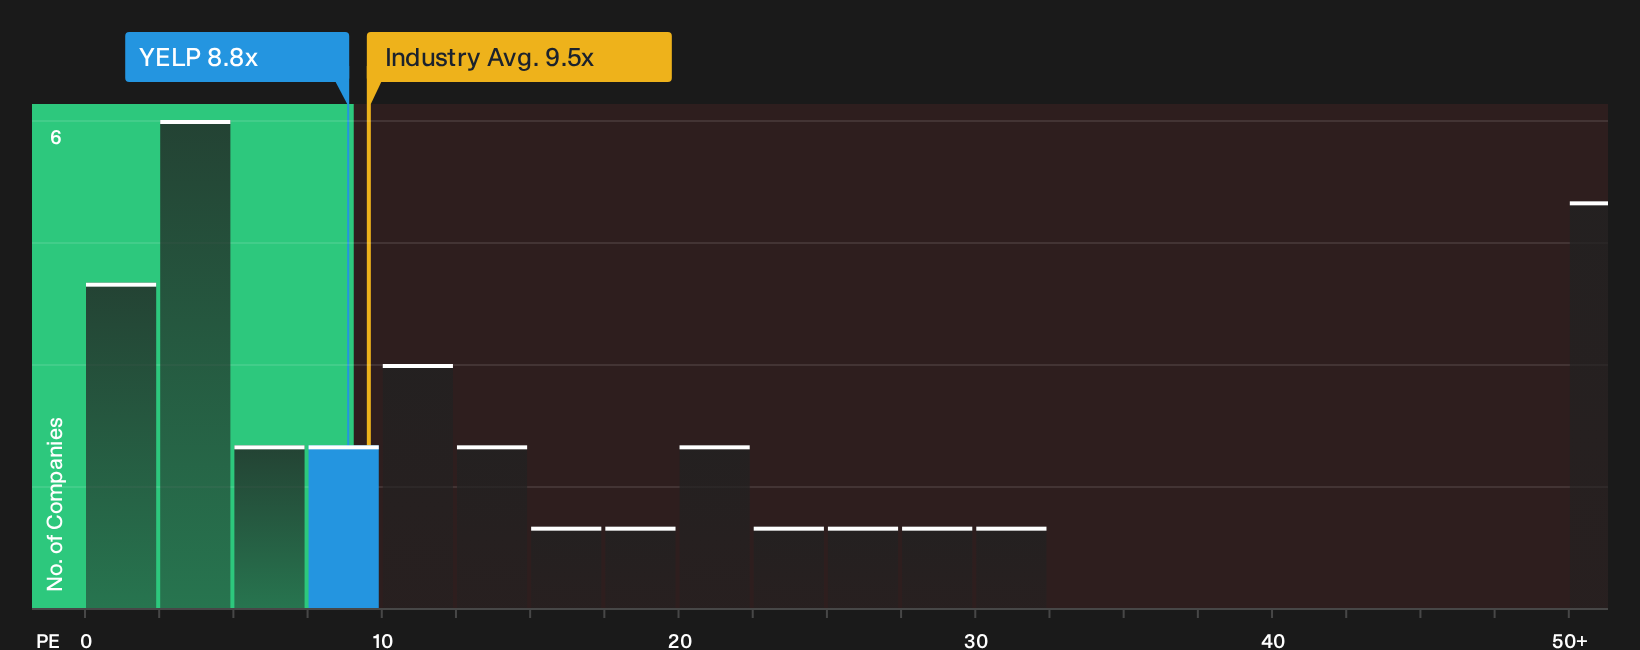
The P/E ratio fits Yelp because earnings still sit at the center of how investors judge the business. At the current price, Yelp trades on a P/E of 8.8x, which is slightly below the Interactive Media and Services industry average of 9.5x and close to a peer group average of 9.2x. That puts the stock on a modest discount to similar platforms that also rely heavily on digital advertising and local commerce spending.
A more tailored fair multiple, which adjusts for factors like Yelp's profitability profile, size and sector risk, points to a higher P/E than where the shares trade today. That gap suggests the market is not paying up for the level of earnings the platform currently generates, so any investor using P/E as a primary yardstick would treat Yelp as undervalued on this measure. Explore the numbers behind Yelp's P/E valuation.
The Yelp Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Yelp leaves off by spelling out which expectations for future growth, margins and earnings would need to hold for the stock to be worth substantially more or less than today’s price. Each one sets out fair value as a thesis about the business that can be tracked over time rather than a one off snapshot, all hosted on the Community page.
The community is split on Yelp, with one camp treating the recent weakness as an opening and the other seeing the AI story as still unproven.
Bull case: 18% undervalued
"Scaling AI driven subscription tools like Yelp Host and Hatch, which together are on tens of millions of dollars of annualized revenue run rate…"
Discover why this Narrative puts Yelp at 18% undervalued.
Bear case: 21% overvalued
"Although Yelp Assistant is contributing to a higher share of Request-a-Quote projects and services projects, there is a risk that this AI-led shift to conversational discovery simply redistributes existing demand…"
Explore why this Narrative puts Yelp at 21% overvalued.
One more check for Yelp before you file this away
Price ratios tell you what the market pays for Yelp today, but the analyst view of where this business might be in a few years offers a separate reference point that can sharpen your own outlook. Explore where analysts expect Yelp to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com