


EN
Sally Beauty Holdings (SBH) Stock Still Looks Like A Bargain After A 124% Run
Sally Beauty Holdings has seen its share price climb in recent years, and that move naturally raises a question about what investors are paying for its earnings today. With the stock changing hands at around US$18.74, the key issue is how that price lines up with what the underlying business is currently earning.
- The share price has returned 124.2% over the past 3 years, which puts real weight on whether the current earnings profile can support that kind of rerating.
- The upcoming November 10 earnings call and related filings may update the market on profit trends and cash generation, which can feed directly into how sustainable today's earnings base looks.
- Your read on Sally Beauty Holdings is one view; the desks covering it have another. See what analysts think Sally Beauty Holdings's shares could be worth.
For investors, the debate is whether Sally Beauty Holdings' recent share price level is justified by the earnings it produces right now.
If you are weighing whether Sally Beauty Holdings' current earnings justify its price, it can help to compare it with a broader group of businesses screened for 42 high quality undervalued stocks.
Does Sally Beauty Holdings Look Undervalued on Earnings?
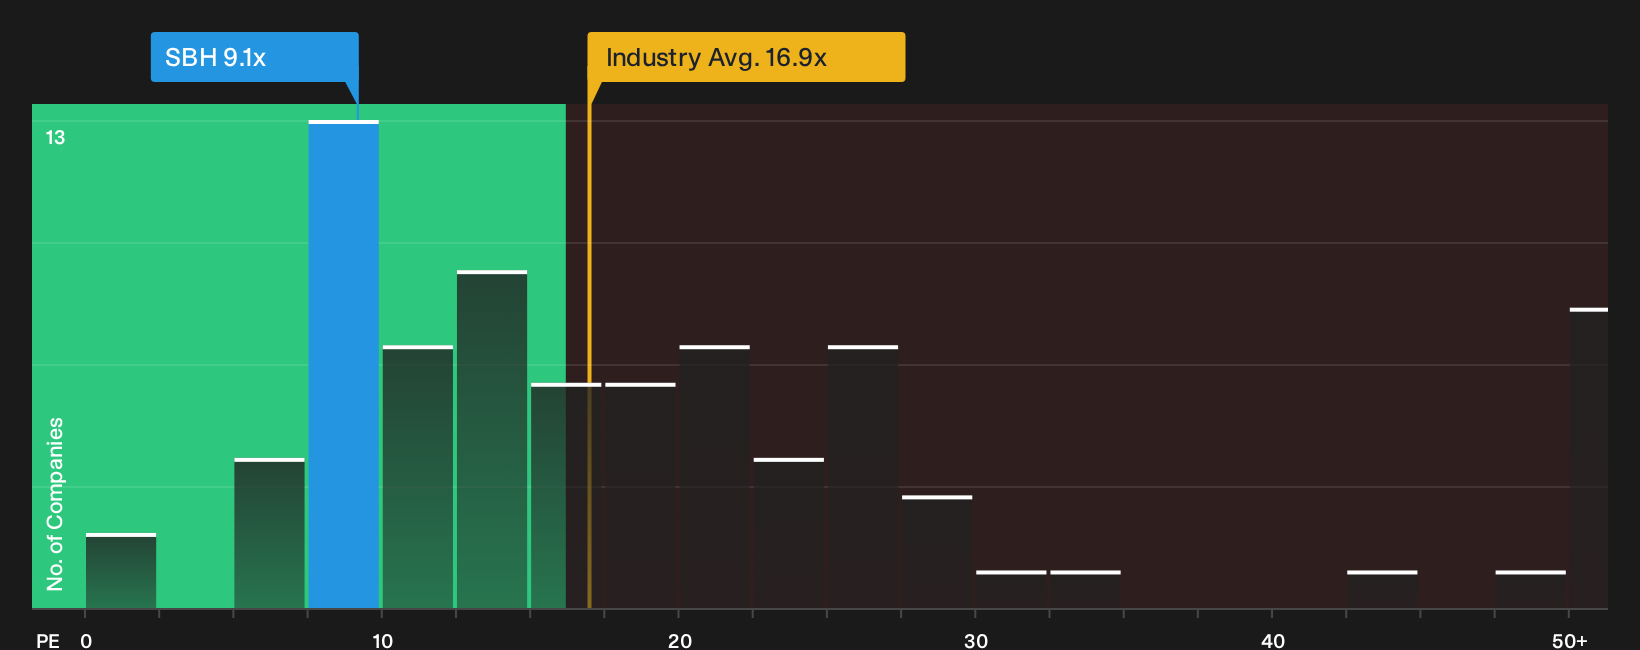
The P/E ratio fits Sally Beauty Holdings well because earnings are a key focus for a mature retailer where profits matter more than narrative. On this basis, the stock trades on roughly 9.1x earnings, compared with about 16.9x for the wider Specialty Retail industry and around 18.7x for peers in the same group.
That gap shows investors are paying less for each dollar of Sally Beauty Holdings' earnings than both the sector and the peer set. The model that blends the company's growth profile, margins, scale and risk suggests a higher P/E would typically be applied. Within this framework, the current multiple screens as undervalued. Because the upcoming November 10 earnings call could refresh views on profit quality and stability, the current discount remains in place ahead of any new information. Explore the numbers behind Sally Beauty Holdings's P/E valuation.
The Sally Beauty Holdings Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for Sally Beauty Holdings, spelling out which combinations of future growth, profitability and earnings power would need to hold for today’s share price to look meaningfully higher or lower. Rather than relying on a single multiple or model line, each scenario lays out the assumptions behind its estimate of fair value in a way you can track against reported results over time. Narratives for Sally Beauty Holdings sit on Simply Wall St's Community page and provide a structured way to test your expectations against different possible paths for the business.
Community views on Sally Beauty Holdings are split between those who see more upside left in the rerating and those who think most of the good news is already in the price.
Bull case: 6% undervalued
"Sally Ignited remodeled stores are outperforming the fleet with higher traffic, dwell time, units per transaction and average ticket…"
Discover why this Narrative puts Sally Beauty Holdings at 6% undervalued.
Bear case: 10% overvalued
"The current valuation and narrative imply that the share price already reflects a fair, bullish view on Sally Beauty Holdings, with meaningful execution risk still attached…"
Explore why this Narrative puts Sally Beauty Holdings at 10% overvalued.
The share price is only one piece of the Sally Beauty Holdings puzzle
Current earnings and multiples tell you what Sally Beauty Holdings looks like today, but analyst views on where the business might be in a few years give you a different yardstick to compare with the current tag. Explore where analysts expect Sally Beauty Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com