


EN
Is SSR Mining (TSX:SSRM) Reasonable After Cost Warnings And Buybacks?
SSR Mining has delivered a powerful multi year return, yet after a recent pullback and fresh corporate moves, the real question for investors is whether the current share price lines up with what its earnings can justify.
- SSR Mining has returned 143.0% over the past 3 years, which puts a lot of weight on whether its profit power supports that kind of share price outcome.
- Heavy share buybacks, asset sales and new project commitments may shift the timing and durability of future earnings, which directly affects how you might think about what today's price implies.
- There is a second opinion on SSR Mining worth weighing. See what analysts think SSR Mining's shares could be worth.
The issue now is whether SSR Mining's present valuation can be explained by the earnings it is currently generating and what those profits reasonably point to over time.
If you are weighing whether SSR Mining's recent pullback lines up with its earnings power, it can help to compare it with a wider set of producers that have a clear production focus, as screened through the 33 elite gold producer stocks
Is SSR Mining Still Cheap on Earnings?
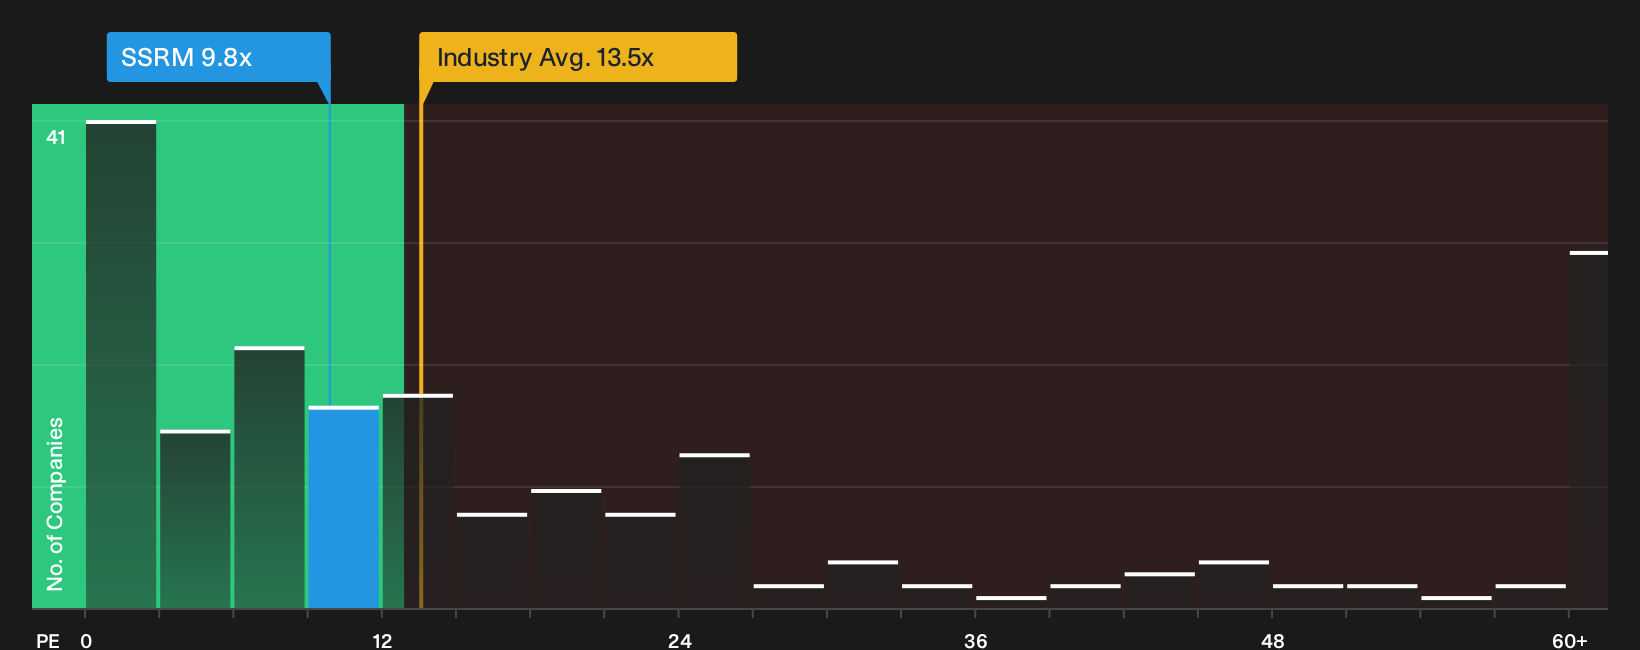
The P/E ratio is a useful tool for assessing SSR Mining, as earnings are a key reference point for investors considering its recent corporate reshuffle and asset sales. On this metric, the stock trades on a P/E of about 9.8x, which is below both the Metals and Mining industry average of roughly 13.5x and the peer group on about 11.2x. Using a tailored fair multiple that reflects SSR Mining's own margin profile, risk mix and scale, the current P/E appears on the low side rather than at a premium.
Because the Çöpler sale left SSR Mining with about US$1.55b of cash and no short term debt, yet the P/E still trails sector norms, the market appears to be applying a cautious earnings multiple despite that balance sheet position. For you as a shareholder or potential buyer, the key task is to judge whether the recent cost warning and mine reshuffling justify that discount or whether the present P/E implies more earnings risk than the latest results indicate. Explore the numbers behind SSR Mining's P/E valuation.
The SSR Mining Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for SSR Mining pick up where the P/E puzzle leaves off and explain which combinations of future growth, margins, and earnings would need to occur for the stock to be worth materially more or less than it is today on the market. Each narrative links its figure to a specific view on how SSR Mining's profitability, cash generation, and risk profile could change, providing a reference point to revisit as new information becomes available.
One of the top community narratives on SSR Mining: 42% undervalued
"The current valuation implies the market discounts SSR Mining’s enlarged reserve base at Marigold and potential extra ounces from Converse..."
Discover why this Narrative puts SSR Mining at 42% undervalued.
One more SSR Mining check that belongs next to the P/E
Before calling your work on SSR Mining finished, it helps to see how professional analysts map out this business a few years from now and weigh that side by side with the current valuation. Explore where analysts expect SSR Mining to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com