


EN
Is ScanSource (SCSC) Still Below Fair Value On Cash Flow?
ScanSource shares have fallen sharply in recent weeks after a solid multi‑year run. This puts fresh attention on whether the current price lines up with the cash the business is expected to generate. With the stock now around US$45.07, the key issue is how that market quote compares with what its cash flows may be worth on a discounted basis.
- The share price is up about 57.4% over the past 3 years, so a lot of prior optimism about ScanSource's future cash generation is already embedded in the recent history.
- The company relies on converting its distribution and technology service operations into steady free cash flow. This can influence how sensitive any intrinsic value estimate is to assumptions about growth, margins and reinvestment needs.
- Prefer to judge ScanSource on earnings? See what ScanSource's 11.5x P/E says about the price.
For investors, the debate is whether ScanSource's recent share price, after both the multi‑year gain and short term pullback, is adequately supported by the cash flows implied in a Discounted Cash Flow (DCF) intrinsic value estimate.
If you want to stress test this same cash flow question beyond ScanSource, compare it with a broader set of 42 high quality undervalued stocks.
Does ScanSource Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) method looks at the cash ScanSource can generate for shareholders and discounts it back to today. ScanSource has produced about $114.3m of free cash flow over the last twelve months, and the model assumes that future cash generation grows gradually rather than swinging sharply up or down.
Projected free cash flows through the next decade sit in a fairly tight range, which fits a business that already produces meaningful cash rather than one being rebuilt from scratch. On those inputs, the DCF outcome sits substantially above the current share price of $45.07, so the model implies the market is valuing ScanSource at a discount to the cash flows being projected. Find out what ScanSource could be worth using our Discounted Cash Flow (DCF) estimate.
The ScanSource Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the ScanSource valuation puzzle leaves off by spelling out which expectations for growth, profitability and earnings would need to hold for the share price to sit materially above or below where it trades today on the Community page. Each Narrative ties a specific fair value view to a clear storyline about ScanSource's possible catalysts and key risks, so you can track over time which version of events seems to align with reality.
One of the top community narratives on ScanSource: 30% undervalued
"The acquisition of MicroAge brings capabilities in cloud, cybersecurity, data center and AI services such as cloud migration…"
Discover why this Narrative puts ScanSource at 30% undervalued.
ScanSource’s price is only one clue, insider actions are another
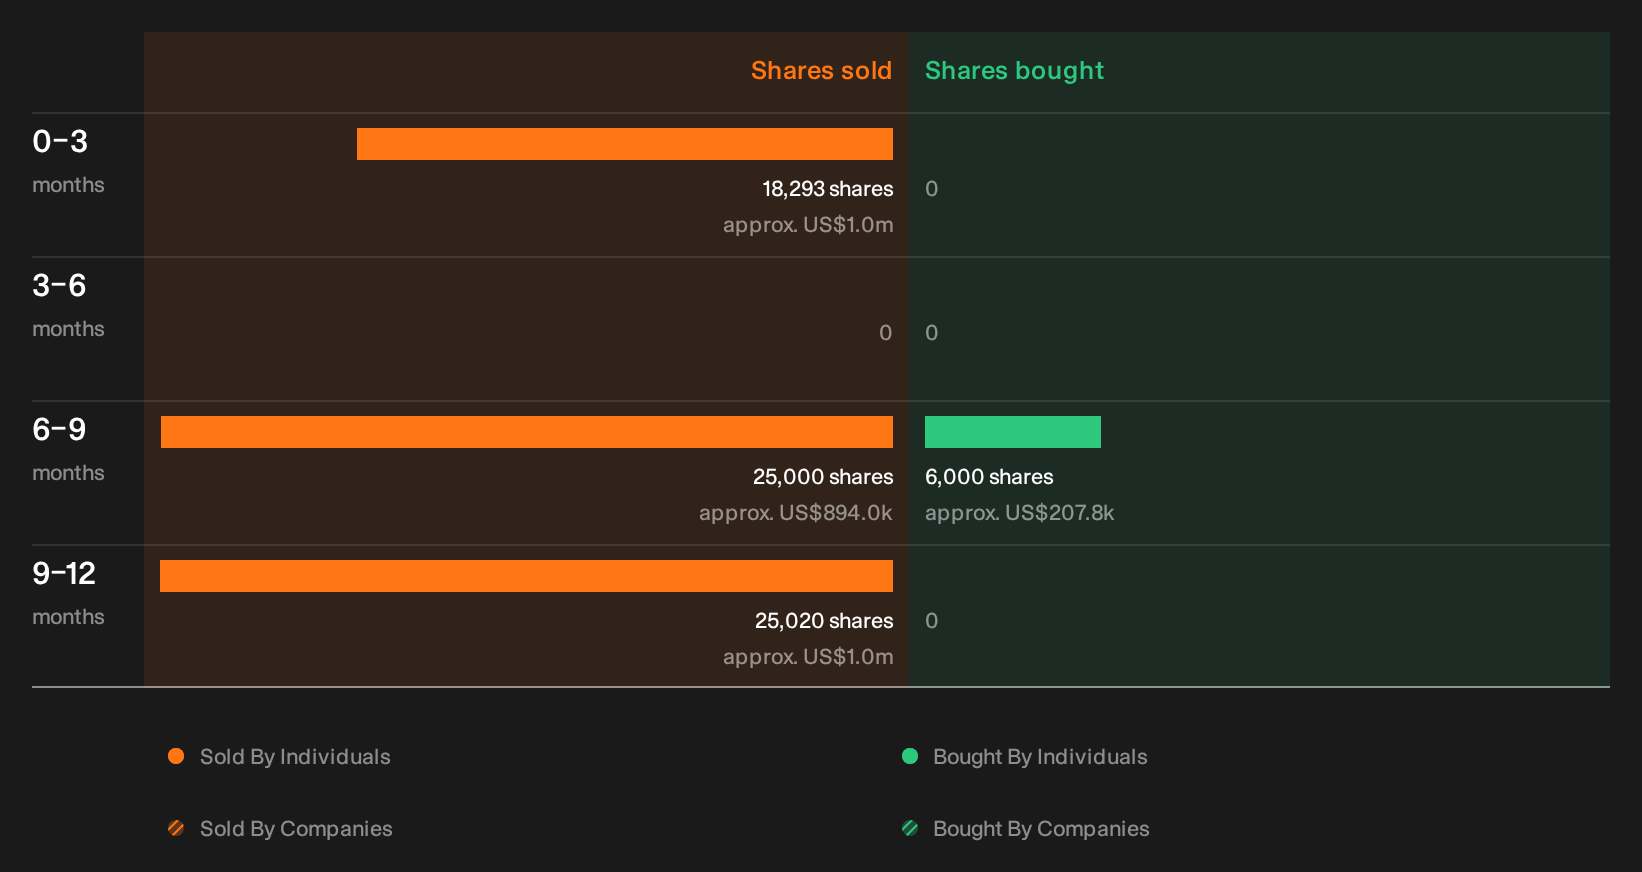
Valuation models tell you what the cash flows might justify, but our checks also flag recent insider share sales. The specific people involved, sizes and possible takeaways are for you to review. See the recent insider selling flagged for ScanSource.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com