


EN
Vericel Stock Gains Focus After Return To Nine Month Profit
- Vericel reported third quarter 2026 revenue of US$85.37 million and net income of US$14.16 million, with basic EPS from continuing operations of US$0.28, alongside nine month revenue of US$231.25 million and net income of US$10.07 million.
- The nine month period shifted from a loss a year earlier to a profit, which signals progress in Vericel's cost discipline and operating efficiency across its cartilage repair and burn care franchises.
- We will now look at how Vericel's profitability and nine month return to net income shape the broader investment narrative.
See how Vericel's improving profitability compares with peers by reviewing a curated shortlist of 21 high quality undiscovered gems that are also turning stronger fundamentals into fresh momentum.
Vericel Investment Narrative Recap
To own Vericel, you need to buy into a focused cell therapy story that leans heavily on MACI, Epicel and NexoBrid while the Burlington facility and bigger MACI sales team are absorbed. The latest quarter puts more weight behind that thesis because the business is now profitable over nine months, which helps fund MACI Ankle work and ex U.S. preparation.
The near term catalyst still centers on MACI utilization and surgeon adoption, helped by that sales expansion and broader procedure coverage. The biggest risk remains the concentrated product mix and fixed cost load. If demand for MACI or burn care softens against those higher expenses, earnings could come under pressure.
The earnings release for the third quarter and nine months to 30 September 2026 is the key event here. Vericel reported quarterly revenue of US$85.37 million with net income of US$14.16 million and basic EPS from continuing operations of US$0.28. Over nine months, the firm recorded US$231.25 million in revenue and a move from loss to profit.
That shift to nine month profitability matters for the transition year story. It gives Vericel more room to absorb Burlington manufacturing costs, MACI sales force expansion and MACI Ankle trial spending without relying solely on external funding. It also tests the risk that a concentrated product set and volatile Epicel volumes could strain margins if procedure trends weaken.
Vericel's current analyst narrative points to revenue of US$490.4 million and earnings of US$86.3 million by 2029, built on a projected 17.0% yearly revenue growth rate and an earnings increase of about 3.6x from US$24.2 million today.
Uncover why Vericel's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
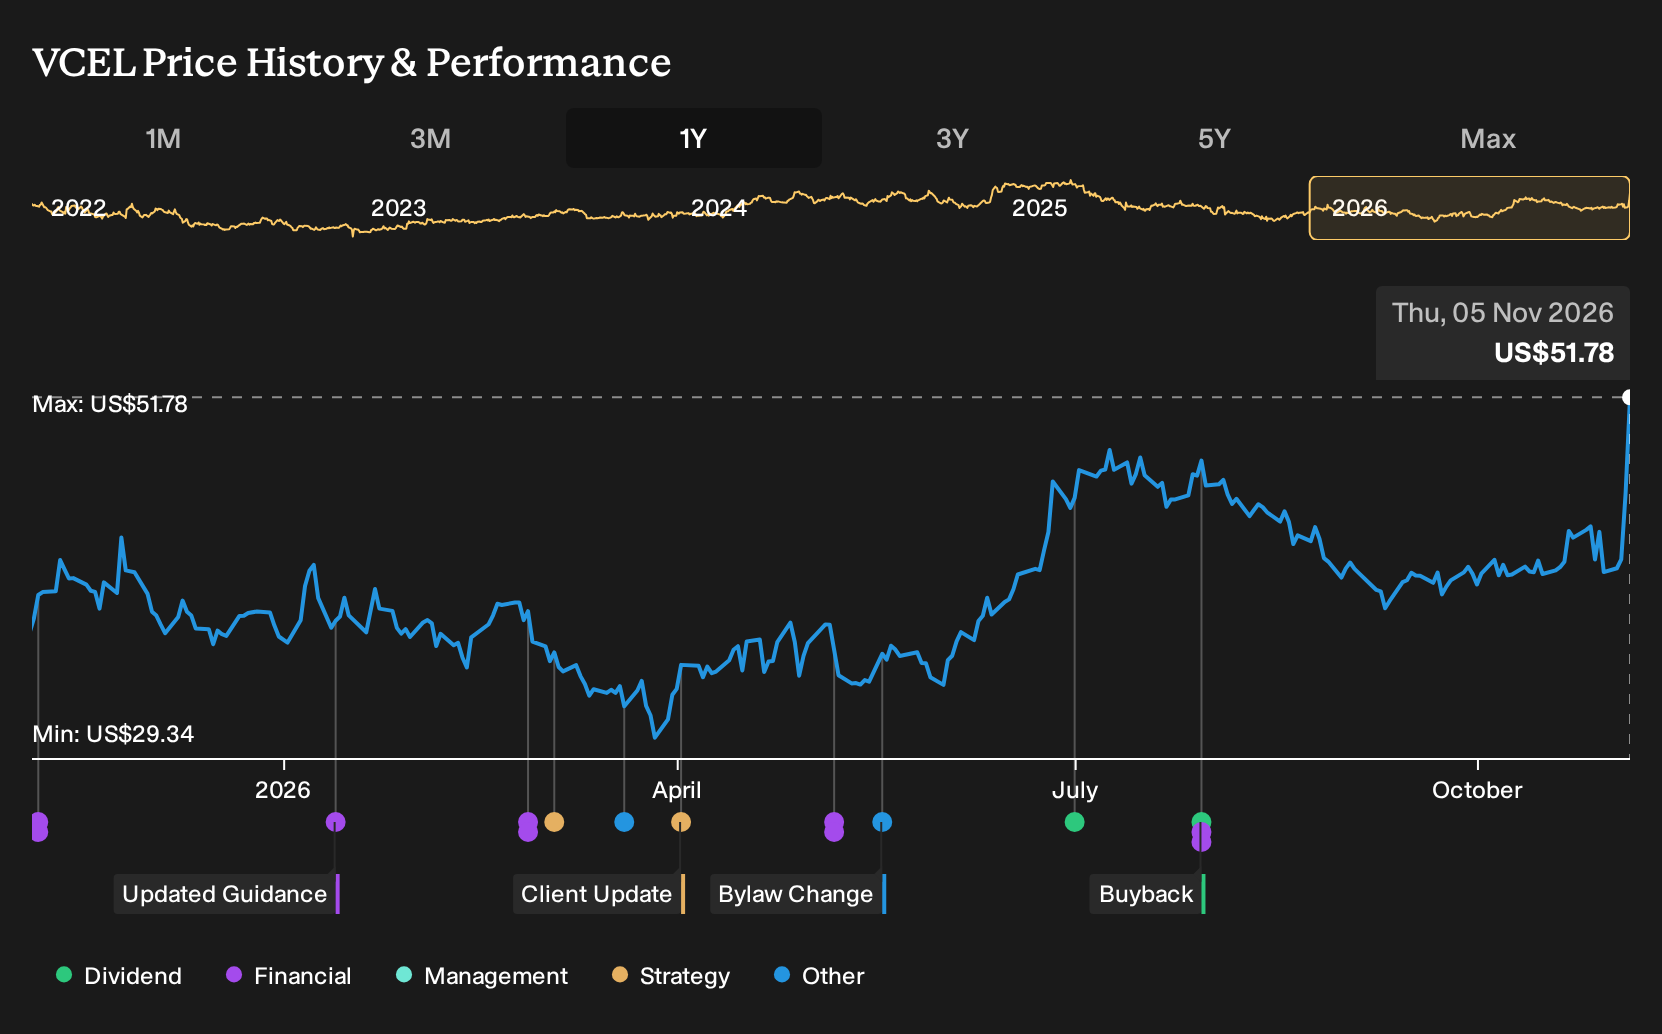
Exploring Other Perspectives
Some of the most optimistic analysts focus on MACI pricing as a key swing factor for Vericel. Before this earnings release, the bullish camp was modeling about US$516.5 million of revenue and US$110.5 million of earnings by 2029. You can use this stronger pricing narrative as a counterpoint and explore how opinions might shift after these results.
Explore 2 other Vericel fair value estimates, including one that indicates up to 17% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vericel research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Vericel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vericel's overall financial health at a glance.
Looking for more investment ideas beyond Vericel?
Once you have a view on Vericel, it can help to put that thesis in context by comparing it with other companies that share similar qualities in cash generation, balance sheet strength or income potential. The Simply Wall St Screener is built for exactly that kind of side by side work.
- For investors who care most about quality at a sensible price, you can filter for companies with stronger fundamentals using the 42 high quality undervalued stocks.
- If capital preservation and steadier business profiles matter more to you than rapid growth, you can narrow the field with a 32 resilient stocks with low risk scores.
- For readers focused on steady cash returns, you can concentrate on income opportunities through a 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com