


EN
Apple Hospitality REIT (APLE) Looks Fully Valued After Third Quarter Earnings
Apple Hospitality REIT (APLE) just released third quarter 2026 results, reporting revenue of US$398.33 million and net income of US$60.47 million, resulting in basic earnings per share from continuing operations of US$0.26.
Apple Hospitality REIT’s latest report lands after a strong run, with a year to date share price return of 50.5% and a 1 year total shareholder return of 72.78%. However, the stock pulled back 3.56% on the day of the release and is now at US$18.15, hinting that recent gains and the 12.18% 3 month share price return are being reassessed as investors weigh how much of the earnings story is already reflected in the current valuation.
Scan how Apple Hospitality REIT stacks up against other income focused real estate plays by reviewing a hand picked set of 6 dividend fortresses.
Bulls point to Apple Hospitality REIT’s rising earnings and income focus. Bears focus on the sharp run up and recent pullback. Which side does the current valuation support next?
Most Popular Narrative: 6% Overvalued
On Simply Wall St's most followed narrative, Apple Hospitality REIT carries a fair value of $17.17 against the latest close of $18.15. This points to a stock already pricing in a solid operational story rather than a bargain setup.
The current valuation, along with evidence of resilient RevPAR, margin expansion, regular monthly cash distributions near a mid single digit yield and improving external views on Apple Hospitality REIT’s earnings outlook, suggests the share price already reflects a fairly valued, bullish narrative that assumes continued execution rather than a deep discount.
See why 49 investors see Apple Hospitality REIT as 6% overvalued.
Result: Fair Value of $17.17 (OVERVALUED)
Still, the thesis around Apple Hospitality REIT can be shaken if renovation disruptions at key hotels drag on or if weaker demand in markets like Phoenix lingers longer than expected.
Find out about the key risks to this Apple Hospitality REIT narrative.
Another View: Cash Flows Send A Different Signal
There is a twist once the focus shifts from analyst targets to the SWS DCF model. While the narrative fair value sits at $17.17 and frames Apple Hospitality REIT as about 6% overvalued, the cash flow based estimate lands at $33.54, which points to a very different story about upside versus risk.
For readers who want to see exactly how that gap is built from future cash flows, discount rates and scenario work, Look into how the SWS DCF model arrives at its fair value.
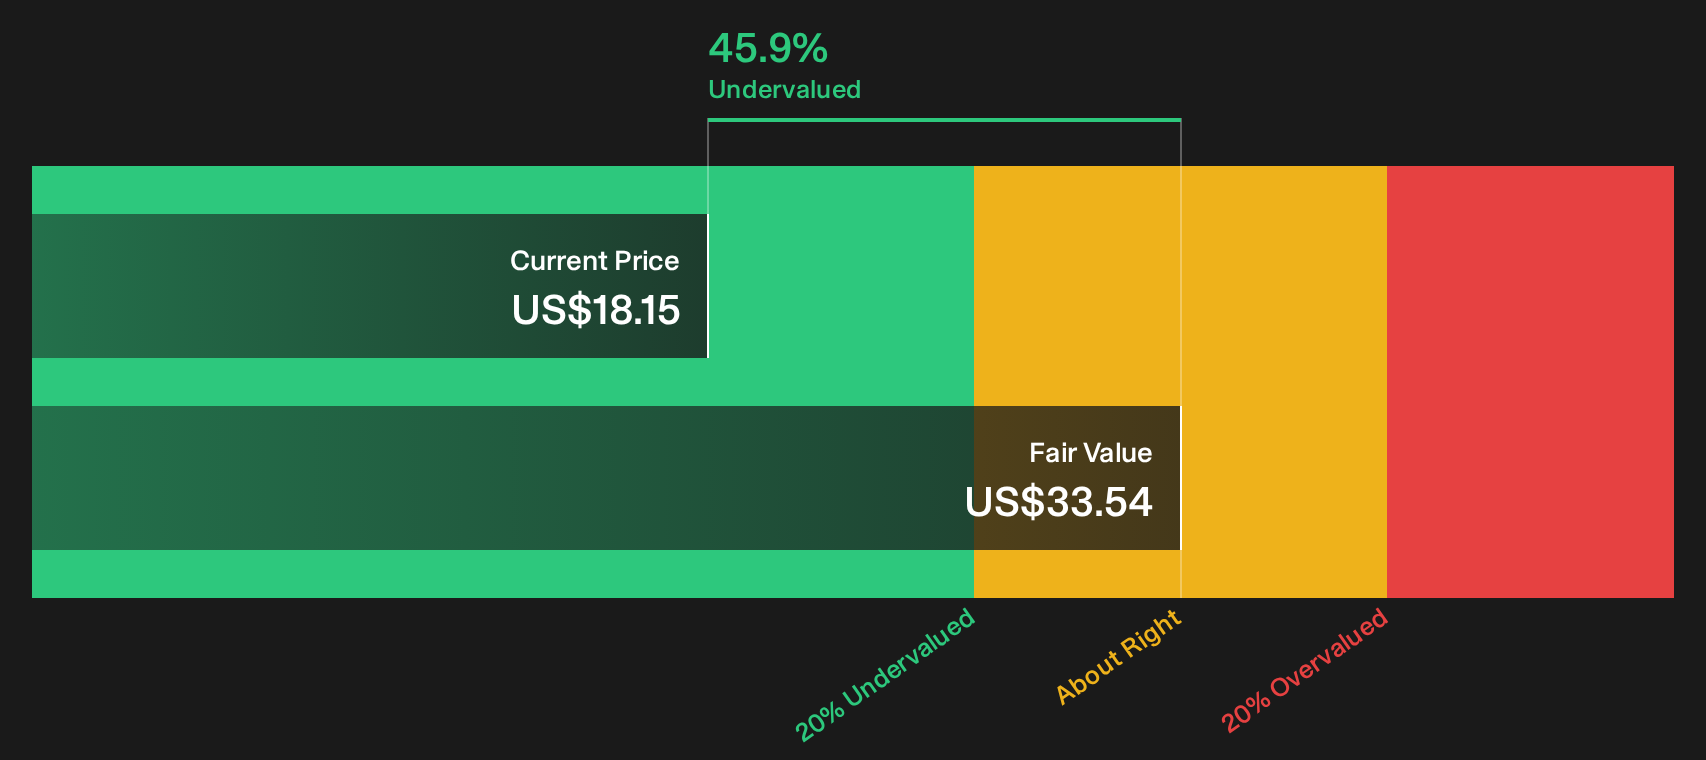
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Apple Hospitality REIT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear message? With Apple Hospitality REIT showing both flagged risks and clear upside drivers, move quickly to stress test the 1 key reward and 2 important warning signs.
Looking for more ideas beyond Apple Hospitality REIT?
If you stop with Apple Hospitality REIT, you could miss other opportunities that fit your style. Let the data do the heavy lifting for your next move.
- Target resilient income with staying power by scanning a hand picked set of 6 dividend fortresses.
- Hunt for quality at a discount by running through a focused group of 42 high quality undervalued stocks.
- Prioritise sturdier fundamentals and balance sheet strength by reviewing a curated list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com