


EN
How Investors May Respond To ACI Worldwide Stock As EBITDA Outlook Rises
- ACI Worldwide reported third quarter 2026 results with revenue of US$426.81 million and net income of US$32.53 million, while new annual recurring revenue bookings rose 86% and full year adjusted EBITDA guidance was raised.
- The firm paired higher adjusted EBITDA expectations with the first customer going live on its ACI Connetic cloud payments platform and the acquisition of Cranium Ventures to support its card payments roadmap.
- This article examines how ACI Worldwide's investment narrative is affected by the raised adjusted EBITDA outlook and recurring revenue momentum.
Scan how ACI Worldwide’s raised EBITDA outlook and recurring revenue focus compares with other payment and fintech players by reviewing our hand picked 42 high quality undervalued stocks in similar spaces.
ACI Worldwide Investment Narrative Recap
To own ACI Worldwide, you need to be comfortable with a payments software business that is leaning harder into recurring cloud and real time payment revenue, while still living with lumpy license timing. The raised adjusted EBITDA outlook and stronger new ARR bookings support that subscription heavy direction. The key shorter term catalyst remains clean execution on Connetic and Speedpay One deployments so those contracted wins actually turn into usage and margin.
The main operational risk right now sits in earnings volatility and competitive pressure. Quarterly results already show that license timing and segment specific items can move net income, as seen in third quarter revenue of US$426.81 million and net income of US$32.53 million compared with higher figures a year earlier. If large banks or billers shift volume to rivals or alternative networks faster than expected, that could weaken both recurring revenue momentum and the EBITDA trajectory management is targeting.
The raised full year 2026 adjusted EBITDA guidance after the third quarter update is the announcement that ties most directly to the current ACI Worldwide story. Management kept revenue guidance while lifting profitability expectations. That points to cost discipline and mix benefits from ARR, even as reported nine month net income of US$102.63 million sits below the prior year’s US$162.32 million. For you, the focus is how much of that EBITDA uplift is tied to timing of license renewals versus genuinely improving unit economics in cloud products.
That guidance change also interacts directly with the biggest catalysts. You have Connetic’s early customer go live, real time payments contracts, Speedpay One expansion and the Cranium Ventures acquisition all feeding into a model that analysts already describe as more recurring and asset light. The risk is clear execution slippage. If implementations run long, migrations stall or integration of acquired technology proves more complex than expected, then the higher EBITDA outlook could meet pressure just as competition and regulatory changes keep testing ACI Worldwide’s relevance in critical payment flows.
ACI Worldwide's current analyst narrative points to revenues of US$2.3b and earnings of US$382.2 million by 2029, based on an assumed 8.2% yearly revenue growth rate and an earnings increase of about US$156.5 million from US$225.7 million today.
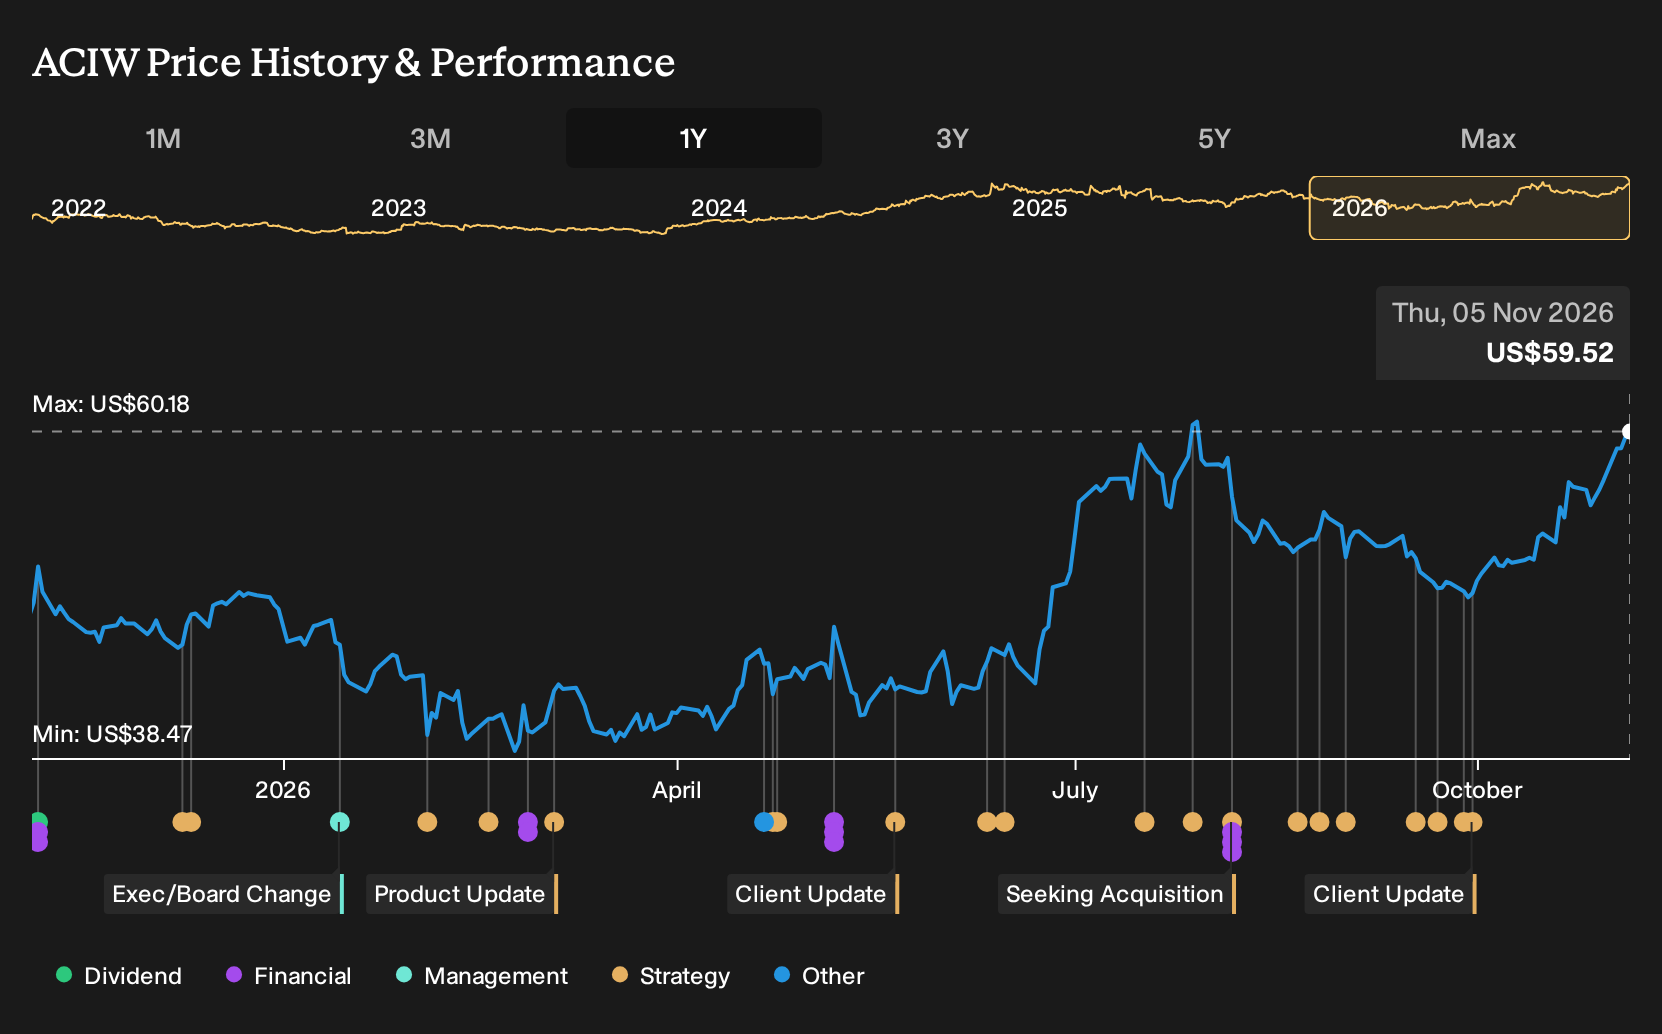
Uncover why ACI Worldwide's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The lowest ACI Worldwide analysts focus on Connetic execution risk. They worry that integrating deals like Cranium Ventures could slow customer go lives, so the raised EBITDA outlook might prove harder to sustain. Before this earnings news, they were modeling about US$2.3b of revenue and US$376.6 million of earnings by 2029. That is only slightly below consensus, yet it supports a much more cautious story. Use that spread in expectations as a reminder that reasonable people can view the same data very differently and consider exploring both sets of forecasts as new results land.
Explore 4 other ACI Worldwide fair value estimates, including one that suggests as much as 24% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ACI Worldwide research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ACI Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ACI Worldwide's overall financial health at a glance.
Looking For More Investment Ideas Beyond ACI Worldwide?
If ACI Worldwide has sharpened your thinking about payment software and recurring revenue, you may wish to use that momentum to widen your watchlist. The Simply Wall St Screener can help you sift through hundreds of other businesses quickly so you can spot opportunities that fit your risk profile and income goals.
- If you are hunting for steady balance sheets and cleaner fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that can handle stress without stretching finances.
- For investors who care most about resilient business profiles, filter by lower risk scores and use the 32 resilient stocks with low risk scores as a short list to investigate further.
- If you want ideas that the market may not be fully focused on yet, broaden your research with a 21 high quality undiscovered gems that still shows strong underlying data.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com