


EN
Earnings Beat May Strengthen The Case For NetScout Systems Stock
- NetScout Systems reported fiscal Q2 2027 revenue of US$222.19 million and net income of US$34.38 million, with basic EPS from continuing operations of US$0.48, and reaffirmed its full year outlook alongside continued share repurchases.
- The business is leaning into AI ready Smart Data and cybersecurity offerings, while renaming its Service Assurance segment to Network Observability to align products with how customers now think about monitoring and protecting complex networks.
- We will now see how NetScout Systems' reaffirmed full year guidance shapes the investment narrative investors already had in mind.
NetScout Systems Investment Narrative Recap
For NetScout Systems, the core belief is that demand for network observability and cybersecurity, including AI ready Smart Data, can support a steady earnings profile even as IT architectures change. The latest quarter, with US$222.19 million in revenue and US$34.38 million in net income, broadly backs up a thesis centered on execution rather than big swings.
The key near term catalyst is whether management can keep converting that product focus into consistent operating margin progress while holding its reaffirmed full year outlook. The largest current risk sits in the shift toward cloud native and more consolidated IT stacks, which could pressure older offerings if customers rationalize tools faster than NetScout Systems adapts.
The reaffirmed full year outlook, paired with ongoing stock repurchases of about US$77 million in the recent period, is the announcement that ties closest to this earnings print. It signals that management is running the business with cost discipline in mind while still returning capital, which matters if you are watching near term earnings quality.
That same capital return program also raises the bar for execution. To keep both buybacks and product investment viable, NetScout Systems needs continued traction in AI driven observability and DDoS protection, along with enough large enterprise and government deals to offset any pressure in legacy segments. Your own view on that execution risk will likely drive how you interpret this quarter.
NetScout Systems' current analyst narrative points to forecast revenue of US$954.2 million and projected earnings of US$122.2 million by 2029, based on an assumed 3.5% yearly revenue growth rate. That outlook compares with earnings today of US$95.5 million, implying an earnings increase of about US$26.7 million from current levels.
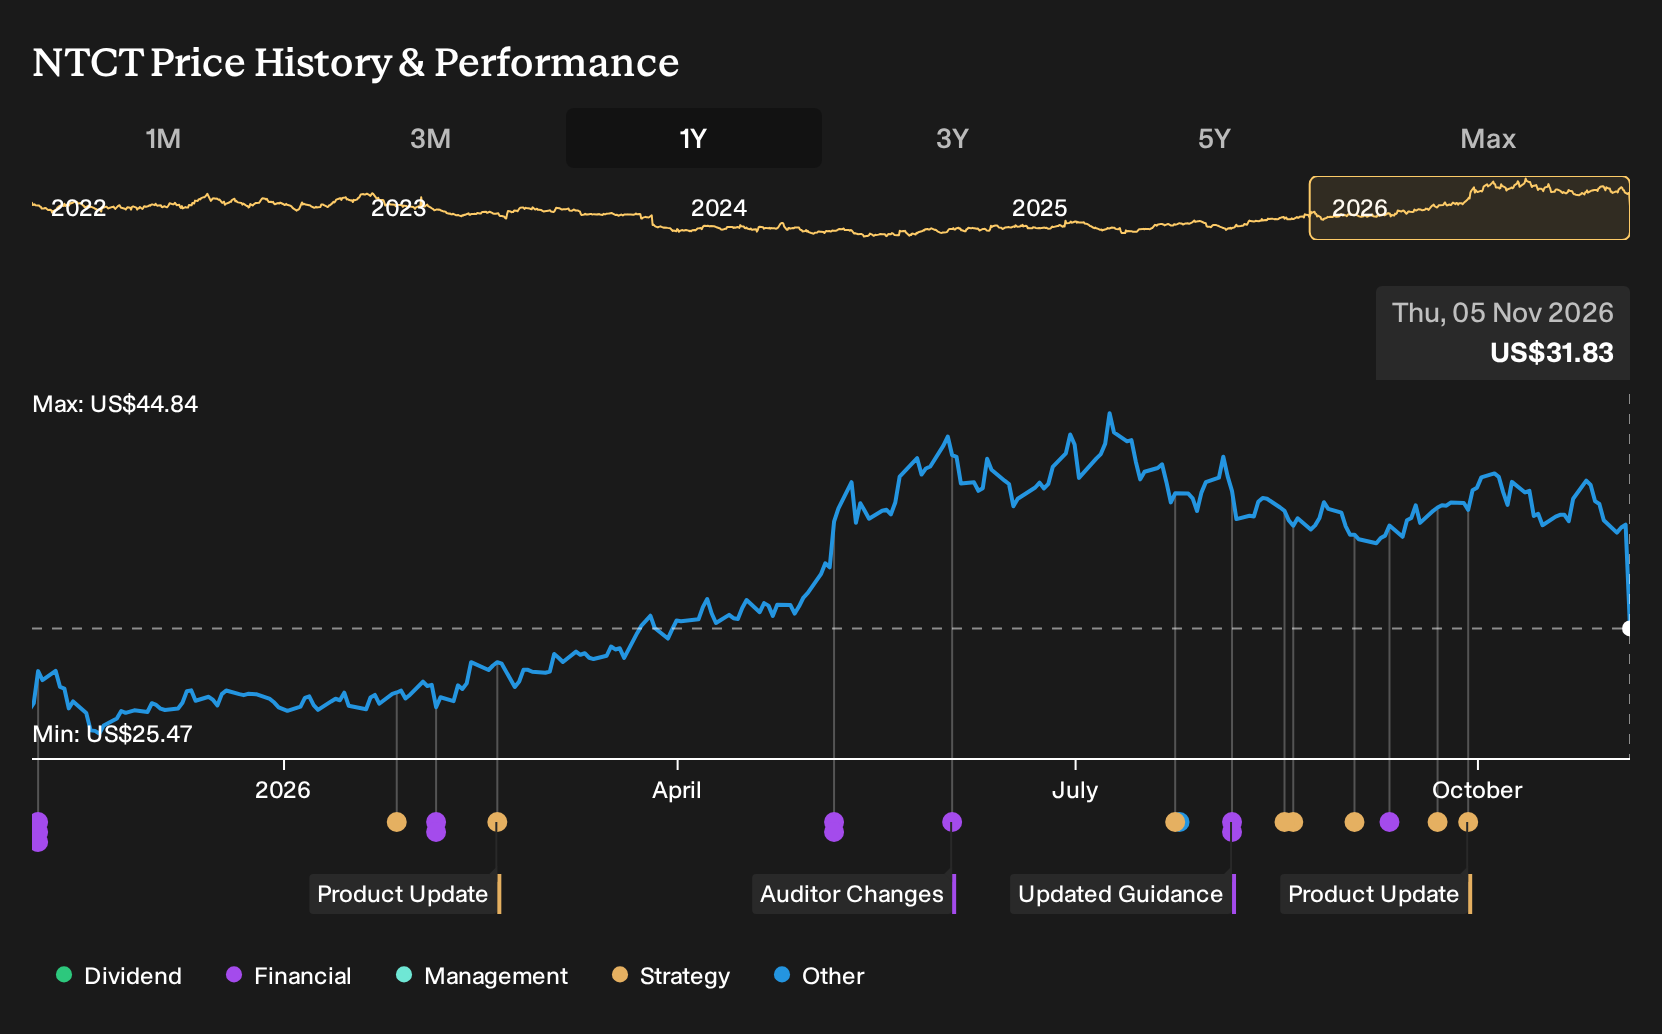
Uncover why NetScout Systems' fair value indicates a 31% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Another angle on NetScout Systems focuses on a single swing factor. Bullish analysts lean hard into the catalyst of higher margin cybersecurity and cloud DDoS services. They were already penciling in about US$959.3 million of revenue and US$106.8 million of earnings by 2029. This fresh earnings report could shift those expectations, so treat it as a cue to compare several viewpoints before deciding what the story looks like to you.
Explore 4 other NetScout Systems fair value estimates, including one that suggests as much as 106% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NetScout Systems research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for NetScout Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NetScout Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond NetScout Systems?
If NetScout Systems has sharpened your thinking about network observability, cybersecurity, and capital allocation, it can be useful to compare it with other opportunities that share some of the same financial traits. The Simply Wall St Screener helps you scan wider without losing focus on quality.
- If capital preservation sits high on your priority list, start with a group of companies that screen as relatively resilient using our 32 resilient stocks with low risk scores.
- For readers hunting for mispriced opportunities with solid fundamentals, cast a wider net with a 42 high quality undervalued stocks that match your preferred quality and valuation filters.
- Income focused investors who want cash returns plus financial strength can review a 6 dividend fortresses that combine higher yields with robust balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com