


EN
BlackLine (BL) Stock Looks Hard To Call As France Cloud News Lands
BlackLine has seen its share price move sharply over recent years, and the question now is whether the current valuation lines up with the earnings the business is producing. With the stock trying to find its footing after a difficult stretch, investors are increasingly focused on what those earnings actually justify.
- Over the past 5 years, BlackLine’s share price has fallen 73.3%. This puts the spotlight firmly on whether the earnings profile supports even today’s lower level.
- The new partnership with S3NS to offer BlackLine’s Agentic Financial Operations Platform on a trusted cloud in France can influence how investors think about future revenue growth and the timing of earnings tied to regulated, data-sensitive clients.
- The analysts covering BlackLine have run their own numbers. See what analysts think BlackLine's shares could be worth.
The issue now is whether BlackLine’s current share price of US$33.67 is justified by the earnings that underpin it.
If you are questioning whether BlackLine’s earnings back up its US$33.67 share price, it can help to compare that same valuation lens across 42 high quality undervalued stocks.
Where Does BlackLine Sit on Earnings?
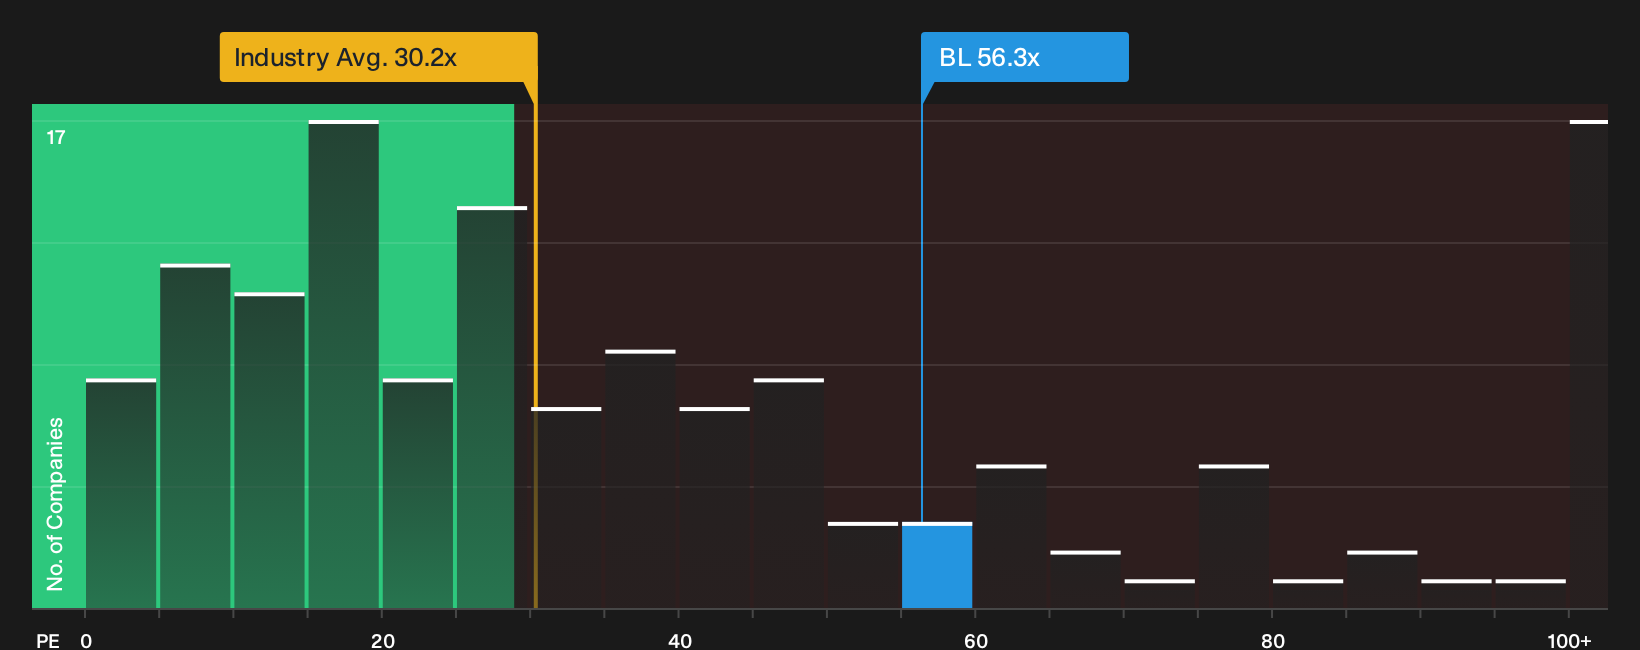
The P/E ratio is a useful lens for BlackLine because the company reports positive earnings and investors often anchor expectations on what they pay for each dollar of profit. BlackLine currently trades on a P/E of 56.3x, which is higher than both the Software sector average of 30.2x and the peer group average of 46.7x. Based on the tailored fair benchmark used here, which blends factors like margins, scale and risk, the current multiple sits close enough that the market’s pricing looks about right rather than clearly stretched or cheap.
Because BlackLine has just announced its Agentic Financial Operations Platform on S3NS’s trusted cloud in France, part of that P/E also reflects how investors price in opportunities with data sensitive customers. For your own view, the key question is whether the earnings power you expect from BlackLine over time matches paying a mid 50s earnings multiple today, or whether that same cash could be put to work in software stocks that trade on lower ratios. Explore the numbers behind BlackLine's P/E valuation.
The BlackLine Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the BlackLine valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings power would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Each Narrative treats fair value as a specific, testable idea about BlackLine’s business that you can track over time, rather than a static snapshot.
Community views on BlackLine are split between those who see an AI driven control platform taking hold and those who worry the backlog takes too long to show up in the numbers.
Bull case: 12% undervalued
"Growing adoption of the Studio360 cloud platform, Verity agents, and the Finance Control Console positions BlackLine as a control and governance layer for AI driven financial operations…"
Discover why this Narrative puts BlackLine at 12% undervalued.
Bear case: 46% overvalued
"Although BlackLine reports remaining performance obligations above US$1.1b with growth that exceeds current revenue, weak billings growth around 8.5% last year and a roughly 6% billings pace in recent quarters signal that slower conversion of this backlog could leave revenue and earnings below what current contracts seem to imply…"
Explore why this Narrative puts BlackLine at 46% overvalued.
BlackLine’s valuation still hinges on who is in charge
Numbers only tell part of the story for BlackLine, because the people setting priorities, allocating capital and deciding their own rewards can tilt those outcomes in very different directions. See who runs BlackLine and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com