


EN
Box (BOX) Is Getting Attention Again, What Is Behind The Focus?
Box (BOX) just rolled out an expanded Box for Industries lineup alongside its new Box Architect platform, aiming to bring AI-driven workflows and tighter security to heavily regulated sectors.
Investors have already reacted to Box’s AI and security push, with the share price advancing 23.48% over the past month and 31.02% over 90 days. Meanwhile, the year-to-date share price return of 51.06% and 1-year total shareholder return of 39.99% indicate strong momentum rather than a short-lived spike.
Scan how Box’s AI momentum compares with other software players by zeroing in on 41 profitable AI stocks that aren't just burning cash, which pair real earnings with exposure to the same theme.
Box has already logged a strong run, yet the shares still trade at what looks like a meaningful discount to one estimate of intrinsic value. Is most of the easy upside already captured, or is the valuation gap still doing the heavy lifting?
Most Popular Narrative: 12% Overvalued
Box last closed at $43.55, which sits above the most followed narrative fair value of $38.71 that is based on an 8.9% discount rate and detailed earnings assumptions.
The current figures on growth, margins and capital returns imply a share price that may not fully reflect Box's potential benefits from higher value per customer and greater AI-driven consumption.
The main factor that has to go well is that Enterprise Advanced, AI units and ecosystem partnerships continue to convert Box's large seat expansion and legacy migration pipeline into durable customer spend and net retention.
See why 7 investors see Box as 12% overvalued.
Result: Fair Value of $38.71 (OVERVALUED)
Still, the Box narrative can wobble if AI units fail to convert seat expansion into durable spending, or if bundled suites reduce pricing power and retention.
Find out about the key risks to this Box narrative.
Another View: Box Through The SWS DCF Lens
Analyst narratives suggest Box looks 12% overvalued around $43.55, yet the SWS DCF model points in a different direction. On that cash flow view, the shares trade about 27% below an estimated future cash flow value of $59.70, which frames current pricing as a potential discount rather than a premium.
The gap between a $38.71 narrative fair value and a $59.70 DCF output leaves a wide band of outcomes for investors to weigh. It raises a simple question. Are analyst earnings multiples leaning too hard on near term margin pressure while the SWS DCF model leans more on Box’s longer dated cash generation potential, or is it the other way around for you as an investor?
Look into how the SWS DCF model arrives at its fair value.
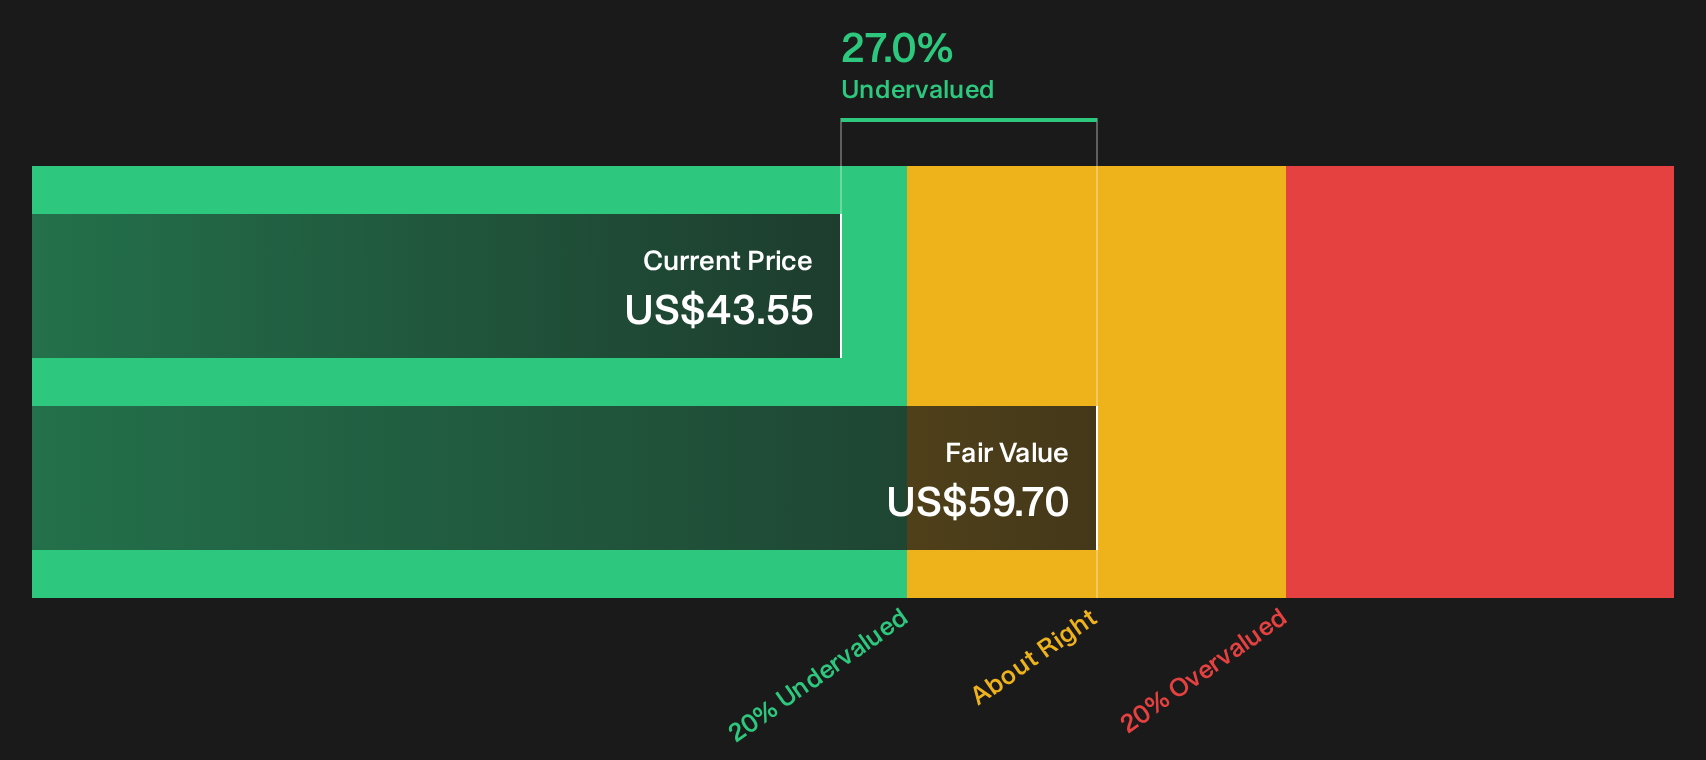
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Box for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The mix of enthusiasm around Box and questions on valuation creates a split picture, so act while the data is fresh and decide where you stand by weighing 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Box?
If Box has sharpened your focus on quality opportunities, do not stop here. Broaden your watchlist with ideas filtered by earnings strength, balance sheets and income resilience.
- Upgrade your watchlist by hunting for companies trading at appealing valuations using the 42 high quality undervalued stocks.
- Strengthen your downside protection by scanning businesses with robust finances through the list of solid balance sheet and fundamentals (24 results).
- Build a recurring income stream by reviewing companies highlighted in the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com