


EN
How Electric Pump Launch At Graco (GGG) Has Changed Its Investment Story
- Graco recently introduced the electric 3 inch QUANTM i230 double diaphragm pump, aimed at paint, coatings, and ceramics producers who want higher throughput and lower energy use while reducing reliance on plant air systems.
- The QUANTM i230 brings electric drive technology into a category long dominated by pneumatic pumps. This development could shift customer focus toward energy savings and tighter integration with plant automation and control systems.
- This article examines how Graco's investment narrative is influenced by this energy efficient pump launch and its automation friendly design.
Scan Graco's shift toward cleaner, automation ready equipment alongside a curated field of similar plays in industrial efficiency with the 89 robotics and automation stocks.
What Is Graco's Investment Narrative?
Owning Graco means buying into a fairly steady industrial story where execution, product quality, and disciplined capital use matter more than splashy growth. Earnings and revenue are both forecast to rise in the mid single digits, with high quality profits and a strong 21% return on equity suggesting a well run operation. The QUANTM i230 fits that playbook. It tightens the link between Graco hardware and customers' automation systems, which supports pricing power and stickier relationships more than it transforms the near term revenue outlook.
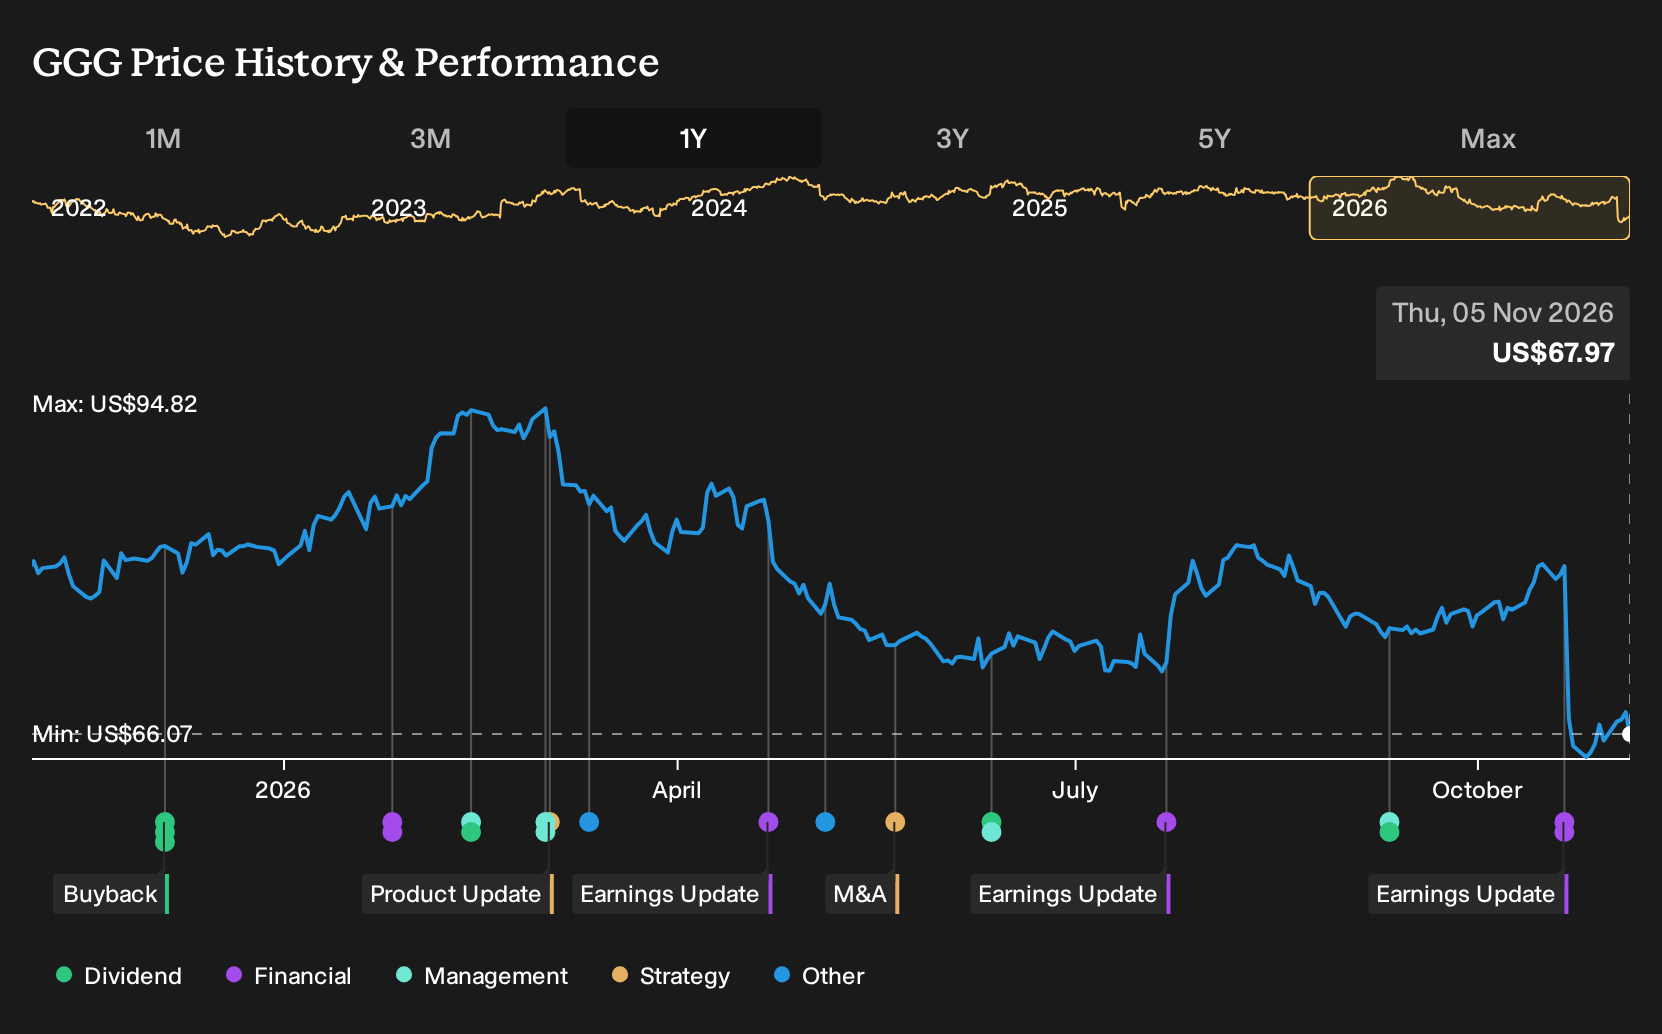
In the short term, the bigger swing factors sit elsewhere. Recent underperformance, with the share price down over the past year despite forecasts for continued earnings growth and a 1.74% dividend, indicates that sentiment has cooled even as analysts still see upside and the stock screens as good value on some cash flow metrics. Capital intensity and funding mix also deserve attention, since the business relies on higher risk external borrowing rather than customer deposits, and product bets like QUANTM only really pay off if demand from industrial, contractor, and expansion markets stays healthy enough to support that investment.
Yet there is one pressure point in Graco's story that rarely shows up in the headline numbers and that could...
There's only one way to know the right time to buy, sell or hold Graco. Head to Simply Wall St's company report for the latest analysis of Graco's Fair Value.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$60 and about US$90.60, so opinion on Graco’s worth already spans a wide band. Those views also predate the QUANTM i230 launch, which could lead some investors to revisit their models and rethink how efficiently focused equipment shapes long term performance.
Explore 2 other Graco fair value estimates, including one that suggests there may be as much as 33% upside from the current price!
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Graco research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Graco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Graco's overall financial health at a glance.
Looking For More Investment Ideas Beyond Graco?
If the Graco story has you thinking about where efficiency, balance sheet strength, and income potential intersect, it can help to line it up against a wider field of opportunities using the Simply Wall St Screener.
- For investors who want potential mispricing combined with quality fundamentals, scan a focused set of companies screened as 42 high quality undervalued stocks that may warrant a closer look.
- If capital preservation ranks high on your list, filter for businesses that score well on stability and financial resilience with a 32 resilient stocks with low risk scores to narrow your research down to sturdier options.
- For those who prefer rock solid finances as a starting point, start with a list of solid balance sheet and fundamentals (24 results) and then layer on your own view of growth, dividends, or valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com