


EN
Harrow (HROW) Stock Still Looks Undervalued On Its 135% Five Year Run
Harrow has given investors a mixed ride, with the share price well up over five years but sharply weaker over the past year. That puts fresh focus on whether the current valuation lines up with its sales. With the stock around US$26.04 at the last close, the question is how much of the business story is already reflected in that price tag.
- Over the past 5 years, Harrow has delivered a total share price gain of about 135%, which raises the stakes for anyone asking how much sales can justify at today's level.
- The launch of the HarrowRx platform that plugs directly into electronic medical record systems may support higher prescription volumes and smoother product access, which could influence how investors frame the value of its sales base.
- Your read on Harrow is one view; the desks covering it have another. See what analysts think Harrow's shares could be worth.
The stock's next move may depend on whether Harrow's current price can be reasonably explained by its sales when set against the Fair Ratio benchmark.
If you are questioning whether Harrow's US$26.04 share price is fully justified by its sales, it can help to compare that same valuation lens across 42 high quality undervalued stocks.
Does Harrow Look Undervalued on Sales?
Price to sales fits Harrow because investors are mainly paying for its existing revenue base rather than current profits.
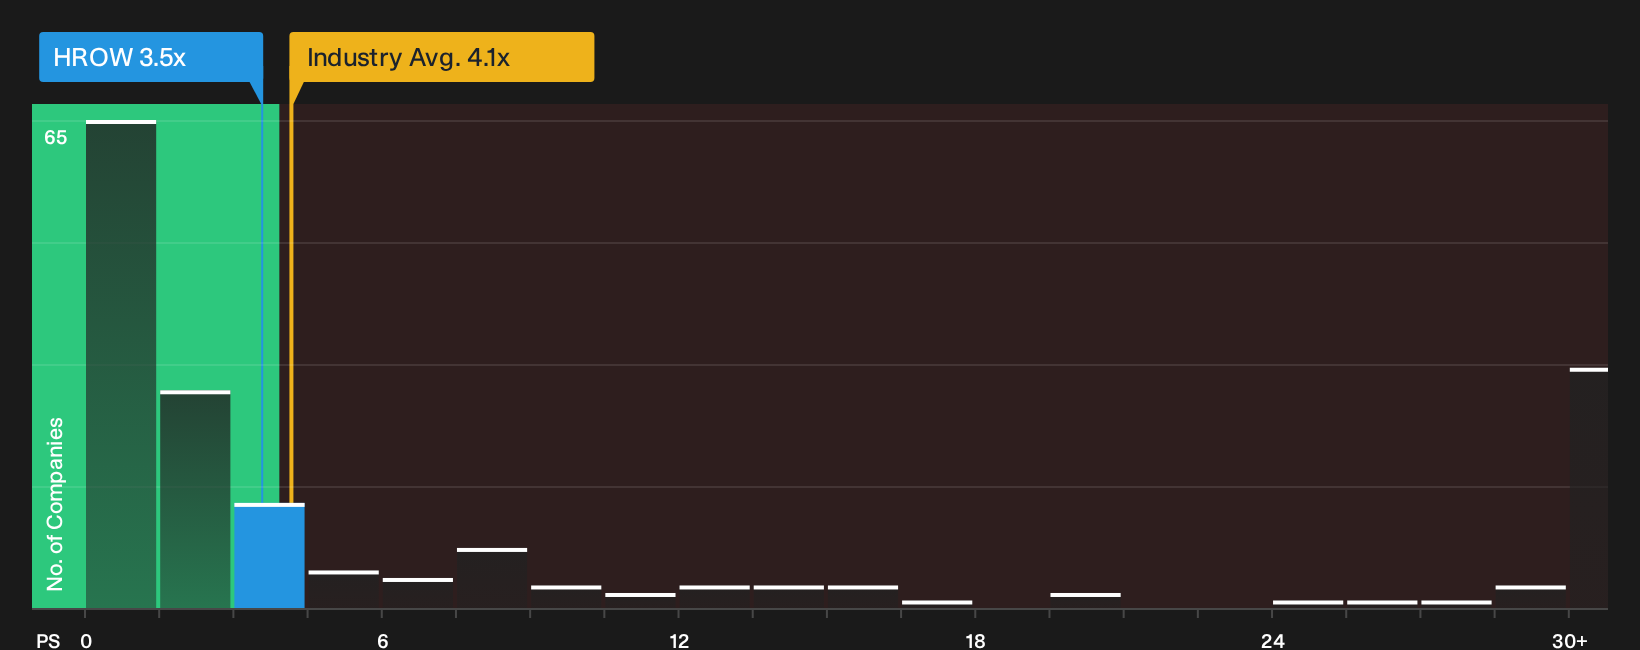
On this lens, Harrow trades on a P/S of about 3.5x, which is lower than the Pharmaceuticals industry average near 4.1x and also below the peer group around 5.8x. The Fair Ratio, which reflects what a typical P/S could look like after factoring in margins, growth profile, size and risk, sits above the current level, so the shares screen as undervalued on this measure. Because the HarrowRx launch plugs the portfolio directly into eye care EMR systems, the market is still pricing the business at a discount to what this framework suggests might be justified if that platform helps the sales base scale efficiently. Explore the numbers behind Harrow's P/S valuation.
The Harrow Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Harrow's P/S puzzle leaves off and explain what combination of future growth, margins and earnings would need to occur for the stock to be worth meaningfully more or less than today, using the Community page as the home base for those scenarios. Each Narrative links a specific outlook on Harrow's potential catalysts and key risks to its own estimate of fair value so you can track which storyline appears to be unfolding over time.
One of the top community narratives on Harrow: 42% undervalued
"The main thing that has to go right is that Harrow converts strong prescription demand and expanded commercial coverage for products like VEVYE, IHEEZO and TRIESENCE into sustainably higher net revenue…"
Discover why this Narrative puts Harrow at 42% undervalued.
Before moving on from Harrow, there is one more angle to check
Price tags and sales multiples only tell part of Harrow's story. The people directing capital, and how they are rewarded, can tilt outcomes in powerful ways. See who runs Harrow and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com