


EN
Earnings Beat May Test The Case For TransMedics Group Stock
- TransMedics Group reported third quarter 2026 revenue of US$203.01 million versus US$143.82 million a year earlier, with net income of US$17.07 million compared with US$24.32 million and diluted EPS from continuing operations of US$0.46 versus US$0.66.
- The latest results show higher revenue for both the quarter and the first nine months of 2026 alongside lower earnings, which highlights the cost and investment burden TransMedics Group is carrying as it builds out its transplant services platform.
- Attention now turns to how TransMedics Group's higher-than-expected quarterly revenue, despite softer profitability, may reshape the broader investment narrative.
Scan how TransMedics Group's latest mix of strong revenue and softer earnings compares with other high quality balance-sheet-focused stocks through this curated list of solid balance sheet and fundamentals (24 results).
TransMedics Group Investment Narrative Recap
To own TransMedics Group, you need to believe the transplant platform keeps gaining procedures across organs and geographies, while the service model matures enough to support consistent profitability. The latest quarter reinforces that trade off. Revenue for both the quarter and year to date is higher, but earnings for each period are lighter as spending stays elevated.
The key near term swing factor remains whether OCS Kidney, European expansion and logistics services can scale without keeping operating costs climbing faster than sales. The biggest risk is that this growth first spending settles into structurally thinner margins. The Q3 figures do not yet resolve that question either way.
The third quarter 2026 earnings release is the clearest data point to focus on. TransMedics Group reported US$203.01 million of quarterly revenue and US$566.89 million for the first nine months, with net income of US$17.07 million for the quarter and US$39.07 million year to date. Diluted EPS from continuing operations was US$0.46 in Q3 and US$1.08 for nine months.
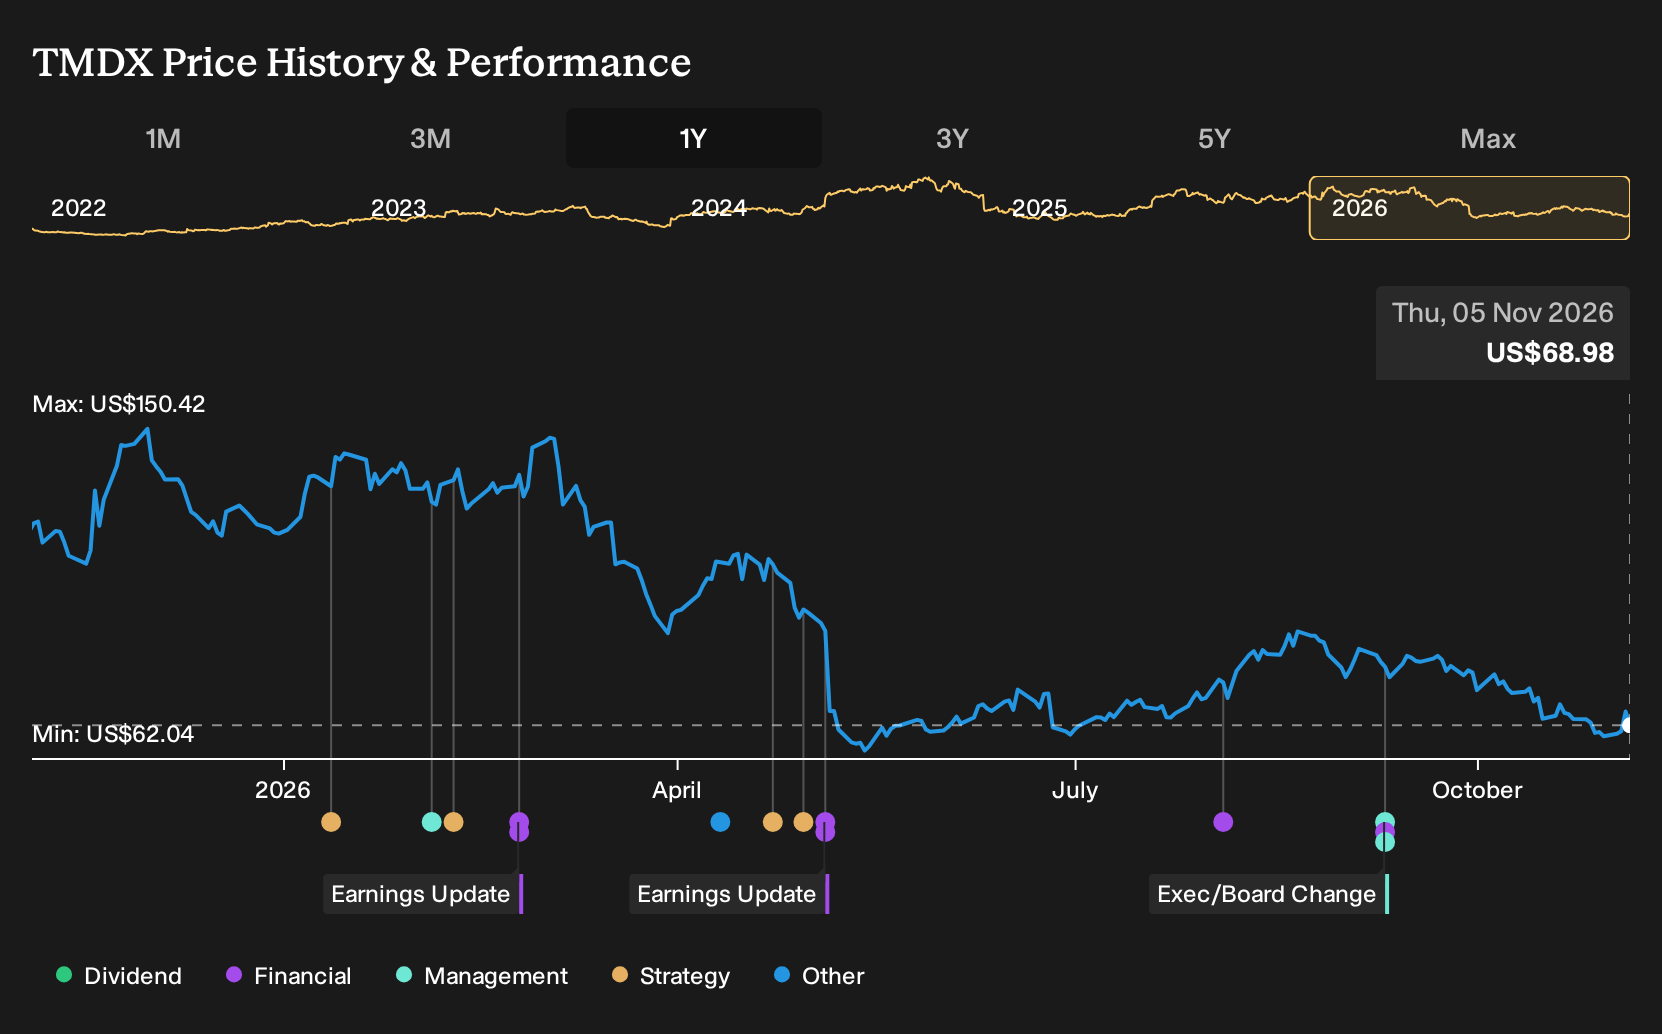
These results sit against rising sector interest after the stock moved 8.4% higher on November 4 in a broader medical device rally. For catalysts, the mix of strong top line and softer profit puts execution on OCS Kidney, NOP services and margin discipline in sharper focus. The operational risk is that higher transplant activity does not translate into the earnings profile many investors are watching for.
What Current Analyst Assumptions Signal For TransMedics Group
Analysts are effectively asking investors to weigh TransMedics Group as a transplant platform that leans hard into growth, while accepting some compression in profitability. Their models build in 18.0% yearly revenue expansion over the next three years, paired with profit margins that step down from 22.7% today to 17.5% by year three as spending on kidney, European roll out and logistics stays elevated. That mix of higher activity and thinner margins underpins the earnings bridge from US$151.7 million today to a consensus US$191.8 million by 2029, alongside modest share count growth of about 1.47% a year. The implied move in valuation, from a P/E of 18.2x now to 23.2x on those 2029 earnings, rests on the view that a more mature transplant services platform earns a premium relative to TransMedics Group's current setup, while still pricing in a discount to the wider US Medical Equipment sector multiple of 24.6x.
The spread between present and projected profit also gives you a simple sense check. Forecast earnings of US$191.8 million against US$151.7 million today implies an increase of roughly US$40 million, which needs to come through a mix of volume growth and operating discipline even as analysts expect margins to drift lower. That is before layering in assumed dilution from a rising share count, which means earnings per share growth depends on the business outpacing that issuance. Any shift in transplant adoption curves, OCS Kidney uptake or cost structure could change that earnings path, so it is worth treating the US$191.8 million figure as one reference point rather than a fixed outcome.
TransMedics Group Valuation Frame And What Needs To Go Right
The valuation work rests on a relatively tight set of headline numbers that readers can anchor on. The consensus blueprint points to TransMedics Group generating about US$1.1b of revenue and US$191.8 million of earnings by 2029, and trading on a P/E of 23.2x at that point, using a discount rate near 8.1%. Those assumptions underpin a central analyst price target of US$97.3 per share, bracketed by a high case of US$125.0 and a low case of US$65.0, against a current share price of US$79.8 as at early November 2026. Analysts are effectively signalling that the market price does not fully reflect their modeled earnings base and margin profile, even though they also flag pressure on profitability as investment continues.
For you, the practical question is which of these moving parts feels most uncertain. Revenue growing at 18.0% a year for several years, profit margins settling closer to the mid teens, and a richer P/E multiple in 2029 all need to line up to hit the consensus fair value story. If transplant volumes or pricing end up lower than embedded in the US$1.1b revenue figure, or if operating costs eat into earnings more than expected, the US$191.8 million profit estimate could prove optimistic. If results resemble or exceed the current analyst curve, that supports the idea that TransMedics Group is building into the type of scaled services business that analysts are using in their models. Either way, the spread between the current share price and the range of targets makes it important to cross check these external estimates against your own view of the transplant market, regulatory risk and the long term role of outsourced organ services.
TransMedics Group's current analyst framework points to forecast revenue of US$1.1b and earnings of US$191.8 million by 2029, anchored on 18.0% annual revenue growth and an earnings increase of roughly US$40 million from US$151.7 million today.
Uncover why TransMedics Group's fair value indicates a 41% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on TransMedics Group leans hard into OCS Kidney as a major catalyst. The most optimistic analysts were modelling about US$190 million of quarterly revenue and roughly US$1.2b by 2029, before this earnings release. Those forecasts sit above consensus, and this latest mix of higher sales and softer profit may prompt some of those projections to shift. You do not need to pick a side today. However, it is worth comparing these more aggressive expectations with your own read of transplant demand and how quickly kidney adoption can realistically build.
Explore 7 other TransMedics Group fair value estimates, including one that suggests as much as 591% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your TransMedics Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for TransMedics Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TransMedics Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond TransMedics Group?
If you want to cross check TransMedics Group against other stocks with different risk, income and valuation profiles, the Simply Wall St Screener can help you quickly narrow the field to a manageable shortlist.
- For investors who care most about resilient balance sheets and cleaner fundamentals, start with this curated list of solid balance sheet and fundamentals (24 results).
- If you are hunting for companies that screen as potentially mispriced on quality and value metrics, take a look at this focused set of 42 high quality undervalued stocks.
- Income focused readers who want higher yields with an emphasis on durability can review this hand picked group of 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com