


EN
BridgeBio Pharma (BBIO) Cut Losses And Grew Revenue, Is The Stock Still Undervalued?
BridgeBio Pharma (BBIO) just posted third quarter 2026 results that showed revenue of US$353.17 million and a reduced net loss of US$56.71 million, a combination many investors watch closely.
The mixed share price record around US$74.27 tells the story. The stock is up with an 11.68% 1 month share price return but down 12.09% over 3 months. At the same time, the 1 year total shareholder return of 20.18% and roughly 3 year total shareholder return of 174.06% point to longer running optimism as investors weigh BridgeBio Pharma’s revenue gains against ongoing losses and risk.
Compare BridgeBio Pharma’s latest momentum with a curated shortlist of other high-growth healthcare names using our 34 healthcare AI stocks for ideas beyond a single biotech story.
BridgeBio Pharma now trades around US$74.27 at a sizable discount to both analyst targets and one intrinsic value estimate. After the latest swing, is that gap mispricing or a fair warning label on ongoing losses?
Most Popular Narrative: 197.1% Overvalued
On Simply Wall St, the leading narrative on BridgeBio Pharma pegs fair value at $25.00, far below the recent $74.27 close. This frames the current price as rich for a still loss-making biotech with heavy launch spending ahead.
The "BridgeBio Commercial Bonanza" is priced for perfection, treating the upcoming Acoramidis launch as an automatic cash cow while ignoring a brutal multi-front commercial dogfight.
Here is why the market is mispricing the structural hurdles for BBIO:
1. The Pfizer Moat & SG&A Bleed: Outperforming Vyndaqel in a clinical trial does not guarantee market share. Pfizer’s commercial entrenchment in the ATTR-CM space is institutional. For BBIO to compete, marketing and launch expenses will likely need to rise substantially, which could severely depress free cash flow and delay true profitability relative to some expectations.
See why 4 investors see BridgeBio Pharma as 197% overvalued.
Result: Fair Value of $25.00 (OVERVALUED)
Still, the narrative could flip quickly if BridgeBio Pharma secures smoother than feared launches, or if upcoming clinical milestones reshape expectations around long term cash generation.
Find out about the key risks to this BridgeBio Pharma narrative.
Another View: Cash Flows Paint BridgeBio Pharma Very Differently
The most popular narrative calls BridgeBio Pharma overvalued at a fair value of $25.00, yet the SWS DCF model reaches a very different conclusion. Using projected cash flows, the SWS DCF model lands on a value of $313.48 per share, which presents the current $74.27 price as deeply undervalued.
This kind of gap places you as an investor in the middle of competing stories. One possibility is that the market is correctly focusing on commercial risk. Another is that it is heavily discounting future cash generation that the DCF model treats as central to the BridgeBio Pharma thesis.
Look into how the SWS DCF model arrives at its fair value.
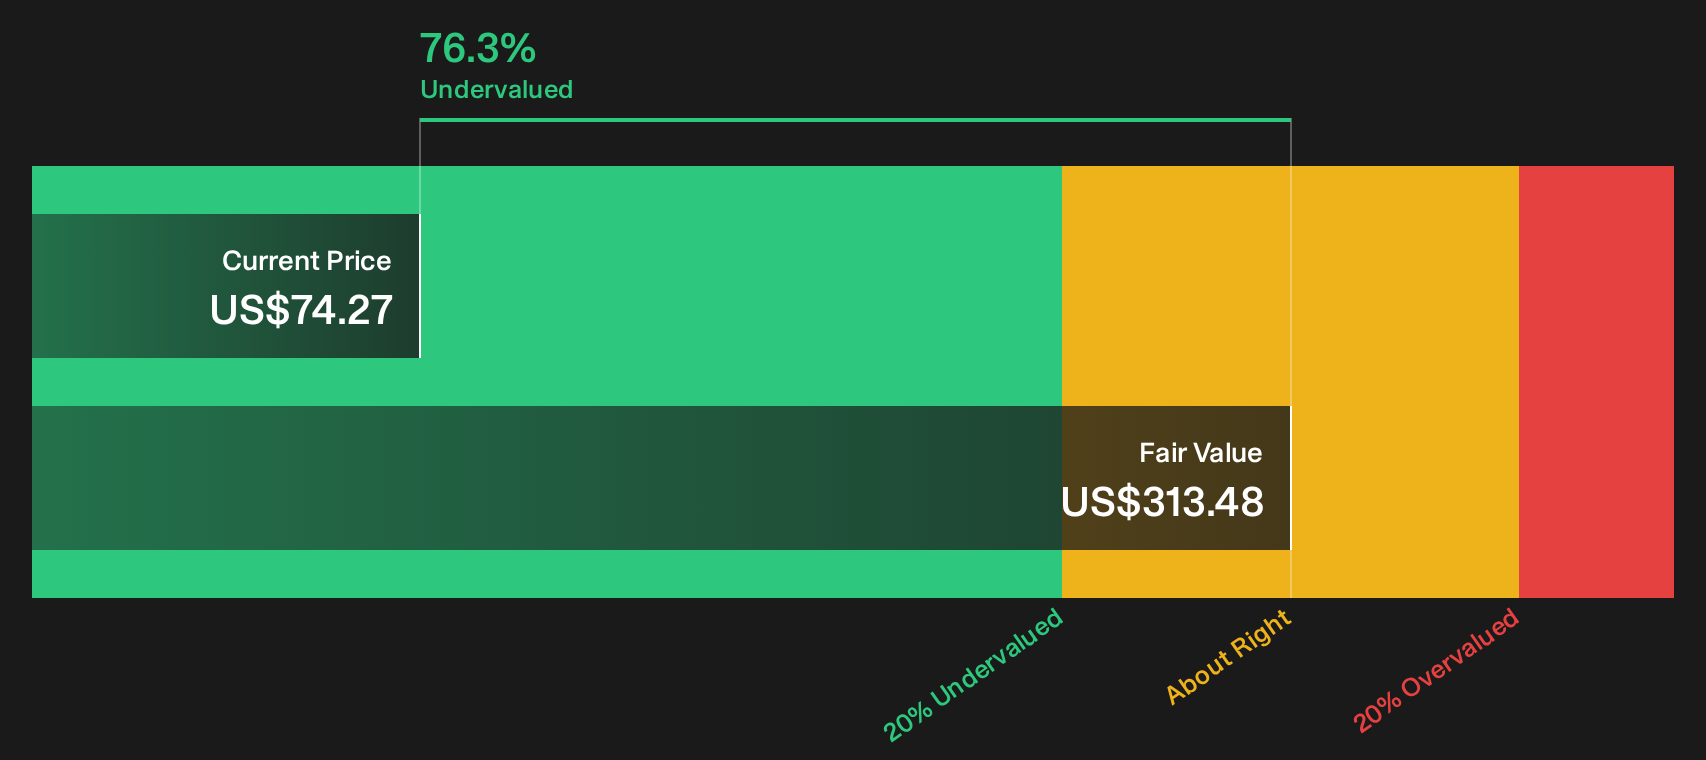
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BridgeBio Pharma for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If BridgeBio Pharma’s mixed messages feel hard to pin down, use that tension as a reason to move fast, review the data yourself, and weigh both caution and optimism through the lens of the 2 key rewards and 1 important warning sign.
Looking for more BridgeBio Pharma style investment ideas?
If BridgeBio Pharma has your attention, do not stop with a single ticker. Use the Simply Wall St screener to quickly surface other opportunities that match your approach.
- Target quality at a discount by scanning companies flagged in our 42 high quality undervalued stocks that pair strong fundamentals with pricing that may not fully reflect them.
- Prioritise resilience by reviewing the 32 resilient stocks with low risk scores and focus on businesses with sturdier balance sheets and fewer red flags pulling at your attention.
- Chase under-the-radar potential with the 21 high quality undiscovered gems and see which less followed stocks share traits you like without the heavy spotlight yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com