


EN
Are Wall Street Analysts Bullish on DoorDash Stock?
DoorDash, Inc. (DASH), headquartered in San Francisco, California, operates a commerce platform that connects merchants, consumers, and independent contractors. Valued at $86 billion by market cap, the company develops technology to connect customers with merchants through an on-demand food delivery application.
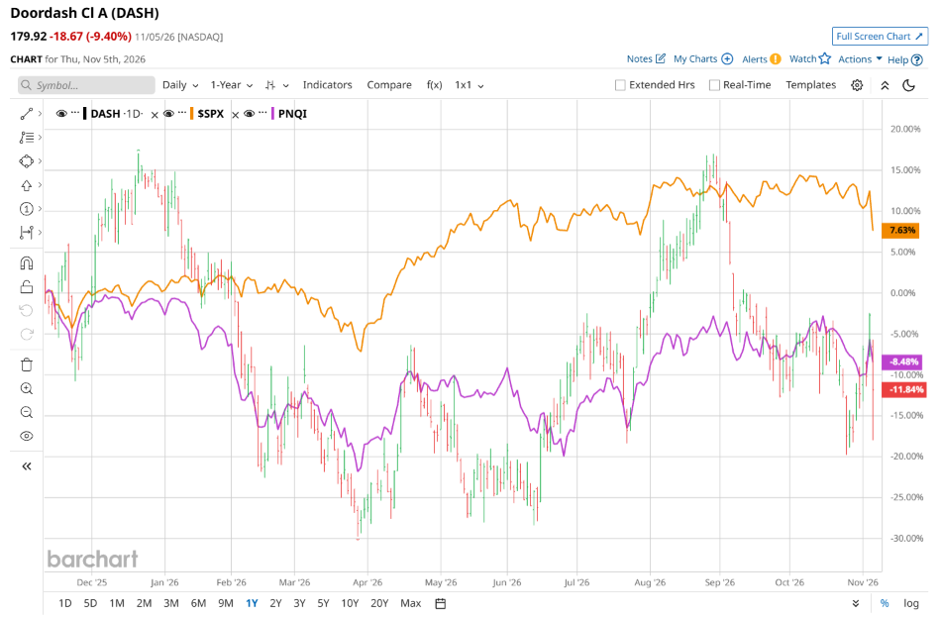
Shares of this food delivery giant have underperformed the broader market over the past year. DASH has declined 24.4% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 8.2%. In 2026, DASH stock is down 20.6%, compared to the SPX’s 7.4% gains on a YTD basis.
Narrowing the focus, DASH’s underperformance is also apparent compared to the Invesco NASDAQ Internet ETF (PNQI). The exchange-traded fund has declined about 8.7% over the past year. Moreover, the ETF’s 6.9% dip on a YTD basis outshines the stock’s double-digit losses over the same time frame.
DoorDash’s underperformance has been driven by a combination of high valuation expectations, intensifying competition, and persistent regulatory pressures regarding gig-economy labor costs and delivery pricing. While the company has continued to post solid top-line order and revenue growth, investors have grown increasingly sensitive to margin compression, elevated investment spending in new verticals, and periodic earnings volatility, all of which have led to sharp share price pullbacks from prior highs.
For the current fiscal year, ending in December, analysts expect DASH’s EPS to grow 25.8% to $2.68 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in two of the last four quarters while missing the forecast on two other occasions.
Among the 39 analysts covering DASH stock, the consensus is a “Strong Buy.” That’s based on 31 “Strong Buy” ratings, two “Moderate Buys,” and six “Holds.”
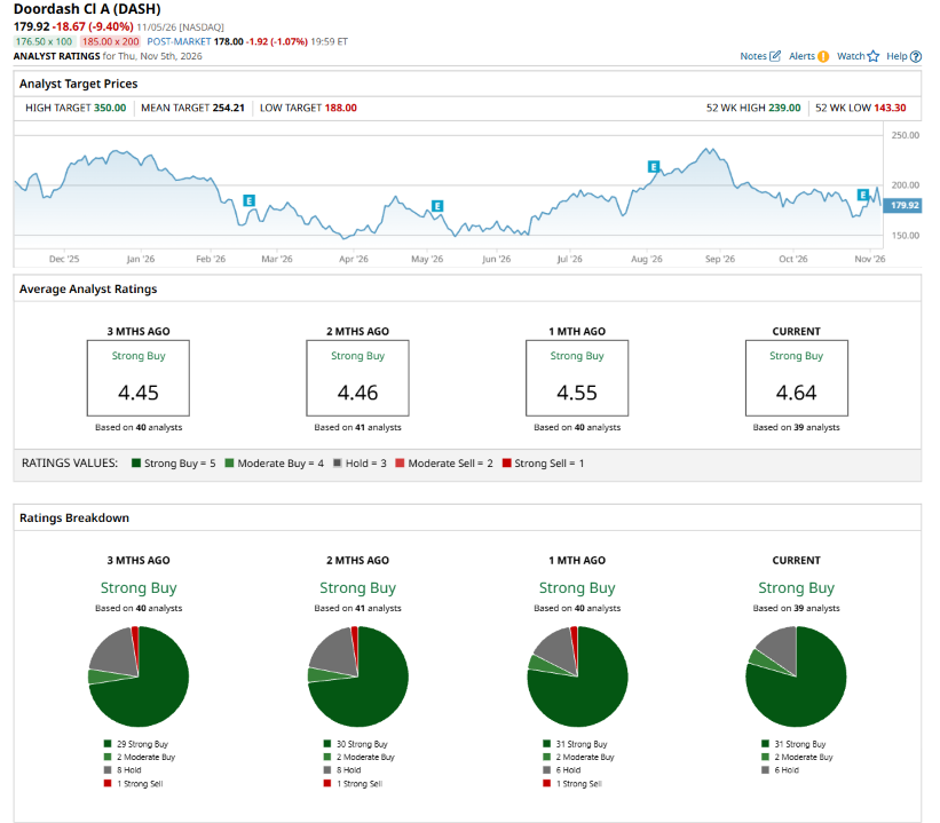
This configuration is slightly less bearish than a month ago, with one analyst suggesting a “Strong Sell.”
On Oct. 30, Scotiabank analyst Nat Schindler kept an “Outperform” rating on DASH and lowered the price target to $235, implying a potential upside of 30.6% from current levels.
The mean price target of $254.21 represents a 41.3% premium to DASH’s current price levels. The Street-high price target of $350 suggests a notable upside potential of 94.5%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.