


EN
Lucid Group (LCID) Faces Earnings Questions As Fair Value Looks About Right
Lucid Group (LCID) dropped 11.57% in the latest session, sharply lagging broad indices as traders looked ahead to the November 9 earnings report and fresh detail on the electric vehicle maker’s progress.
At a share price of $2.98, Lucid Group is coming off a steep 90 day share price decline of 57.67% and a 1 year total shareholder return that has fallen 82.75%, with recent drops clustering around headlines on vehicle recalls, Q3 delivery figures, and the upcoming earnings release rather than any clear improvement in sentiment.
Scan beyond Lucid Group’s recent slide and consider other beaten down EV and auto players with the hand picked 42 high quality undervalued stocks that still pair cash generation with sturdier balance sheets.
After a collapse this steep, the question becomes blunt: Is Lucid Group now priced for most of the pain already, or has the potential upside already been spent by earlier investors?
Most Popular Narrative: 1% Undervalued
Against a last close of $2.98, the most followed narrative on Lucid Group pegs fair value at about $3.02, which leaves a very small discount yet still frames expectations around the upcoming report rather than a long range target.
Consensus revenue is about $399.1 million from eight analysts, in a range of $321.7 million to $441.5 million. I expect about $376.6 million. With volume settled, the consensus needs a price Lucid has never reported. Excluding regulatory credits, revenue per delivery was $79.7K a year ago, $91.3K in Q1 and $96.1K in Q2. With $15 million of credits, $399.1 million needs about $100.9K per delivery, another 5% rise, in a quarter when Lucid delivered 852 more vehicles than it built. Some of the eight estimates were probably built before the delivery release and not revised.
See why 1 investors see Lucid Group as 1% undervalued.
Result: Fair Value of $3.02 (ABOUT RIGHT)
Still, two things could quickly challenge this Lucid Group setup: a revenue surprise driven by regulatory credit sales and a richer vehicle mix than current inventory implies.
Find out about the key risks to this Lucid Group narrative.
Another View: Lucid Group Through The Market’s Lens
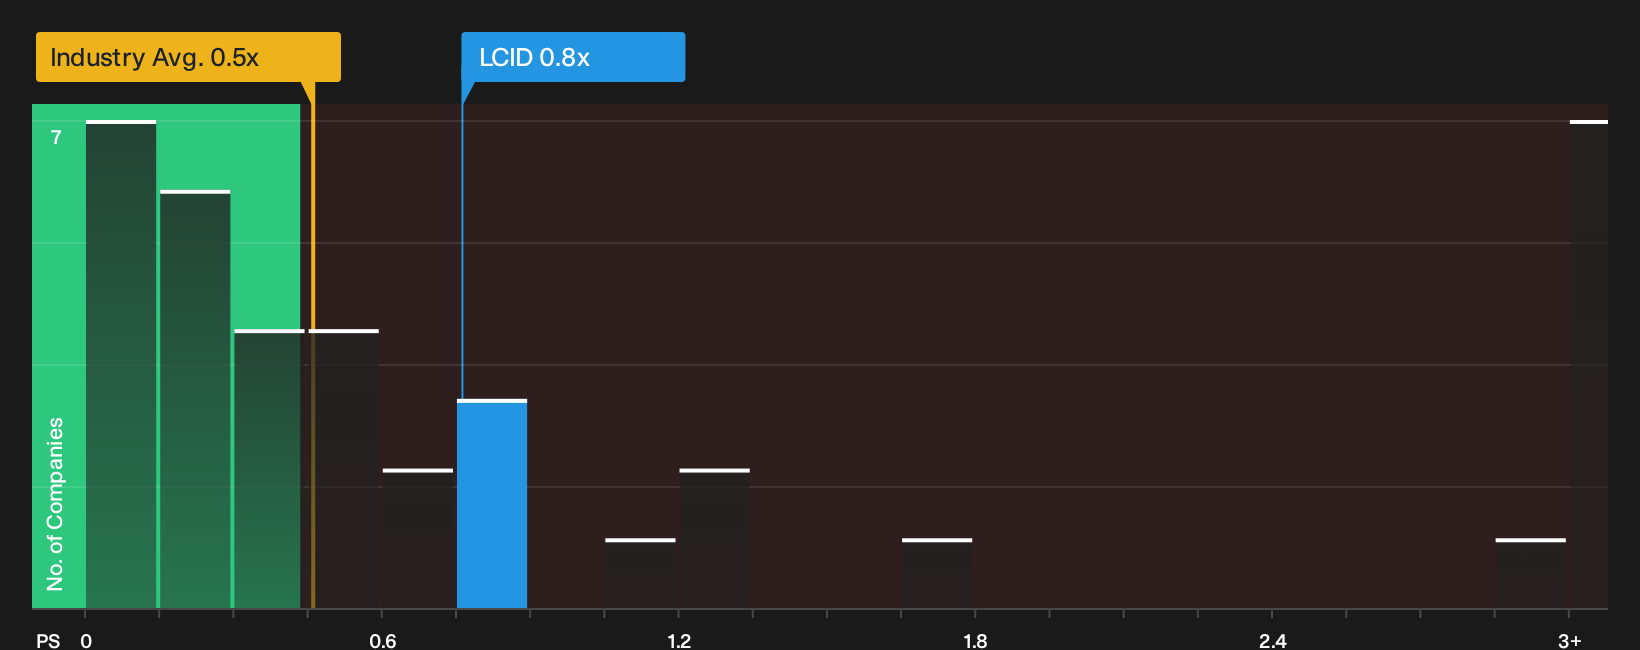
The first narrative on Lucid Group treats $3.02 as roughly fair. The market’s preferred yardstick tells a very different story. At about 0.8x P/S versus 0.5x for the wider US Auto group and 0.4x for closer peers, Lucid trades on a richer sales multiple despite ongoing losses and a fair ratio of 0x that points to far less support from regression based models. That gap raises a blunt question: Is this simply optionality being priced in, or are investors paying up for risk that has not yet been fully tested by results?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Lucid Group can tempt you to wait on the sidelines, yet the bigger risk is not checking the data yourself. Weigh the potential upside against the concerns by reviewing the 1 key reward and 3 important warning signs.
Looking for more Lucid Group sized opportunities?
If Lucid Group has you rethinking your watchlist, do not stop here. Use focused screeners to surface ideas that better fit your risk, income, and quality preferences.
- Target potential turnaround stories with strong balance sheets and real cash generation by scanning the 42 high quality undervalued stocks.
- Build a dependable income stream by hunting for companies that match your yield and resilience preferences through the 6 dividend fortresses.
- Dial down portfolio stress by focusing on businesses that score well on stability using the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com