


EN
W. P. Carey (WPC) Q3 Earnings Leave Its Fully Valued Narrative In Place
W. P. Carey (WPC) is back in focus after its third quarter 2026 report, which showed higher sales and revenue while quarterly earnings per share from continuing operations edged slightly lower.
Recent trading shows a mixed picture for W. P. Carey, with the share price up about 2.0% over the past month but down roughly 9.1% across the last quarter. Meanwhile, the 1 year total shareholder return of 4.1% and 3 year total shareholder return of 42.9% point to stronger longer run engagement with the REIT despite the softer reaction to the latest quarterly earnings.
Compare W. P. Carey’s mixed quarter with a curated group of income-focused real estate plays by scanning the 6 dividend fortresses that share similar yield driven appeal.
For W. P. Carey, a flat quarter on earnings and a pullback over three months now sit against stronger multi year returns. The key question is whether that combination still tips the risk reward balance toward buyers at today’s price, once valuation is unpacked next.
Most Popular Narrative: 27% Overvalued
The latest narrative on W. P. Carey pegs fair value at $51.35, which is below the recent $65.29 close, so the story tilts toward a premium price tag rather than a bargain.
Price sits slightly above my fair value estimate, so the stock looks fairly priced rather than cheap. The ~5.95% gross yield is attractive for a diversified net-lease stock, but at this level the margin of safety is thin and the buy signal stays Risky. I would rather wait for a pullback toward S1 or S2, where the risk/reward would improve. Until then, it stays on watch.
See why 2 investors see W. P. Carey as 27% overvalued.
Result: Fair Value of $51.35 (OVERVALUED)
Still, the narrative around W. P. Carey could shift quickly if tenant credit quality weakens, or if higher refinancing costs squeeze returns on its long leases.
Find out about the key risks to this W. P. Carey narrative.
Another View: Cash Flow Signals A Different Story
The fair value call from the narrative paints W. P. Carey as 27% overvalued at $51.35 versus the recent $65.29 price. The SWS DCF model points the other way. Its estimate of future cash flow value is $166.75 per share, which frames the stock as trading about 61% below that figure. If one lens says premium and another flags a wide discount, which signal do you put more weight on for your own process?
Look into how the SWS DCF model arrives at its fair value.
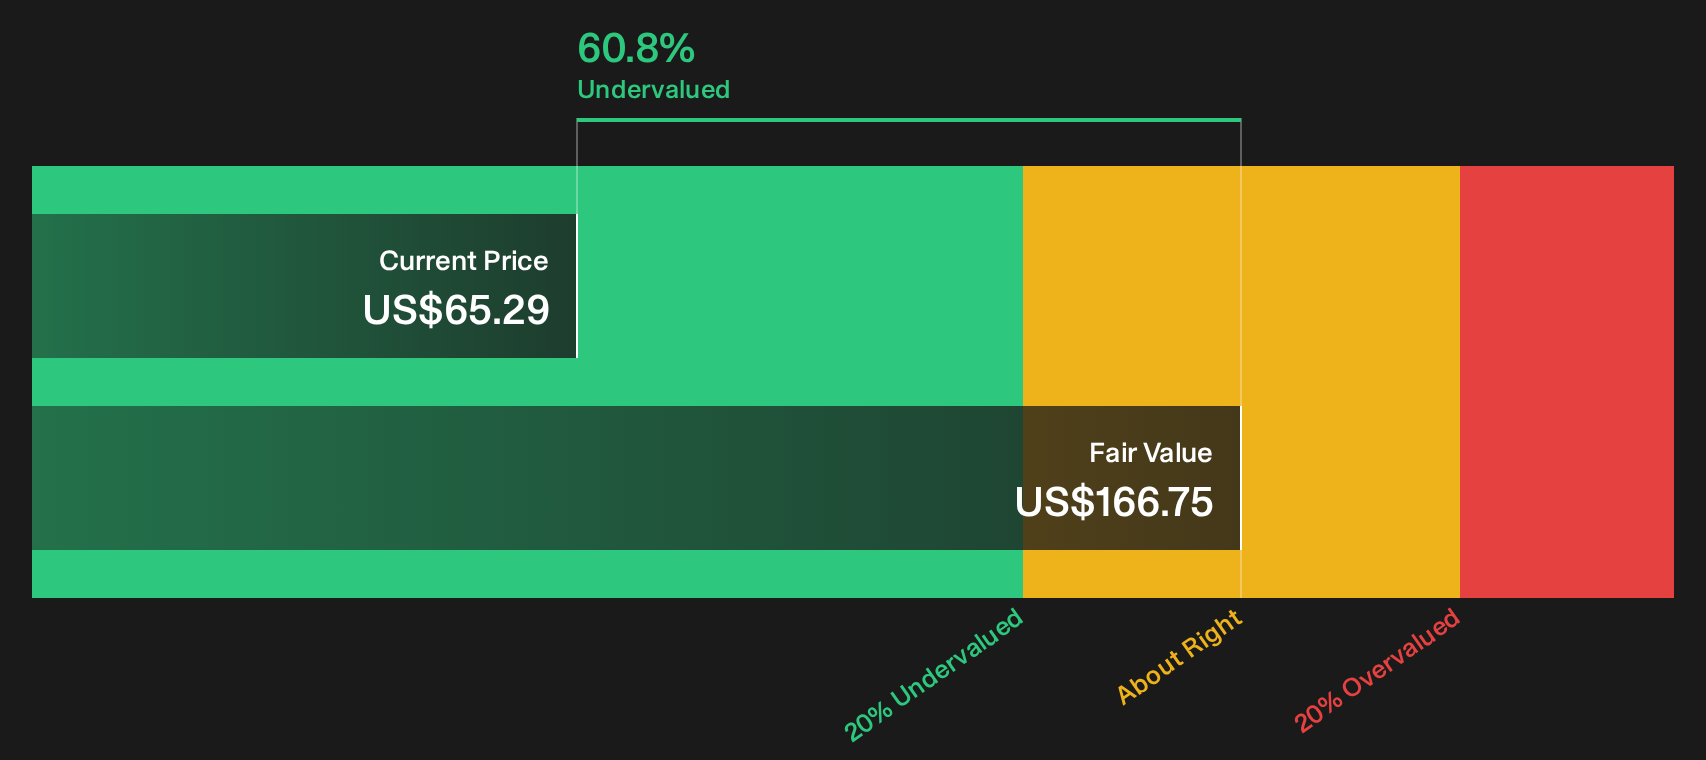
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out W. P. Carey for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around W. P. Carey can leave the picture feeling blurred, so move quickly, dig into the data, and compare it with your own risk appetite and income goals by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond W. P. Carey?
Do not stop your research with W. P. Carey. Broadening your watchlist with high quality ideas can sharpen your judgment and highlight better risk reward trade offs.
- Target reliable compounding potential by scanning a focused shortlist of quality opportunities in the 21 high quality undiscovered gems that pair strong fundamentals with quieter market attention.
- Prioritise capital preservation first and evaluate the 32 resilient stocks with low risk scores to see businesses that score well on financial resilience and measured volatility.
- Chase income without ignoring balance sheet strength by reviewing the 6 dividend fortresses that combine higher yields with sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com