


EN
Power Integrations (POWI) Stock Looks Overvalued After A 59% Five Year Fall
Power Integrations has seen its share price fall sharply in recent weeks, which puts fresh focus on whether the current valuation lines up with what the business is earning today. With the stock now some distance from its past highs, the key issue is how much of the recent earnings power the market is really paying for.
- Over the past 5 years the stock has fallen 59.3%, which raises questions about how investors should think about its earnings profile after such a long reset.
- Recent growth in demand for gallium nitride products and a higher dividend can support a view that future earnings and cash generation may look different from the past, which matters when you weigh the current share price against its profit base.
- There is a second opinion on Power Integrations worth weighing. See what analysts think Power Integrations's shares could be worth.
For investors, the debate is whether Power Integrations' current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you are reassessing Power Integrations after this earnings reset, it can help to compare it with a wider pool of quality candidates using 42 high quality undervalued stocks.
Is Power Integrations Getting Expensive on Earnings?
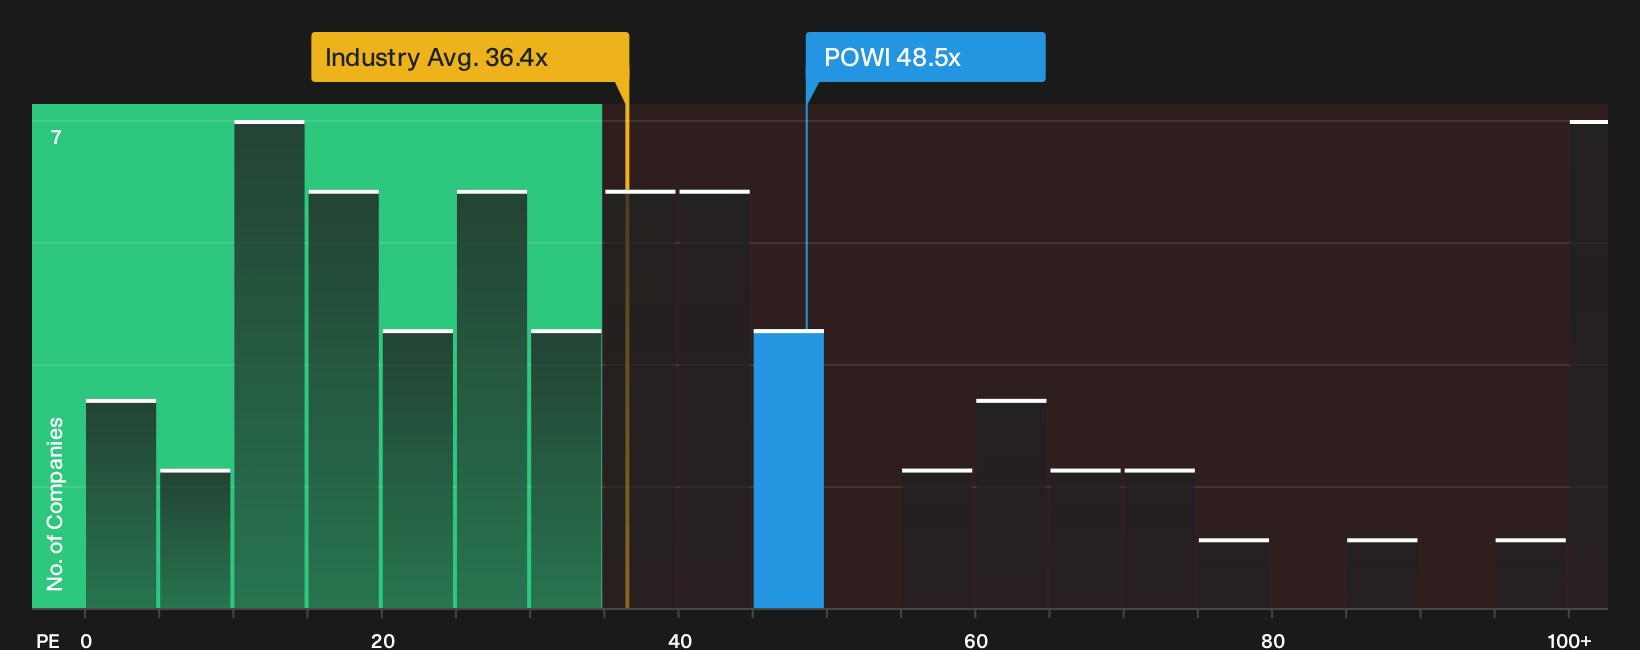
The P/E ratio fits Power Integrations because earnings are a key driver of how investors frame value for a profitable chip designer. The stock trades on a P/E of 48.5x, which is well above the Semiconductor sector average of 36.4x and ahead of the peer group on 26.6x. This means each dollar of current earnings at Power Integrations is priced more highly by the market than earnings at many comparable chip makers.
The Fair Ratio, which reflects what investors might typically pay given Power Integrations' size, economics and risk profile, comes out below the current market multiple, so the shares screen as overvalued on this measure. Despite the positive reaction to Q3 2026 GaN demand and the higher dividend, the valuation already assigns a premium to those trends compared with many sector alternatives. That gap is what you need to weigh when deciding whether the current P/E still leaves enough room for your own return expectations. Explore the numbers behind Power Integrations's P/E valuation.
The Power Integrations Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Power Integrations pick up where the valuation puzzle leaves off by laying out the specific growth, margin and earnings paths that would need to hold for the stock to be worth materially more or materially less than today’s price on the Community page. They turn a single P/E or valuation output into a set of future conditions, so you can watch how Power Integrations' actual progress lines up with the scenario that number implies.
One of the top community narratives on Power Integrations: 46% undervalued
"Some analysts highlight Power Integrations' high voltage GaN portfolio and its data center, EV, and industrial design wins as potential drivers of higher quality revenue and margins over time…"
Discover why this Narrative puts Power Integrations at 46% undervalued.
One more Power Integrations check that belongs beside the earnings multiple
Valuation only tells part of the story for Power Integrations, because the people steering the business and the way they are rewarded can shape how that story plays out over time. See who runs Power Integrations and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com