


EN
Donnelley Financial Solutions (DFIN) Turns Profitable Following Q3 Results But Is It Fully Valued
Donnelley Financial Solutions (DFIN) just paired a sharp swing back to profitability in the third quarter with fresh fourth quarter sales guidance of US$175 million to US$180 million, giving investors new fundamentals to weigh.
Recent trading shows that momentum in Donnelley Financial Solutions has been building, with a 30-day share price return of 35.61% and a year-to-date share price gain of 47.32%. The 1-year total shareholder return of 47.44% points to solid longer term performance, despite a 1-day share price pullback of 3.42% as investors digest the earnings beat, new AI-focused product launch and the completion of a US$31.49m repurchase program.
Scan how Donnelley Financial Solutions compares with other financially robust companies using our curated list of solid balance sheet and fundamentals (24 results)
Donnelley Financial Solutions now combines a sharp earnings rebound, a fresh AI product launch, and a completed buyback with a steep share price run. Does that mix still skew the risk reward towards buyers at today’s valuation?
Most Popular Narrative: 7.5% Undervalued
On Simply Wall St’s most followed narrative, Donnelley Financial Solutions screens as modestly undervalued, with a fair value of $72.67 against a last close of $67.22. The story now hinges on whether its higher margin software mix really holds up.
The main thing that has to go right is continued growth and adoption of the software portfolio, including new AI features in Active Intelligence and ArcFlex, so that software gains are large enough to offset the ongoing structural decline in print and any softness in capital markets activity.
See why 4 investors see Donnelley Financial Solutions as 7% undervalued.
Result: Fair Value of $72.67 (UNDERVALUED)
Still, the Donnelley Financial Solutions story can break if capital markets activity stays muted for longer, or if the structural decline in print weakens overall sales faster than software adoption offsets.
Find out about the key risks to this Donnelley Financial Solutions narrative.
Another View: DFIN Through The Cash Flow Lens
There is a catch to the Donnelley Financial Solutions valuation story. While the narrative fair value sits at $72.67, the SWS DCF model points to a future cash flow value of $57.59, which is below the current $67.22 share price.
That makes the stock look expensive on cash flows even though it screens as modestly undervalued on the narrative fair value. Is the market paying up for the quality of the software pivot, or are expectations for future cash generation already running a bit hot?
Look into how the SWS DCF model arrives at its fair value.
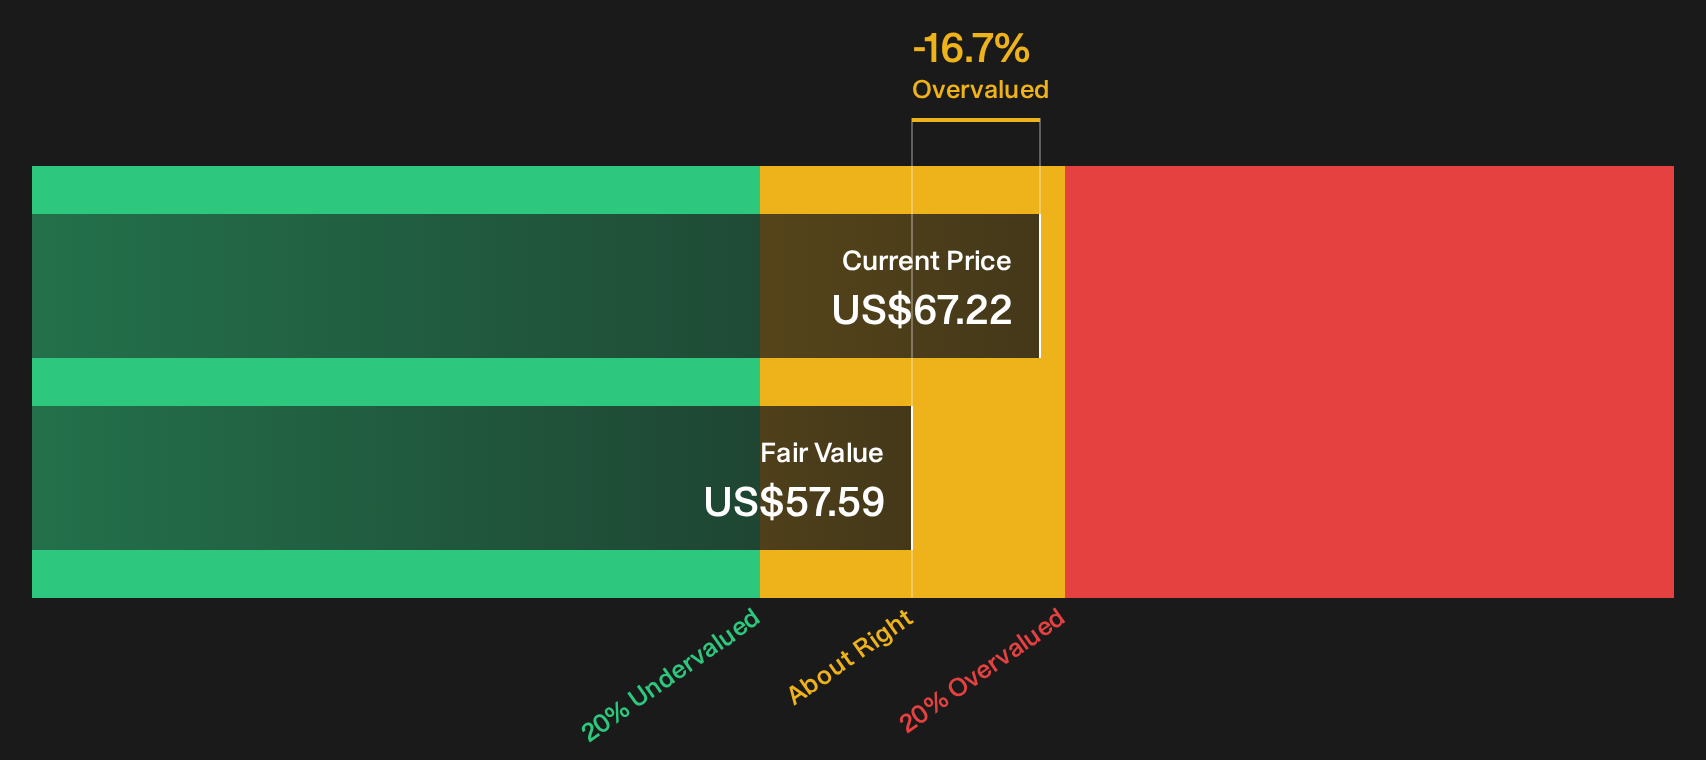
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Donnelley Financial Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Donnelley Financial Solutions can create just as much opportunity as risk, which is why it helps to inspect the numbers yourself and move quickly while sentiment is still forming. To weigh both sides of the story in one place, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Donnelley Financial Solutions?
If you only stop at Donnelley Financial Solutions, you miss a wider set of opportunities. Put a few minutes into fresh ideas now and your watchlist does the heavy lifting later.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) that filters for financial strength first.
- Hunt for quality at a discount by reviewing the 42 high quality undervalued stocks that highlights opportunities where price and fundamentals look out of sync.
- Prioritize staying power and lower volatility candidates with the 32 resilient stocks with low risk scores that screens for businesses with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com