


EN
Ameresco (AMRC) Stock May Be Fully Priced On Current Earnings
Ameresco's share price has been under heavy pressure in recent years, which naturally raises the question of whether the current valuation still lines up with what the business earns. After such a drawn out decline, the key issue for you is whether the stock price now fairly reflects the company’s earnings power.
- Over the past 5 years the share price has fallen 80.1%, which puts the focus squarely on whether the market has overreacted or is simply marking earnings reality.
- The business model depends on converting clean energy projects into steady earnings and cash flow, so the predictability and timing of those profits can heavily influence how investors value each dollar of Ameresco’s income.
- Your read on Ameresco is one view; the desks covering it have another. See what analysts think Ameresco's shares could be worth.
The issue now is whether Ameresco's current share price is justified by the earnings the business is generating today and is expected to produce in the future.
If you are weighing Ameresco after this long slide and want a broader earnings-focused watchlist, it can help to line it up beside 42 high quality undervalued stocks.
Where Does Ameresco Sit on Earnings?
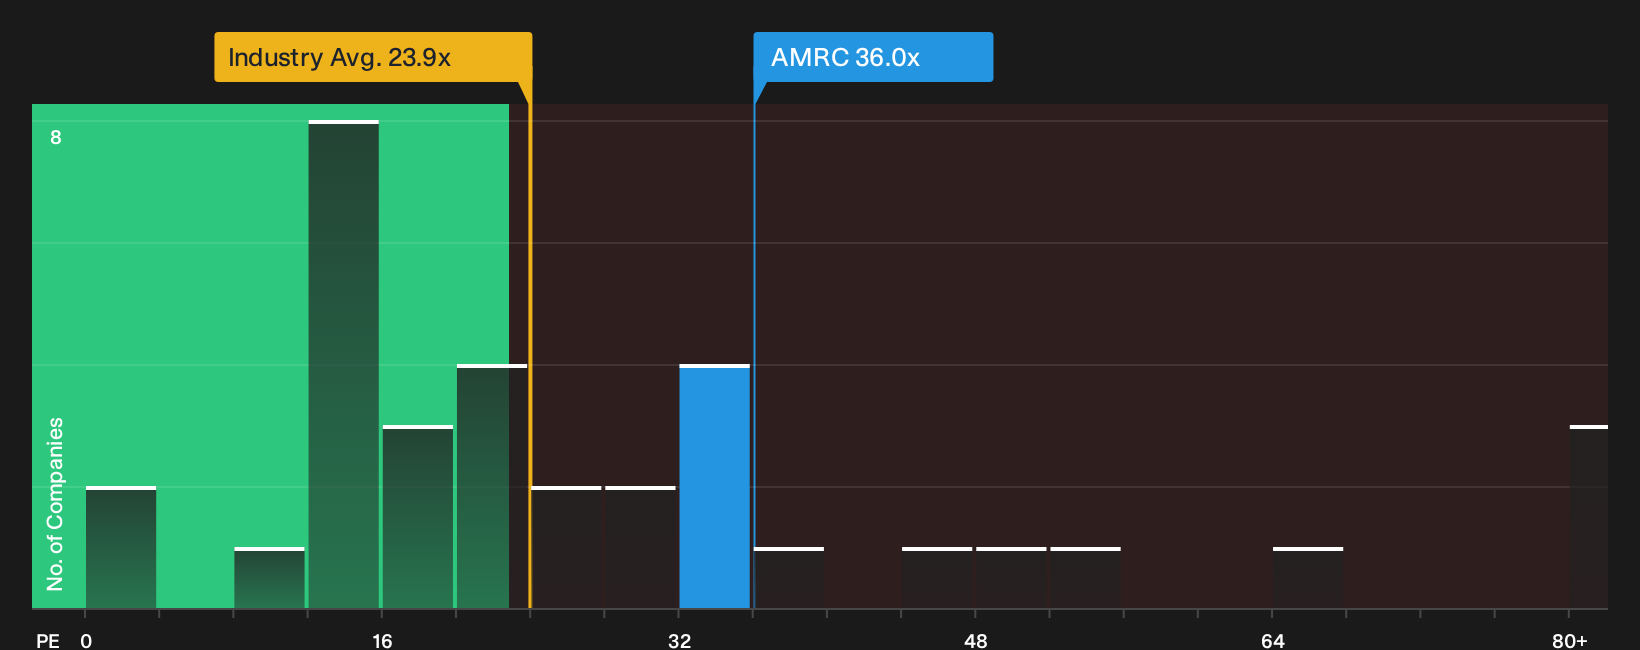
The P/E multiple fits Ameresco because earnings remain the main yardstick most investors use for this kind of project driven energy business. Ameresco currently trades on a P/E of 36.0x, which is higher than the construction industry average of 23.9x but below the peer group average of 52.0x. That combination suggests the market is giving the stock a premium to the broader sector while still pricing it below some closer comparables that investors may see as higher quality or lower risk.
The in house fair P/E points to the kind of ratio that might be expected for Ameresco once its growth profile, margins, size and risks are blended together. The current 36.0x level sits close to that reference point. For you as a shareholder or potential buyer, the key question is whether the earnings Ameresco is generating and aiming for are strong and steady enough to justify paying roughly this kind of multiple for each dollar of profit today. Explore the numbers behind Ameresco's P/E valuation.
The Ameresco Narrative: What Would Justify Today's Price?
For Ameresco, Simply Wall St Narratives pick up where the P/E puzzle leaves off by spelling out the future growth, margin profile and earnings path that would need to occur for the current share price to look meaningfully higher or lower. Instead of stopping at a single ratio or model output, they describe the future business conditions that number depends on, which you can then watch over time to see whether they actually hold. These scenarios sit on Simply Wall St's Community page for you to explore in more depth.
One of the top community narratives on Ameresco: 55% undervalued
"Growing recurring O&M contract revenue and a rising base of operating energy assets, now above 820 megawatts with more than US$1.5b of long term O&M backlog..."
Discover why this Narrative puts Ameresco at 55% undervalued.
An open question for Ameresco that the valuation ratio alone cannot answer
Price multiples only tell part of the story, because the people steering Ameresco and the way their pay is structured can strongly influence how future decisions line up with shareholder outcomes. See who runs Ameresco and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com