


EN
Is Sezzle (SEZL) Reasonably Priced Or Starting To Look Stretched?
Sezzle has delivered a huge share price run over the past three years, which naturally puts the focus on whether that move still lines up with what the business is earning today. With the stock recently closing at US$155.0, investors are increasingly asking if the current valuation can be grounded in its profit stream rather than just its price chart.
- Over the past three years the stock has returned a very large multiple on capital. That raises the question of how much of that gain is supported by the underlying earnings power of the business.
- Recent company updates point to strong growth in total transaction volume and higher expectations for both revenue and adjusted net income, which can support a richer earnings profile if those trends hold.
- There is a second opinion on Sezzle worth weighing. See what analysts think Sezzle's shares could be worth.
The stock's next move may depend on whether Sezzle's current earnings justify the price investors are being asked to pay today.
If you are weighing whether Sezzle’s earnings justify this kind of move, it can help to compare it with a wider set of companies screened for 42 high quality undervalued stocks.
Does Sezzle Look Pricey on Earnings?
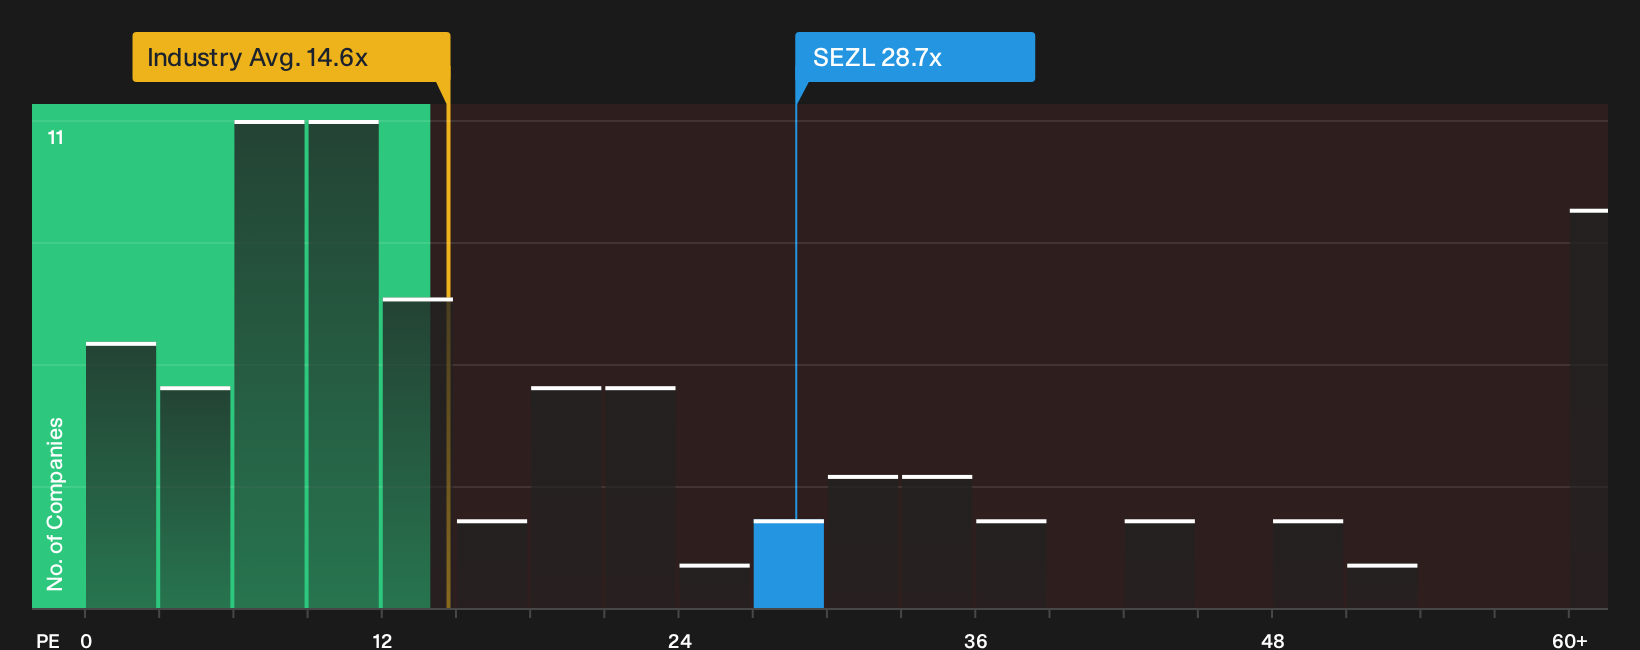
The P/E ratio is a straightforward way to see how much you are paying for each dollar of Sezzle’s earnings. On this measure, Sezzle trades at about 28.7x earnings, which is below the peer group average of roughly 37.8x and well above the broader Diversified Financial industry on 14.6x.
The valuation model that blends Sezzle’s growth outlook, margins, size and risk points to a lower P/E as a rough anchor. On that basis, the current 28.7x appears overvalued in that framework, even though it does not look stretched against faster growing peers. Because management recently raised guidance and flagged higher adjusted net income for 2026 and 2027, the market appears willing to keep paying a premium multiple for these earnings. That leaves you weighing how durable those profits are and how much of that optimism is already reflected in the 28.7x tag. Explore the numbers behind Sezzle's P/E valuation.
The Sezzle Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Sezzle pick up where this valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would logically support a much higher or lower price than today. They sit on the platform’s Community page. Each narrative links a specific fair value estimate to a clear story about Sezzle's potential catalysts and key risks so you can see which version of events is actually unfolding over time.
Community views on Sezzle split sharply today, with one camp seeing more runway in the subscriber model and another warning on BNPL risks and valuation.
Bull case: 8% undervalued
"Sezzle’s push to broaden its offering beyond point-of-sale BNPL into services such as subscriptions, deposit-style products, mobile plans, SezzleCash, Sezzle Send and longer term lending creates more ways to earn from each user over time..."
Discover why this Narrative puts Sezzle at 8% undervalued.
Bear case: 78% overvalued
"This thesis argues that SEZL’s path to mid-cap status is speculative at best, with slowing revenue growth, persistent bad debt provisions, and international expansion risks likely to compress multiples and erode shareholder value..."
Explore why this Narrative puts Sezzle at 78% overvalued.
One more angle on Sezzle that could change how you see this valuation
There is a final piece worth checking before you move on, which is where professional earnings projections place Sezzle a few years from now compared with the price you see on screen today. Explore where analysts expect Sezzle to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com