


EN
Chord Energy (CHRD) Stock May Be Undervalued As Asset Sale Plans Loom
Chord Energy has delivered a 60.7% share price gain over the past five years, yet its recent swings leave a clear question for investors who anchor decisions on earnings. After a sharp pullback in the past week and fresh headlines around portfolio changes and capital returns, the issue now is how well the current price lines up with what the business is earning.
- The 60.7% return over five years puts real weight on whether Chord Energy's earnings can support that kind of longer term shareholder outcome.
- Recent updates on production, asset sales and shareholder payouts may influence how stable and repeatable the company's earnings base looks over time.
- There is a second opinion on Chord Energy worth weighing. See what analysts think Chord Energy's shares could be worth.
For investors, the debate is whether Chord Energy's current share price around US$132 is adequately explained by the level and quality of its earnings today.
If you want a wider yardstick for Chord Energy's recent swings around earnings, try lining it up against 42 high quality undervalued stocks.
Does Chord Energy Look Undervalued on Earnings?
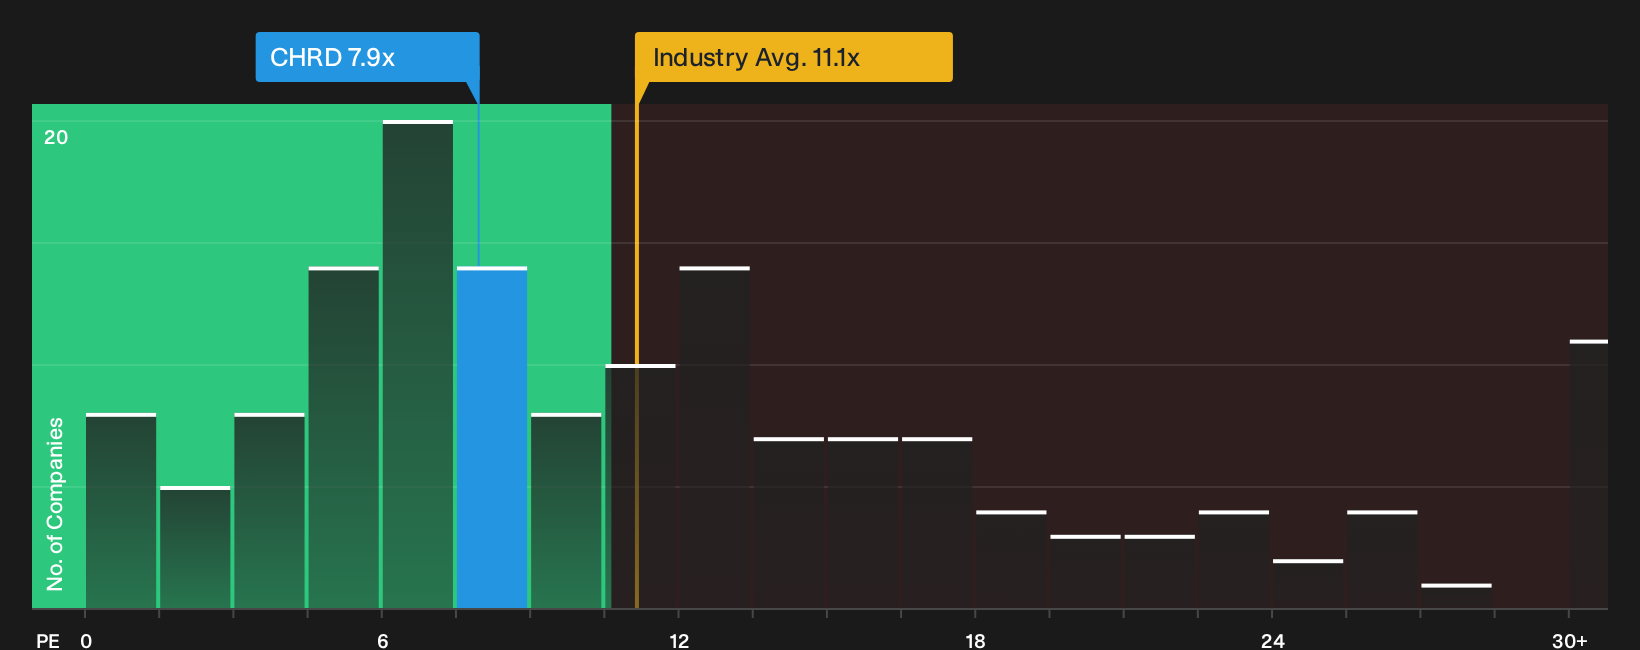
The P/E ratio fits Chord Energy because earnings are a key reference point for a producer that is throwing off material cash flow. On this measure, Chord Energy trades on a P/E of about 7.9x, compared with roughly 11.1x for the wider Oil and Gas industry and about 8.7x for its direct peer group. Based on a tailored fair multiple that takes its growth profile, profitability, scale and risk into account, that reading screens as undervalued rather than stretched.
Because the company has just reported strong Q3 2026 results and flagged divestment plans, the current discount on the P/E ratio suggests that the recent news has not fully closed the gap that the model implies. For anyone weighing Chord Energy at around US$132, the key question is whether the earnings power behind that 7.9x figure looks durable enough to justify a higher multiple over time, or whether the lower rating is an appropriate cushion for sector and company specific risks. Explore the numbers behind Chord Energy's P/E valuation.
The Chord Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Chord Energy leaves off by spelling out what kind of future growth, margins and earnings profile would need to hold for the stock to end up worth materially more or less than today's price. Each scenario ties a fair value to a particular mix of potential catalysts and hazards for Chord Energy's business, so you can watch over time which storyline looks closest to reality.
One of the top community narratives on Chord Energy: 27% undervalued
"Expanded use of AI supported base production optimization across roughly 5,000 operated wells ... points to incremental production volumes that can lift revenue and free cash flow…"
Discover why this Narrative puts Chord Energy at 27% undervalued.
Chord Energy’s valuation still hinges on who is steering it
Numbers only go so far, because what really shapes Chord Energy’s future earnings power is the people setting priorities, picking projects and deciding how they pay themselves. See who runs Chord Energy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com